

The most important signal from Wise PLC (Nasdaq: WSE; LSE: WISE) Fiscal 2026 report, released on June 25, was not in the financial data. Instead, it came when Cris Kennedy at William Blair pressed Emmanuel Thomassin, CFO, for color on Q1 FY27 take-rate cadence. Thomassin gave it without hesitation:
“We took the take rate by 1 basis point down in the first quarter ... 1 to 2 basis points each quarter.”
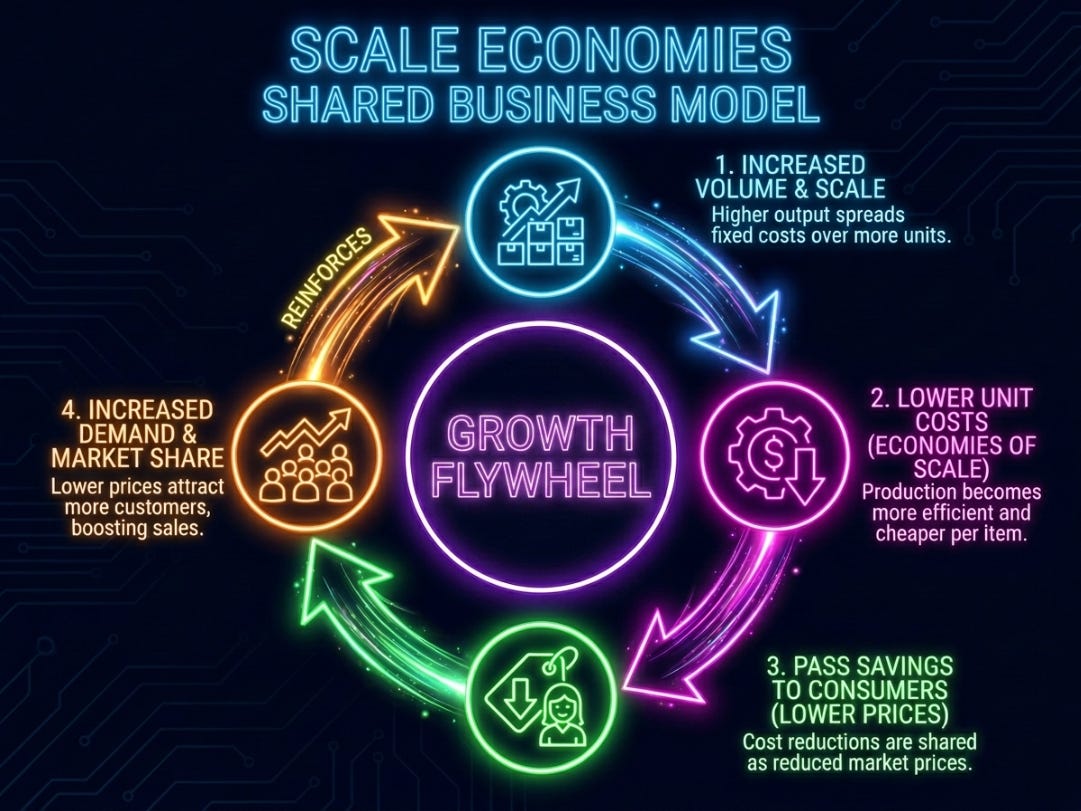
This is important for two reasons - firstly, it shows the scale economy shared (SES) flywheel continues to spin. Secondly, a management team in trouble generally does not pre-commit to compressing its take rate unless it’s a) inept or b) executing exceptionally well. Our read is b), and it appears the market read it the same way, as shares moved up ~10% after the release.
The deep dive published in May argued that Wise’s status as a compounder is driven by its SES flywheel, spinning ever faster as more people use the platform, and as Wise then passes those savings back on to the users, continually accelerating the spin.

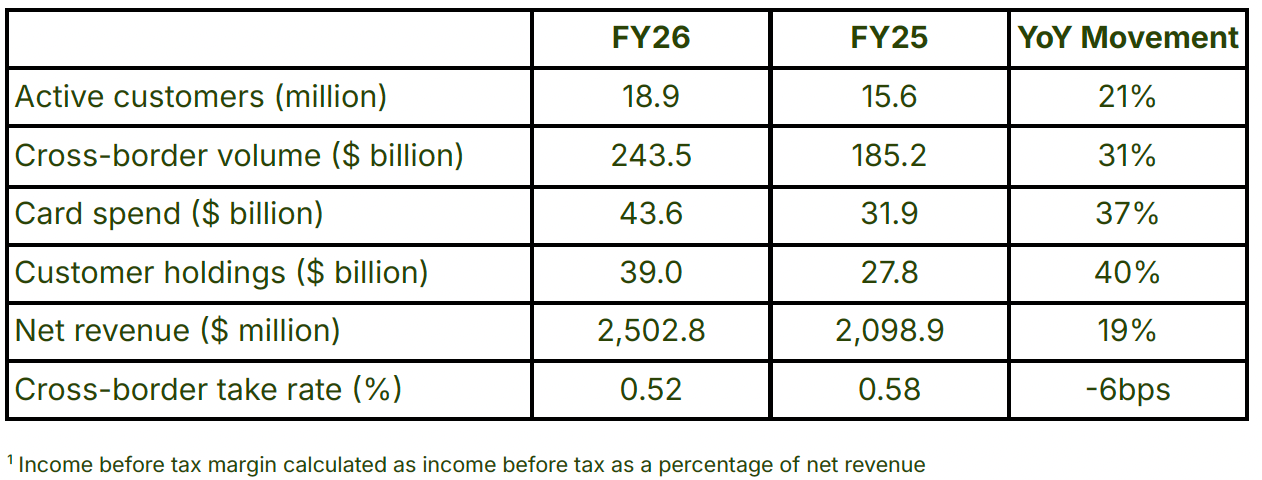
FY26 is the first full reporting period after that publication, and we see a body of evidence in favor of that thesis. The blended take rate compressed 6 basis points to 0.52%. Cross-border volume grew 31%. Customer holdings grew 40%. Card spend grew 37%. Wise Business volume grew 42%. Management then announced a new $500 million-plus share-purchase program, the largest in company history, with 60% earmarked for treasury buyback.
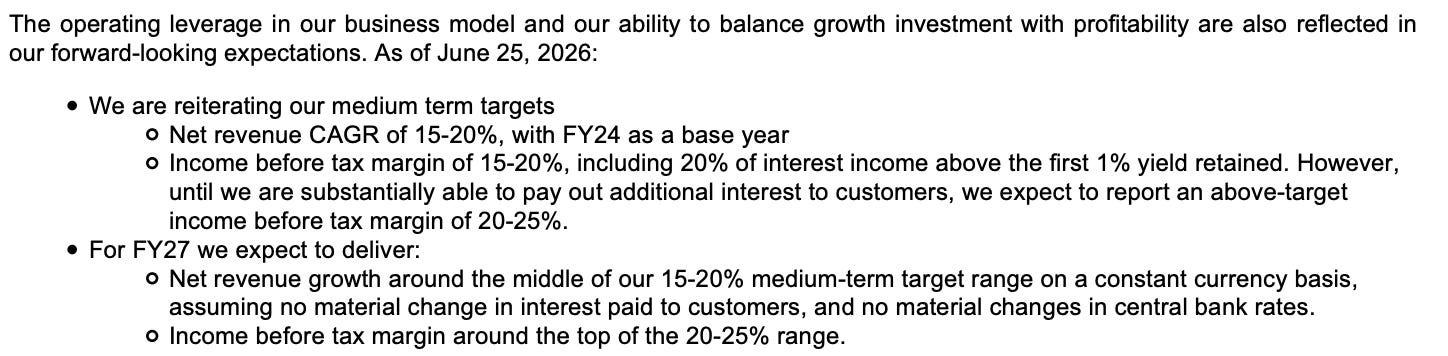
Management provided the following guidance for FY 2027:
There are some items to unpack further though - operating expenses grew 39% as the company added 2,300 employees and built into Brazil, Japan, South Africa, the UAE, and Thailand. Furthermore, there is also a European regulatory over-hang worth watching. Nonetheless, we think the thesis is working.
Let’s break it down.
The Financials
With the May Nasdaq primary listing, reporting is now in U.S. dollars. For FY 2026 net revenue came in at $2.50 billion, up 19%. Income before tax (IBT) of $660 million on a 26.4% IBT margin. Customer holdings of $39 billion, with $30 billion sitting as customer balances and $9 billion held in Wise Assets.
Revenue
Cross-border revenue grew 17% to $1.26 billion on 31% volume growth, with card revenue growing 40% to $392 million. Other revenue grew 26% to $245 million, including Wise Assets, which launched in Brazil during the year. Transaction revenue totaled $1.89 billion, up 22%.
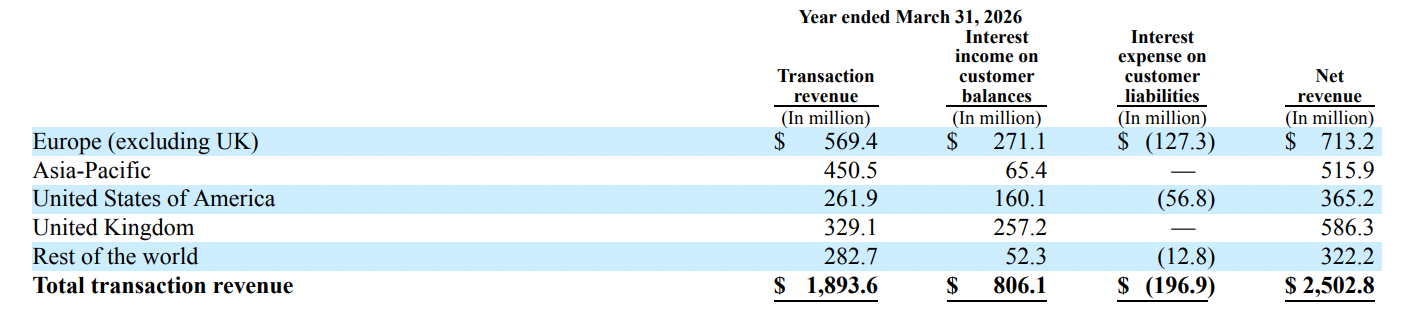
We see that the majority of the Transaction Revenue stems from Europe (including the UK) and Asia-Pacific, with the U.S and Rest of the world being a smaller contributor. When it comes to NII, interestingly APAC is fairly insignificant.
Wise holds $30 billion of customer balances on the balance sheet and another $9 billion of customer assets under custody in the Wise Assets product. These funds are segregated and safeguarded, meaning they are not the company’s cash, but the investment of those funds drives the entire net interest income line. At an average gross yield of 3.0% on $26.8 billion of average balances, it works to the $806 million of reported interest income.
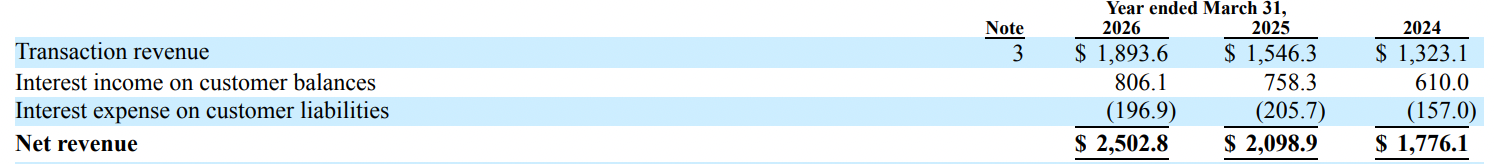
As long as customer balances grow faster than rates compress, NII grows. This high-margin revenue converts 100% to cash, and allows management to self fund investments in the business.
Margins and Operating Items
The IBT margin landed at 26.4% versus 34.2% a year ago, an 800-basis-point compression that looks shocking at first glance. However we must be mindful of two things. Firstly, the SES model means margins are supposed to be kept low, as management continually passes the savings onto the customer. Wise guides for 20-25% IBT margins in the near term, so 34.2% is unusually high.
Second, there were two true one-off GAAP items that were recorded, as a consequence of the Nasdaq listing: $45 million in core function costs tied to the Nasdaq listing, and a $70 million U.S. GAAP expense adjustment related to FX fluctuations on U.K. government bonds, due to transitioning from IFRS to US GAAP rules.
If we strip both one-offs, the operating margin sits closer to 28% than 26%. The remainder of the compression is from higher expenses. Headcount went from 6,500 to 8,800, marketing spend grew 60% to $172 million, servicing grew 38% to $397 million and technology grew 38% to $434 million.
The bullish analysis is that Wise is executing its SES model, continually investing in its business and lengthening the runway for future growth. The bearish analysis is that Wise is under competitive pressure and has to continually invest to defend its position.
We think the bullish interpretation is more likely because Wise’s increased spending has triggered customer acquisition and volume growth, proving that the investments are driving efficient expansion rather than merely defending market share. Furthermore, the tech and headcount investments secured direct integrations into regional payment systems like Japan's Zengin and Brazil's Pix, alongside high-profile B2B partnerships with institutions like UniCredit.
This all continually allows Wise to lower its take rate to starve out competitors, building a longer-term structural cost advantage.

Cash Flow
Because Wise is structurally asset-light (no inventory, no receivables drag, minimal capex outside capitalized software), which means reported IBT translates into operating cash flow at a high rate.
The capital expenditure footprint is small but worth noting. The $434 million of technology and development spend includes salary and capitalized software for the 1,000+ engineering organization that deploys roughly 6,000 times per month. There is no large physical-infrastructure capex line.
The largest investment of FY26 was “Purchase of Available-For-Sale debt securities” - primarily U.S. and U.K. Government bonds.
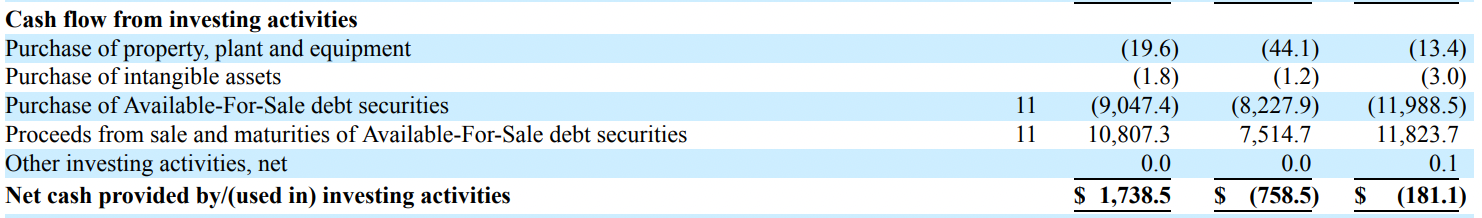
Balance Sheet
Cash and cash equivalents came in at $27.8 billion with total current assets of about $33 billion, although $30 billion of this is customer balances (“funds payable and amounts due to customers" line item).
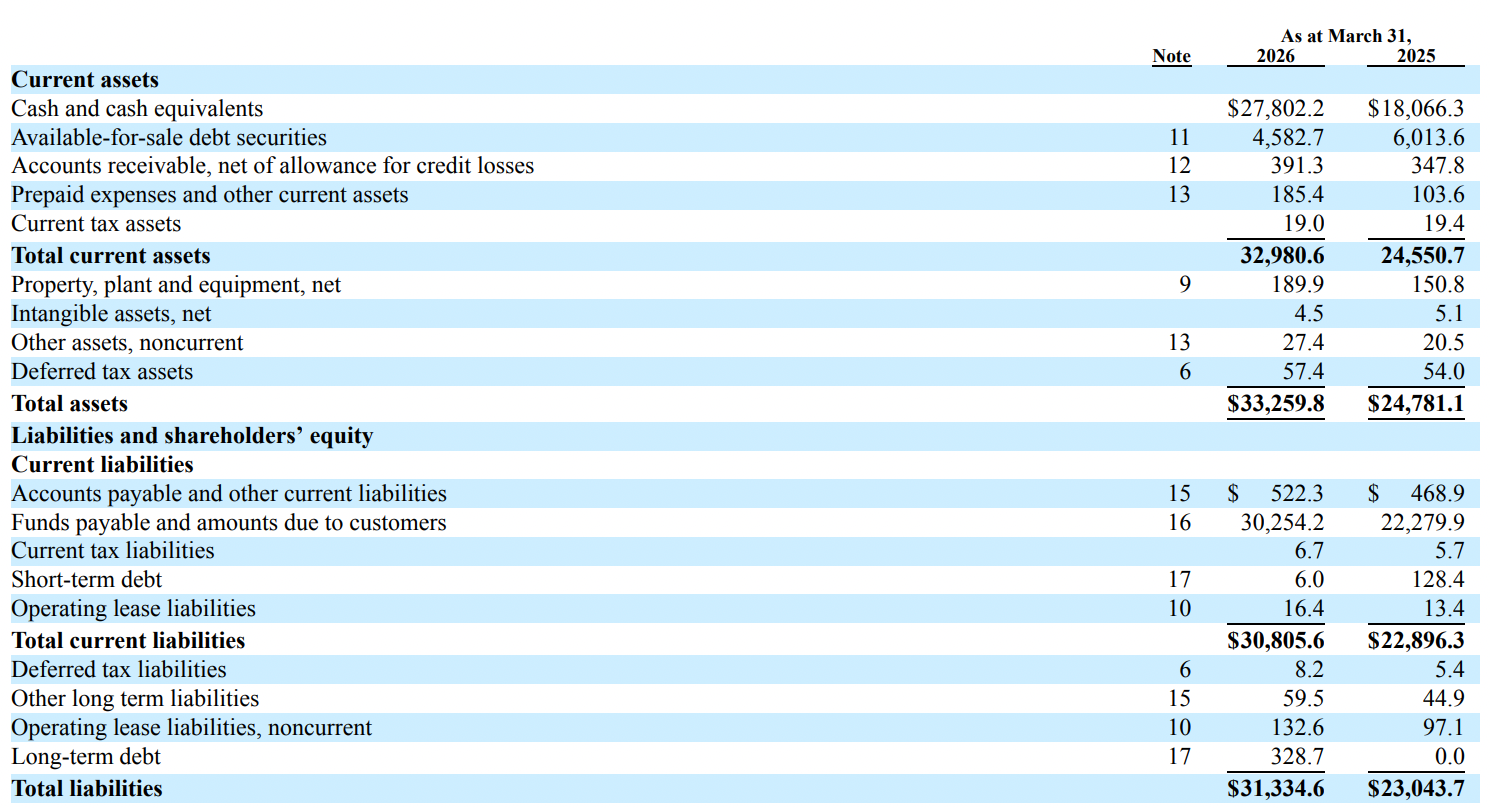
The customer-balance composition is $18.8 billion Personal and $11.2 billion Business, with Business balances growing 33% year over year against Personal balances at 38%.

Personal is still the larger pool, but Business is more meaningful. Business balances tend to be stickier because they fund payroll, supplier payments, and FX hedging needs.
On the company’s own side of the balance sheet, the capital structure is conservative with little debt. There is still the £2 billion Euro medium-term note program, established in November 2025, which gives Wise standing access to public debt markets without requiring a fresh roadshow for each issuance. The £250 million of unsecured notes due 2030 sit inside that program.
The £330 million multicurrency revolving facility (three-year term, signed December 2024) provides standby liquidity. These facilities are oversized relative to current needs, which is the proper conservative stance for a regulated financial-services business managing 80+ licenses globally.
An Update on Capital Allocation
Capital allocation is the CEO’s most important job, and how they allocate capital often determines the long term success, or failure, of the company.


For a company in the growth phase of the corporate lifecycle, reinvesting in the business is often the most prudent use of capital. Wise continues to reinvest heavily into its business, however in FY26 Wise also increasingly returned capital to shareholders via buybacks.
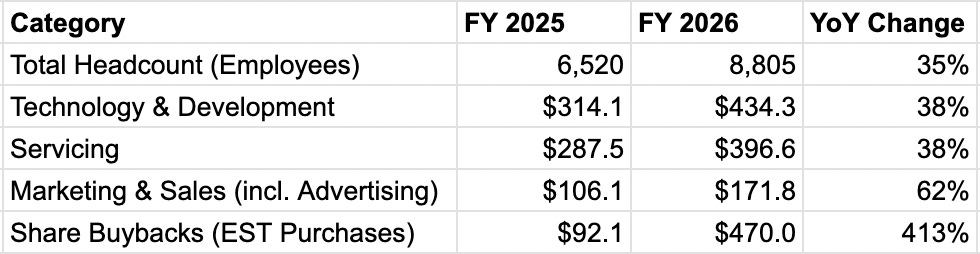
They deployed $470 million to purchase 35.9 million shares into the Employee Share Trust, at an average price of roughly $13. Part of the repurchases went towards offsetting dilution from employee options, and so there was a net decrease of about 11 million shares outstanding.
The new announcement is a fresh share-purchase program "expected to be over $500 million," with approximately 40% (around $200 million) flowing to the EST and 60% (around $300 million) flowing to treasury buybacks. The treasury portion is the first material open-market buyback in company history, and Thomassin framed the program explicitly as an annually-reviewed framework rather than a one-time decision.
If Wise were levering up, starving its R&D or cutting marketing to fund these buybacks, it would be a red flag. However, the financial data shows they are doing the exact opposite. The bullish read is that the business is so cash generative they hit the law of diminishing returns on internal reinvestment, and thus are using the excess cash to return it to shareholders.
At an average purchase price of ~$13.00 these buybacks are likely to be long term value accretive as well. Hopefully, management will continue an opportunistic approach to buybacks, ramping them up when value accretive and ramping them down when not.
The Risks to the Compounder Thesis
Below the paywall in our May Wise Deep Dive we highlighted the following data points that we wanted to monitor, to track the validity of the compounding thesis.
The SES and the Take Rate
If the take rate falls below 50bps without a corresponding step-up in volume growth, then this signals that competitive pressure has overwhelmed the scale economies, not enabled them. - Wise Deep Dive
FY26 produced 31% cross-border volume growth on a 6bp take rate compression. That is the SES flywheel doing what it is supposed to do. Thomassin’s comment on the call was that price is “the number one argument for customers to come to us” and that the company “does not put any floor, any limits.”
That is a management team that knows the flywheel is its core business model, and they are leaning into it.
Wise went live with direct connections into Pix (Brazil) and Zengin (Japan) in FY26, and added payment licenses in South Africa, the UAE, and Thailand. Each direct connection meaningfully reduces unit cost on the relevant corridor and is the mechanism by which the take-rate cuts get funded.
Wise Business Volume
With retail penetration at 5% but SMB penetration at less than 1%, the business segment is the primary engine for future compounding. If this growth stalls, then either the runway is much shorter than anticipated, or the competitive pressure is too great for Wise to surmount. - Wise Deep Dive
Business cross-border volume grew 42% to $70.5 billion, while Business active customers grew 27% to 572,000. The Wise Platform business specifically represented roughly 5% of cross-border volume during the year and remains on its medium-term path to 10%.
Capitec, the largest South African bank by customer count, went live in April 2026 and is not in the 5% figure, which means the Q4 exit rate and FY27 starting rate are both higher than reported. We’ll see the impact of this on the Q1 27 financials.
Wise Platform
If Wise Platform fails to add a top-five global bank within the next two to three fiscal years, then the infrastructure optionality we are paying for is impaired. - Wise Deep Dive
In FY26 Wise added UniCredit, Raiffeisen Bank International, MBSB Bank Malaysia, and Capitec. UniCredit and Raiffeisen are European banks with material flow, and Capitec brings Wise into the African continent for the first time. However, none of these are global top-5.
Kristo’s commentary on the call was that the pipeline contains names “you’re going to be hearing about,” and that the year ahead should bring both new platform partners and deeper embedding with existing ones.
We treat this as credible signal and it shows that the Wise platform is growing.
Stablecoins
Stablecoin transaction volumes will likely keep growing. If, by FY28, Wise has not established itself as a top-three regulated on/off-ramp for fiat-pegged stablecoins, then tokenisation is bypassing its rails and disintermediating the business. - Wise Deep Dive
The earnings release, the analyst deck, and the conference call contain zero mention of stablecoins. It may just be a reflection of the current cryptowinter the market is experiencing; nonetheless stablecoins are a credible threat to undercut the SES model. The company’s response to stablecoins is worth monitoring.
Other Developments
There are two other developments worth tracking as well, that are new since the Deep Dive was published.
European Money Laundering Allegations
Belgian authorities, specifically the Brussels Public Prosecutor’s Office, are currently investigating Wise’s European subsidiary over significant anti-money laundering (AML) control lapses. The probe, which was initiated after Wise accounts repeatedly appeared in cross-border law enforcement requests, centers around roughly €500 million ($583 million) in suspicious transactions spanning more than 30 European countries.
At the heart of the investigation are allegations of “structural indications of non-compliance” with established AML legislation. Prosecutors suspect that Wise failed to adequately identify high-risk clients through robust Know Your Customer (KYC) processes and lacked the ongoing Enhanced Due Diligence (EDD) necessary to monitor customer activities.
In response to the probe, Wise confirmed it is cooperating fully with the authorities, asserting that such inquiries are a routine part of operations and do not inherently prove wrongdoing. The company noted that roughly one-third of its global workforce is dedicated to fighting financial crime, and emphasized that no formal charges or specific findings have been shared with them yet.
This latest regulatory scrutiny compounds a troubling compliance trend for the fintech giant, following a $4.2 million fine by six U.S. state regulators in July 2025 for similar AML deficiencies and a 2024 remediation plan imposed by the National Bank of Belgium over missing customer documentation.
For investors, this pattern raises structural concerns about whether Wise’s frictionless, high-speed transfer model inadvertently makes the platform an attractive pipe for illicit financial flows, thereby elevating long-term regulatory risk. To be fair, the $583 million in suspicious transactions represents approximately 0.24% of the $243 billion cross border flows.
Craig McDowell at JPMorgan asked about recent European money-laundering headlines and a prosecutor matter. Kristo’s response was that there is no new update from the prosecutor, that the interaction is infrequent, and that business continues as usual.
Office of the Comptroller of Currency (OCC) Application
On June 16, 2025, Wise submitted an application to the Office of the Comptroller of the Currency (OCC) to establish the Wise National Trust (WNT). This proposed non-depository national trust bank is designed to significantly upgrade Wise’s global payment infrastructure and broaden its fiduciary capabilities for its customers in the United States.
If approved, WNT would operate under US federal supervision and unlock several strategic advantages for the company. It would enable Wise to offer a custodial account structure eligible for FDIC pass-through insurance by safely placing customer funds with third-party insured banks.
Right now, a lack of direct FDIC insurance limits how much money a cautious user or a mid-sized business is willing to hold in a Wise account. By offering FDIC protection, Wise becomes a safe haven for much larger cash balances, which directly fuels their Business deposit growth.
Currently, Wise operates in the U.S. using 48 separate state-level money transmitter licenses. That means dealing with 48 different regulatory bodies, 48 different sets of rules, and 48 different reporting requirements. An OCC national charter brings federal preemption - meaning Wise would be regulated by a single federal entity. This would streamline compliance operations, reduce long-term SG&A expenses, and free up capital. It would also signal a level of regulatory maturity that puts Wise on par with legacy institutions, lowering the barrier to entry for securing large enterprise clients.
The application is undergoing the OCC’s standard and rigorous review process. In the interim, Wise continues to operate its U.S. business effectively by utilizing its existing network of 48 state-level money transmitter licenses.
Below the paywall we’ll provide an updated Reverse DCF, calculating the Price-Implied Expectations (PIE) baked into the current $12.19 share price.
We’ll also provide an updated Three Stage DCF with a breakdown of our Bear, Base, and Bull case scenarios, projecting revenue fade, terminal margins, and the ultimate implied share prices.
Finally, we’ll close with our Verdict, to determine if Wise offers an actionable entry point today. Paid subscribers will be able to download both models.