

Investors in Adobe (ADBE) have had it tough - it’s down over 30% over the last five years. Imagine trying to be a patient long only investor and sitting in this stock. Certainly not easy, or comfortable.
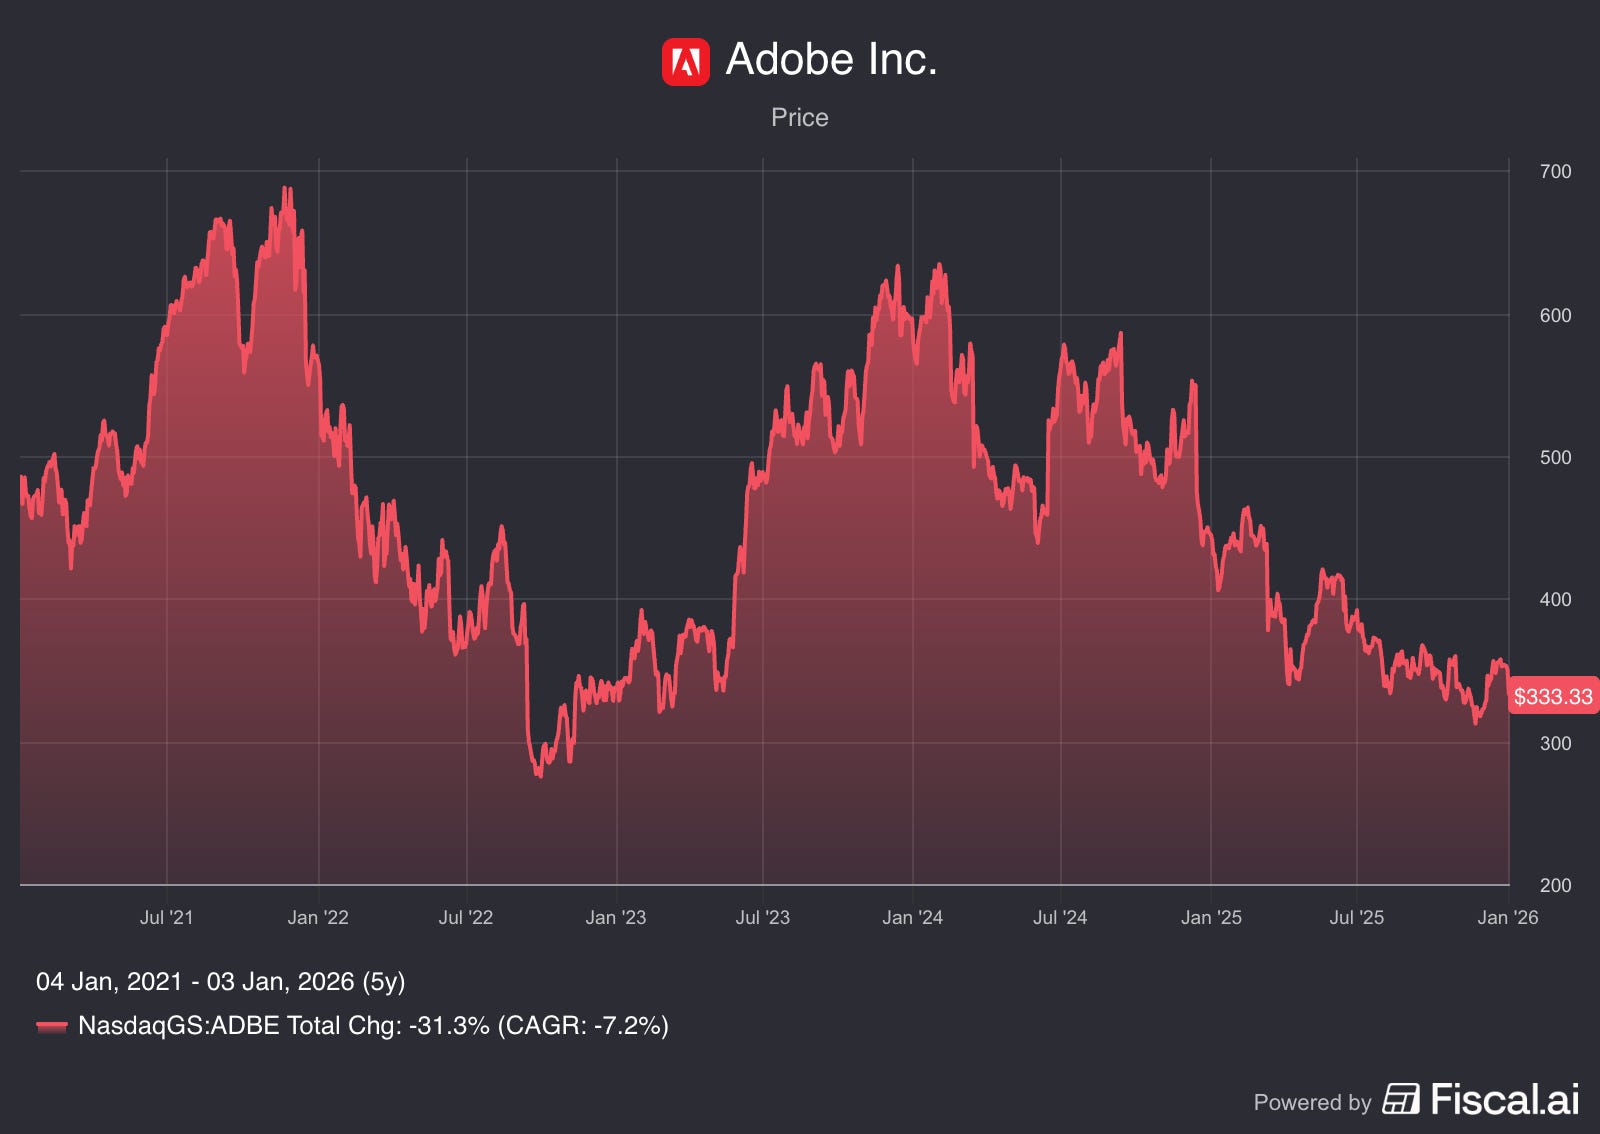
There seems to be no shortage of negative narratives surrounding Adobe - from the failed acquisition of Figma, the FTC lawsuit over predatory pricing, and currently, that Adobe is an AI Loser.
The argument is that generative AI tools like Midjourney, Sora, and Canva will democratize design to such an extent that professional creatives will become obsolete. As corporate design teams shrink, “Seat Compression” will set in, churn will spike, and Adobe’s terminal value will erode.
However, when we examine Adobe’s recently closed Fiscal 2025, a stark disconnect emerges between the fear of disruption and the operational reality.
The Gap Between the Narratives and Numbers
If Adobe were truly being disrupted by AI right now, we would see it in the financials. We would see flat or declining revenue, shrinking backlogs (RPO), and compressing margins as they fight a price war.
Instead, the financials tell a story of resilience.
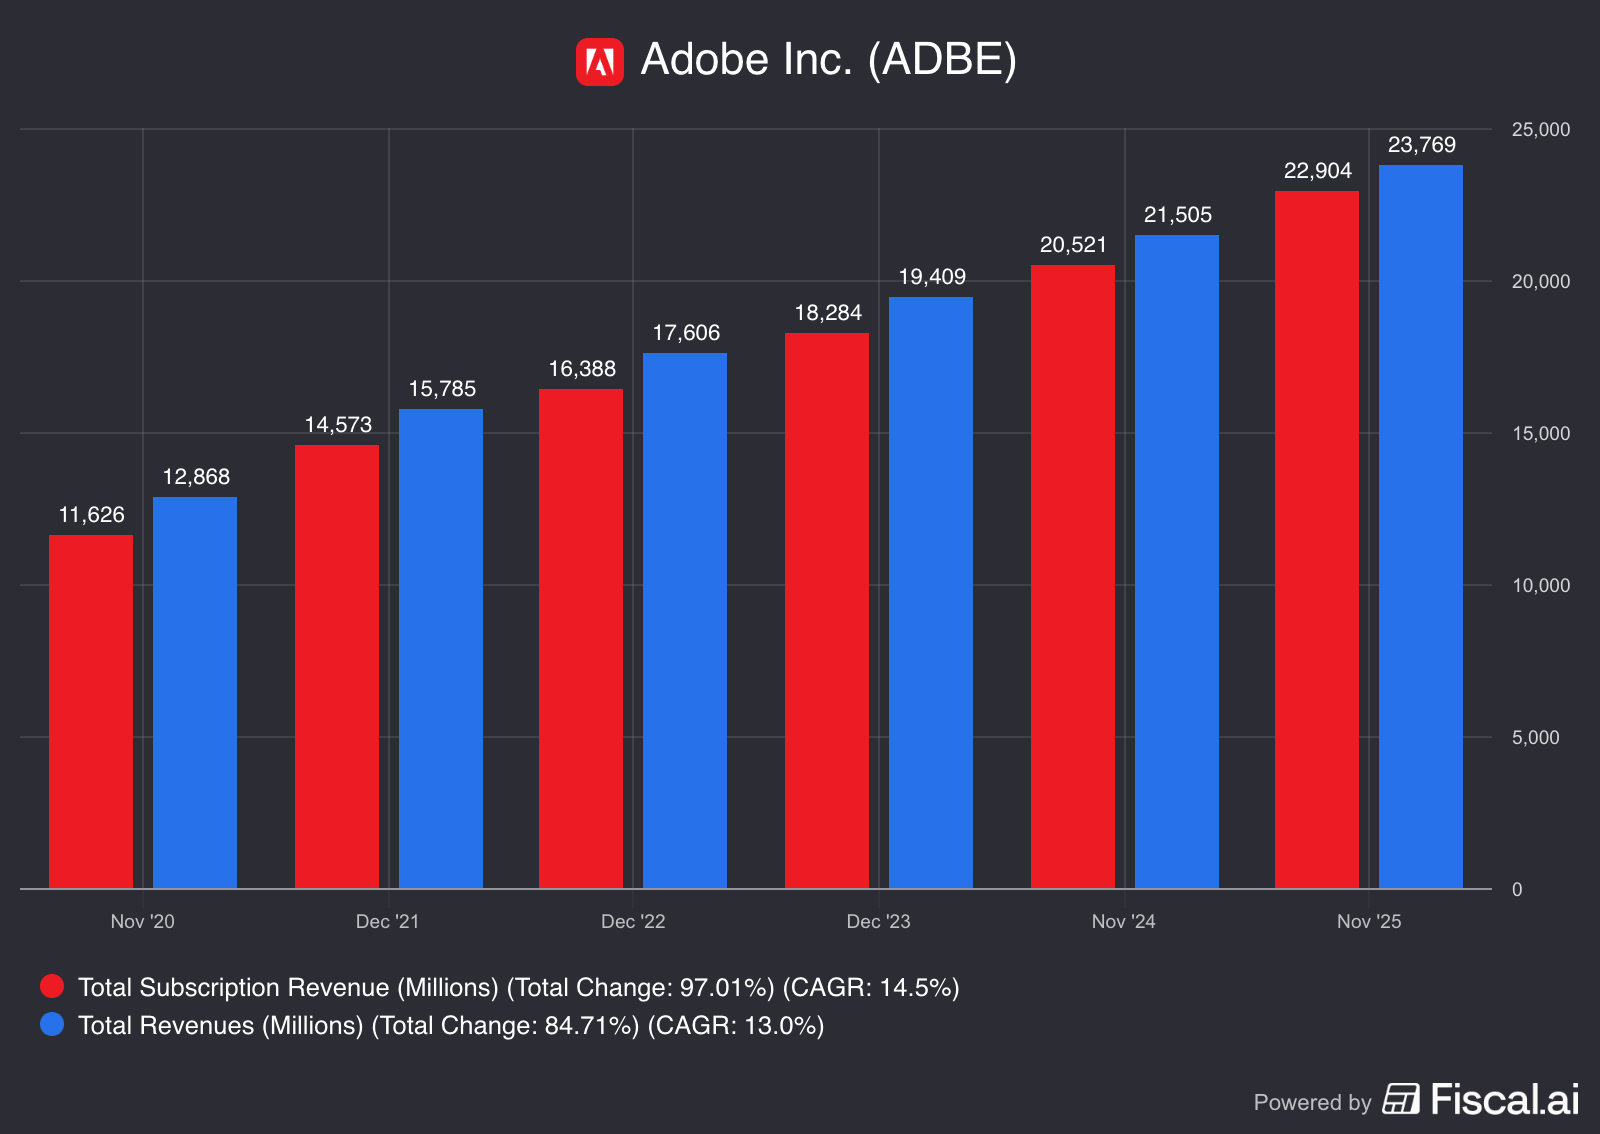
Total revenues continue to grow, with highly sticky subscription revenue growing at high single digits.
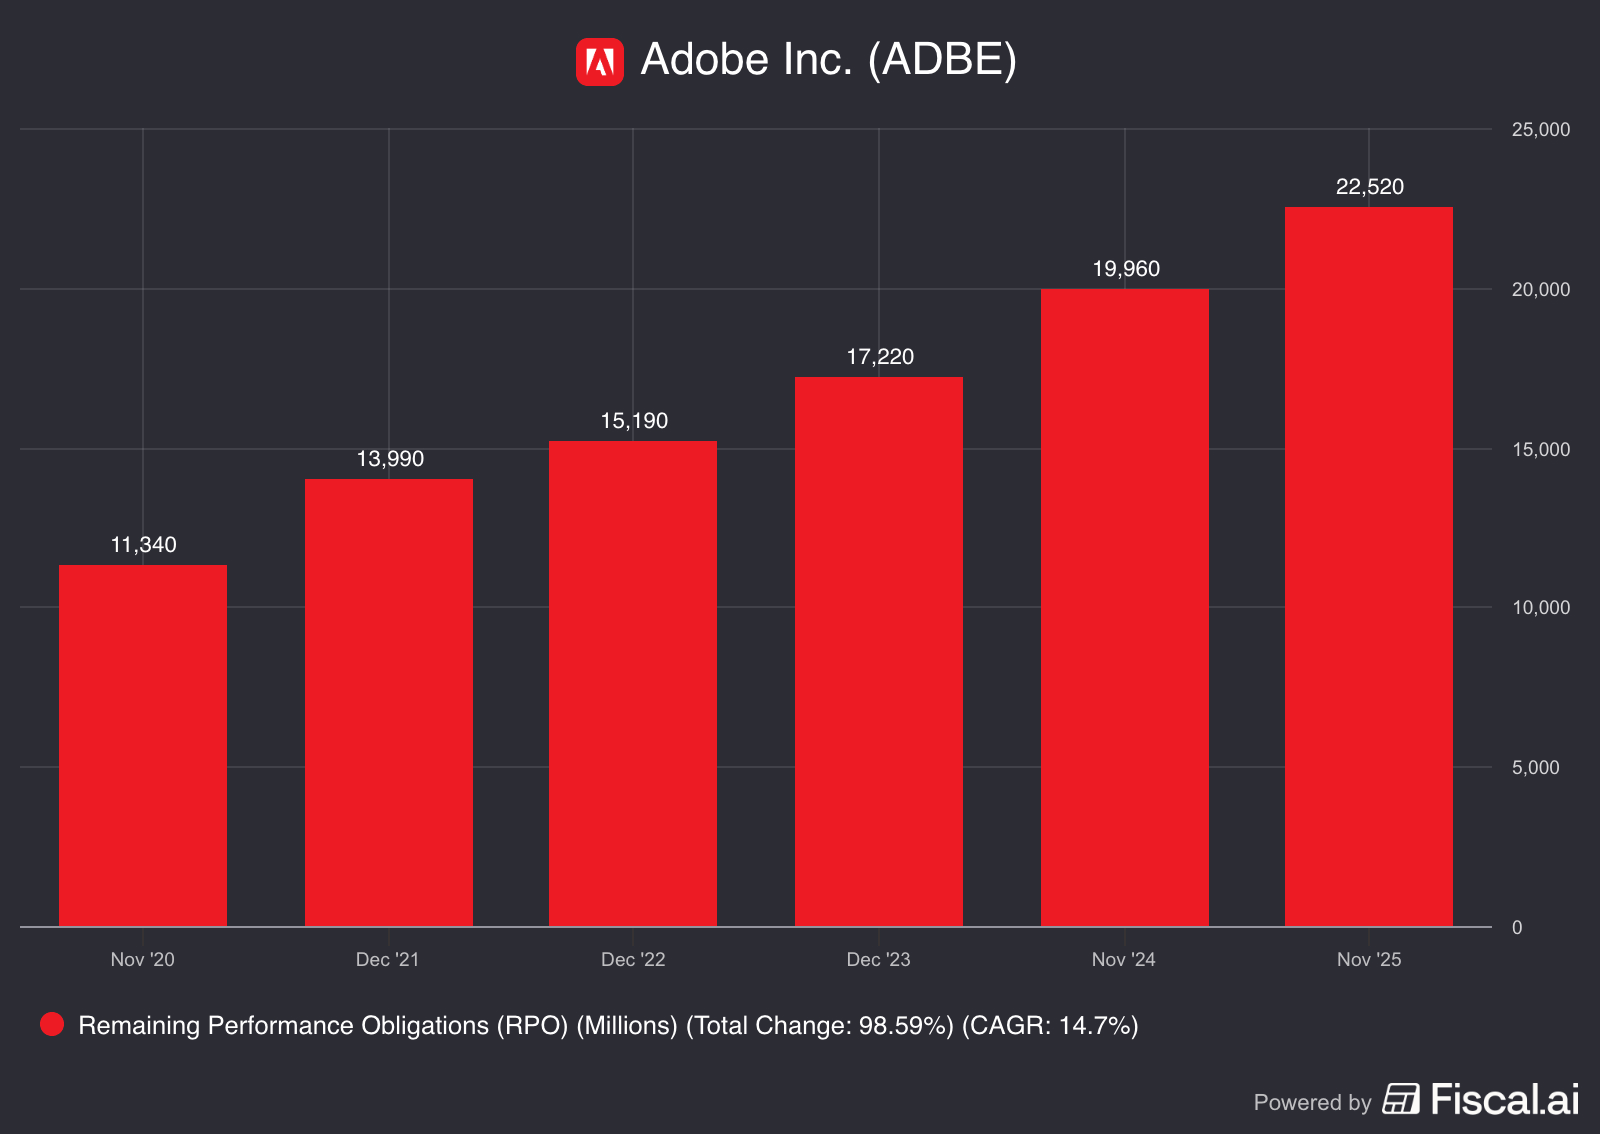
RPO (Remaining Performance Obligations), the metric that represents future revenue under contract. It grew 13% YoY to $22.5 billion.
“By advancing our innovative generative and agentic platforms and expanding our customer base, we are excited to target double-digit ARR growth in FY2026” - Dan Durn, Adobe CFO, Q4 2025 Conference Call
RPO is significant as it provides future visibility into Adobe’s revenue. If Enterprise CIOs believed they could replace Photoshop with a prompt in 6 months, they wouldn’t be signing long-term contracts today.
When we look at their margins, we see a slight wobble in Fiscal 2023 / 2024 although a bounce back in Fiscal 2025. The wobble was due to the $1 Billion Figma break up fee in 2023, while 2024 marked an investment year where ADBE was investing into its business.
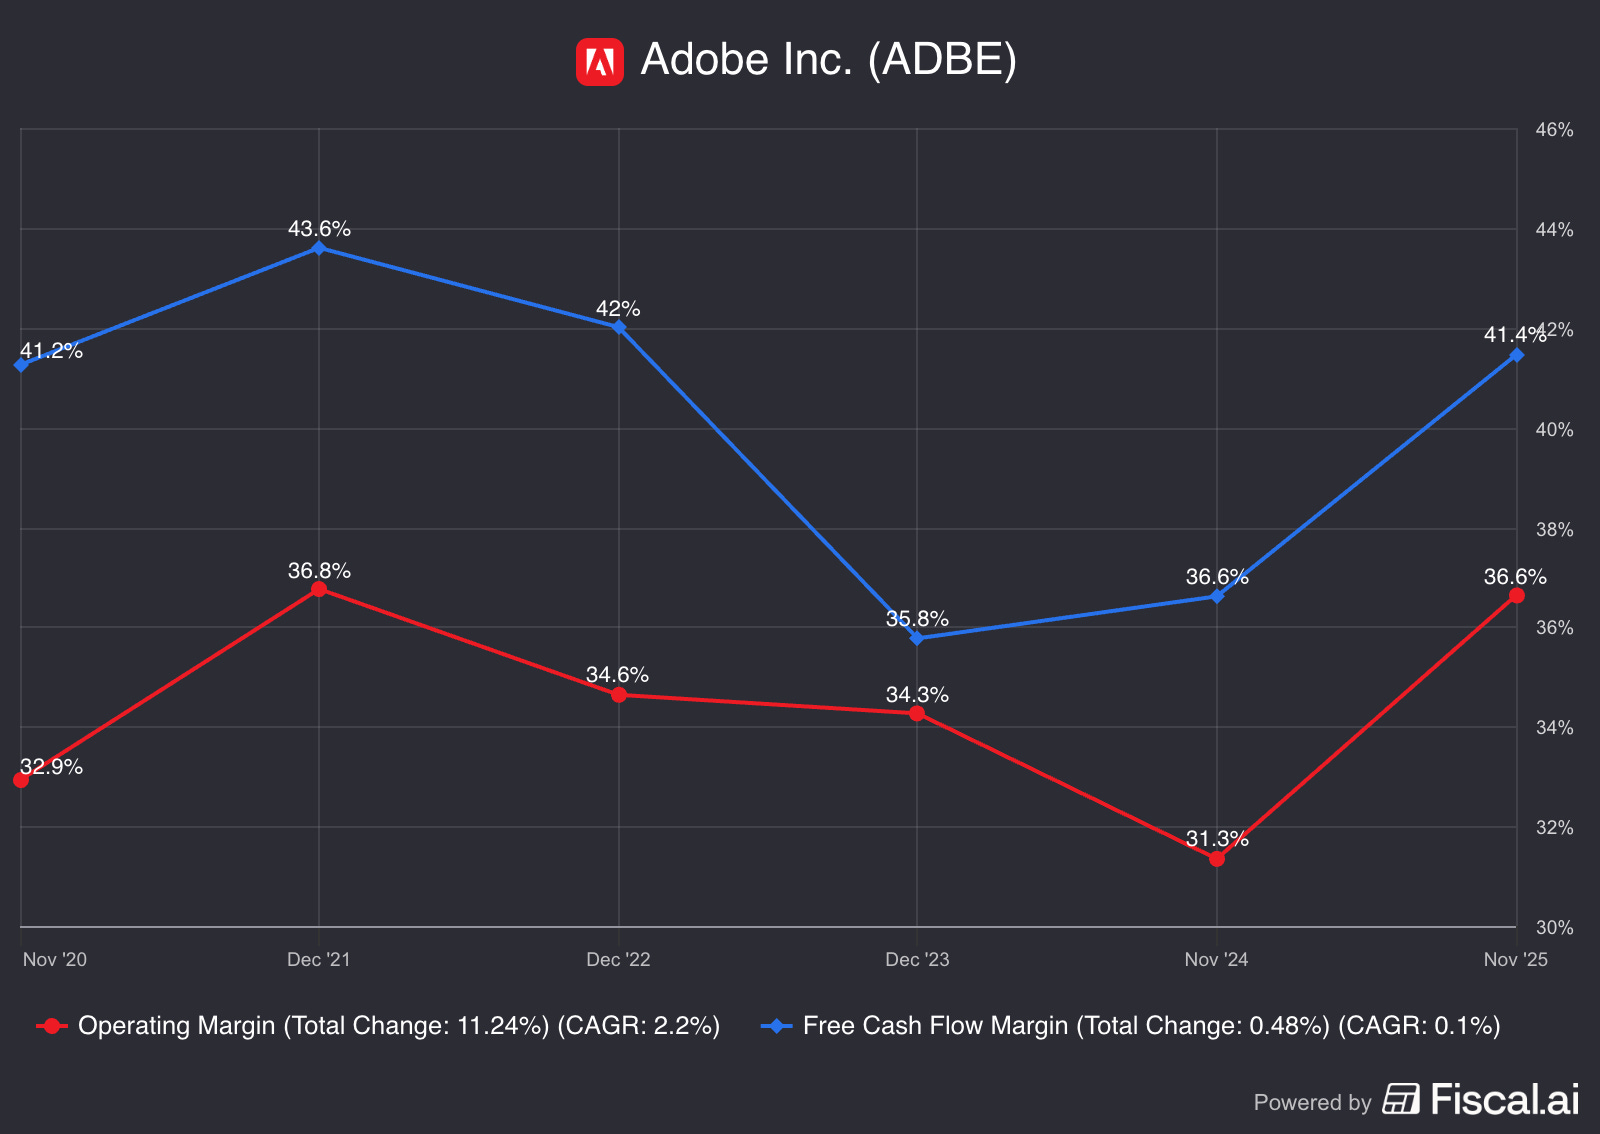
As the free cash flow margins are equally resilient, we can see that the margin preservation is not an income statement illusion.
This is not the profile of a dying incumbent; it is the profile of a durable compounder.
The Overlooked Moat: Legal Safety
The bear case assumes that a Fortune 500 company cares only about the output of an image. They don’t. They care about the liability of the image.
This is Adobe’s hidden moat. While “wild” AI models are trained on the open internet (creating massive copyright risks), Adobe Firefly is trained on Adobe Stock—a clean, licensed dataset.
For a freelance designer, Midjourney might be fine. But for Disney, Coca-Cola, or Nike, “Copyright Indemnification” is a feature worth paying for. Adobe is effectively selling insurance alongside its software, making it the only viable option for the enterprise supply chain.
Integration vs. Disruption
The second flaw in the bear case is the misunderstanding of workflow.
Generative AI creates pixels, but it doesn’t create projects. You cannot edit a 90-minute film in a text prompt; you need a timeline. You cannot assemble a print-ready magazine spread in a chat window; you need layers.
Adobe is successfully embedding AI into the workflow (e.g., Generative Fill in Photoshop) rather than letting it exist outside of it. This increases stickiness. A designer using AI inside Photoshop is more efficient, and, still a subscriber.
What Investors Need to Watch
This is not to say the coast is clear - there are KPIs to watch to monitor for structural decay.
RPO (Remaining Performance Obligations): If this metric starts to decline, then it’s a clear sign Enterprise spend is looking elsewhere.
AI-influenced Annual Recurring Revenue (AI-ARR): If Adobe is truly integrating AI into their product offerings, then investors will see a clear measure of AI’s direct contribution to its recurring revenue. AI-ARR increased to $8 billion for Fiscal 2025, up from $3.5 billion in Fiscal 2024.
Operating Margins: If margins compress and stay compressed, then it implies Adobe is spending too much on GPU compute to deliver AI features without having the pricing power to pass those costs on to customers.
The Verdict
The market has de-rated Adobe from a premium stock (35x+ P/E) to a “show-me” story (15x NTM P/E).
For the value investor, this creates a potential opportunity. The investor can buy a business with 40+% FCF margins, double-digit growth, and a massive competitive moat at a discount created by uncertainty.
For those with full positions, continue to hold (like us). Although the share price movement hurts, the management continues to execute, the fundamentals continue to look strong, and management is buying back shares hand over fist.
The narrative says Adobe is dead. The fundamentals say it’s as strong as ever. Eventually the share price will match reality. In the meantime, investors need to watch the ARR and RPO, not the news headlines or rumors.
Thanks for reading! Please tell us where we could be wrong in the comments section below.
The Pursuit of Compounding 📈
Disclaimer: We are private investors and not financial advisors. This post is for educational purposes only and does not constitute financial advice. Adobe (ADBE) is a stock we currently own. Always conduct your own due diligence before making any investment decisions.
Thanks for sharing your analysis.
I don’t think I’ve seen anyone truly bearish on Adobe over the past few months. I don’t think a serious investor is explicitly saying, “Adobe is dead,.AI killed it,” unlike what you sometimes heard in 2024.
I agree with your point that this is a “show-me” story: the market is waiting for proof, mainly through the trajectory of AI-driven ARR and operating margins (as you also noted).
But I think the market is also watching two other variables:
- How generative AI technology evolves.
- How credible potential competitors, like Figma, develop
The “Adobe is strengthened by AI” scenario will be fully priced in once Adobe proves that, regardless of how AI evolves, its core products remain difficult to replace, and may even improve. Similar to how Google has reinforced the durability of Search even as Gemini advances.
That said, I don’t think this will become clear anytime soon, and the market seems willing to wait as long as necessary for Adobe and GenAI to “show it.”
At this point, it's (already) a show me story by Adobe. Problem is their storytelling of quiet yet consistent growth in the face of evolving AI is being drowned out by one that is making much more noise, the likes of which is very catchy and memorable (no matter how true or false it is). The mere mention of the word AI, and the catchy (yet not always correct) association of AI as a killer of Adobe (and by extension, all software) gives birth to sticky earworms that are difficult to remove from all but the most bullish of ears.
Amidst the very unpleasant noise, someone in the audience of frustrated investors, preferably one that has the fame, reputation, and wealth of a Buffett or Burry, will (eventually) stand up from their seat and shout out their unwavering confidence in Adobe's story. Only then will others follow in short order such that the noise made by detractors will die down to radio silence.
(Of course, should Adobe's stock fall even further this year, it would not be too surprising if a much bigger company like OpenAI or Alphabet makes moves to buy all or parts of Adobe in their efforts to shore up their AI models' capabilities in producing and editing images and videos)