

The legendary investor André Kostolany once perfectly captured the relationship between a company’s fundamental progress and its stock price using a simple metaphor - a human walking their dog.
The human, walking steadily forward, represents the company’s underlying economy and fundamentals - earnings, cash flow, margins, etc. The dog, representing the stock market’s animal spirits and investor sentiment, runs wildly back and forth.
Sometimes the dog darts far ahead in excitement, and other times it lags far behind in fear. While the dog’s movements are erratic and often seem completely disconnected from the humans steady pace, over the arc of time (the walk) the two are ultimately tethered together.

The intersection of financial markets and human psychology frequently produces situations where it appears that the human and the dog decouple. Perhaps the most painful for a long investor is the phenomenon where a corporation consistently reports improving financial metrics - expanding gross margins, surging free cash flow, and accelerating top-line revenue - yet the broader equity market continuously and aggressively discounts the company’s valuation. Adobe, we’re looking at you.
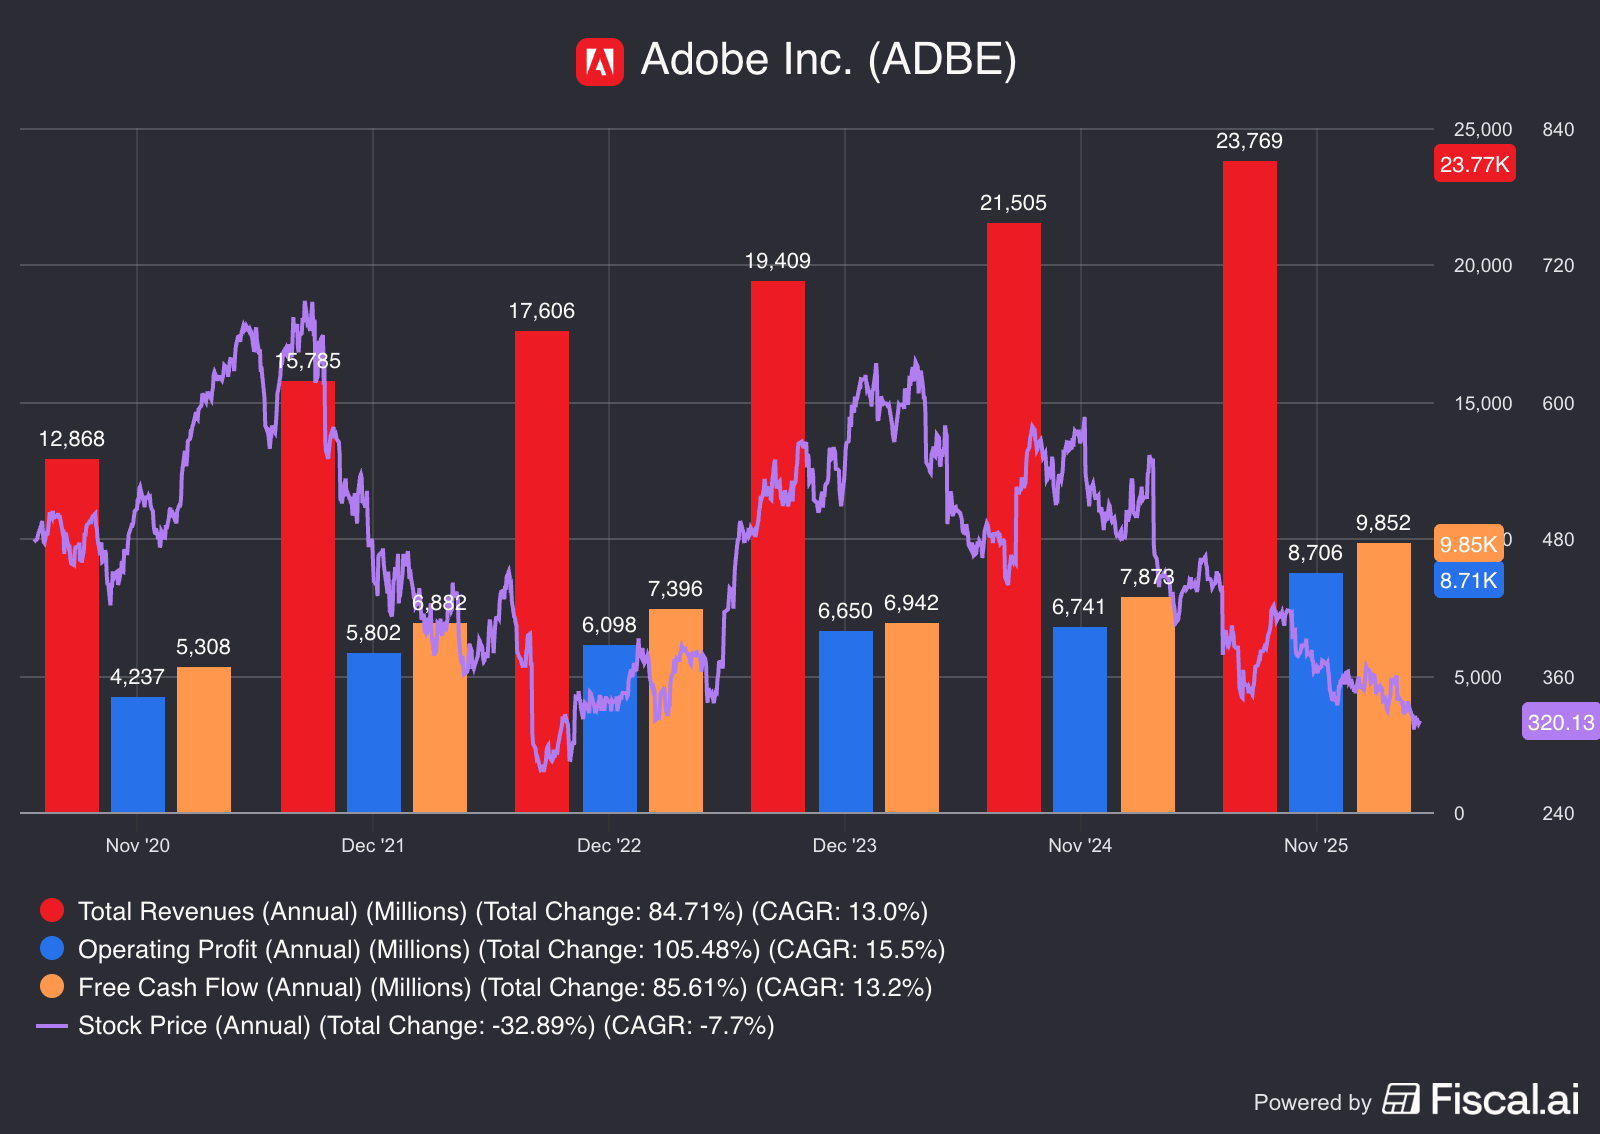
In these situations, the market essentially signals that the current fundamental reality is an illusion, a temporary peak destined for imminent structural decline. The dilemma for the investor is determining whether the market is demonstrating a collective understanding of a deteriorating business model, or if it is merely suffering from an emotional overreaction driven by an extrapolated narrative.
Unless you’re George Soros, relying on intuition, gut feeling, or qualitative judgment to resolve this dissonance is inherently fraught with hazards. A rigorous analytical framework is required to distinguish between the generational opportunity and a value trap.
By mixing the principles of Michael Mauboussin’s “Expectations Investing,” the knowledge of historical base rates, and an understanding of cognitive biases, we can construct a systematic methodology to assess these divergences.
The Inside Versus the Outside View
To understand why the market frequently misprices the threat of disruption, one must first examine the ingredients that are required for a good forecast. When investors attempt to determine if a dominant software company will be destroyed by artificial intelligence, they typically engage in a cognitive process that behavioral economist Daniel Kahneman defines as the inside view. The inside view approaches a forecasting problem by focusing strictly on the specific details of the case at hand, relying on immediate anecdotal evidence, localized data, and vivid narratives.
This method of deduction feels highly intuitive and logically sound to the human brain because it constructs a coherent, linear, and highly salient story. However, as Michael Mauboussin notes in his research on corporate decision-making and market efficiency, the inside view almost invariably leads to inaccurate predictions. Specifically, it is characterized by overconfidence, an illusion of control, and a failure to consider a sufficiently wide distribution of potential outcomes.
For example, a prospective Adobe investor utilizing the inside view may test a new generative AI image tool, note its rapid improvement, combine this observation with a thesis that corporate marketing departments will look to aggressively cut costs, and subsequently project a catastrophic decline in Adobe’s professional subscriber base
The antidote to this cognitive trap is the “outside view.” The outside view entirely ignores the specific narrative details of the individual company and instead treats the forecasting problem as merely one instance within a much larger reference class. It asks a fundamental statistical question: historically, when similar companies faced similar conditions, what was the actual distribution of outcomes? The statistical data derived from this reference class is known as the base rate.
For example, rather than asking “Will large language models destroy Duolingo?”, an investor utilizing the outside view would ask, “What is the historical base rate of an incumbent software platform with a 92% Return on Invested Capital (ROIC), 50 million daily active users, and a deeply entrenched behavioral gamification loop being entirely displaced by a generalized technological substitute within a rapid timeframe?”.
The historical base rate for such total, immediate disruption is exceedingly low. While “disruptive innovation” is a popular theoretical framework championed by Clayton Christensen, empirical data demonstrates that true structural dethronement of dominant, highly profitable incumbents by novel entrants is statistically rare; incumbent survival and adaptation rates are historically much higher than the market narrative assumes during periods of panic.
Neglecting base rates in favor of highly salient, vivid narratives is a documented cognitive error known as the representativeness heuristic or base-rate neglect.
The Base Rate of Market Predictive Accuracy
How proficient is the market at identifying a true structural decline versus merely experiencing a transient panic? To build internal conviction against a collapsing stock price, an investor must understand the base rates regarding the market’s own predictive accuracy.
The academic literature on market efficiency and predictive accuracy presents a highly nuanced picture. On one hand, prediction markets and aggregate equity market mechanisms are incredibly efficient at pricing in known, structured information. Markets typically react to scheduled events, such as earnings announcements or macroeconomic data releases, in milliseconds, efficiently absorbing the numerical reality into the asset’s price. However, when pricing complex, long-term, structural uncertainties - such as the ultimate terminal impact of a new technological shift - the market is highly susceptible to behavioral distortions.
Research demonstrates that investors systematically over-infer from weak signals and under-infer from strong signals. A “weak signal” in this context is a highly publicized, emotionally salient event with low actual diagnostic value regarding long-term cash flows. Examples include the release of a viral video generated by an AI model, a sudden shift in retail trader sentiment, or an analyst downgrade based on peer group momentum rather than fundamental deterioration.
Market participants act as if these weak, noisy signals are highly predictive of the future state of the world, leading to severe overreaction and momentum-driven selloffs. This over extrapolation is deeply rooted in diagnostic expectations, where forecasters overweight the probability of a future state that is highly representative of recent news, ignoring the historical base rate that radical shifts are uncommon.
Conversely, the market chronically underreacts to “strong signals.” Strong signals are less sensational but statistically robust indicators of long-term value, such as sustained high gross margins, consistent free cash flow generation, and aggressive, mathematically accretive share repurchases. This creates a measurable phenomenon where the market extrapolates short-term narrative fears far into the future, assuming an immediate terminal decline, while actively ignoring the high base rate of persistence inherent in cash-generative, high-margin business models.
Studies tracking market sentiment versus actual fundamental outcomes reveal that periods characterized by extreme negative sentiment often fail to materialize into corresponding fundamental collapses. The market’s “hit rate” for correctly predicting immediate industry obsolescence based on early-stage technological shifts is demonstrably poor.
The market consistently underestimates the speed of consumer adoption curves, the friction of enterprise switching costs, and the incumbent’s ability to adapt and counter threats. Therefore, an investor facing a collapsing stock price in the presence of rising earnings should default to the statistical probability - the base rate - that the market is overextrapolating a weak signal, unless specific, existential criteria are met.
When the Market Was Right
However, investors must acknowledge that the market is not always wrong. There are vital historical instances where the market correctly predicted the death of a business model, heavily discounting stock prices well before the underlying earnings formally collapsed. The most instructive case study for this dynamic, and the one most frequently cited by market bears, is the secular decline of the print newspaper industry.
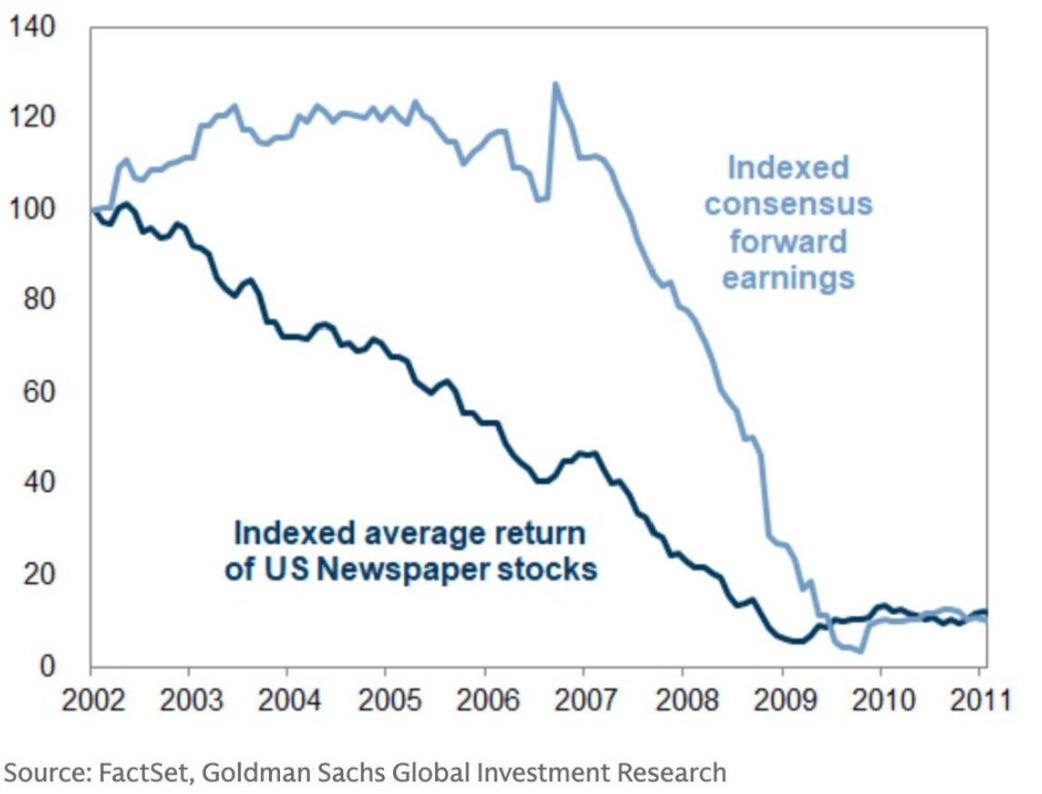
For decades throughout the 20th century, local and national newspapers operated as functional monopolies. They possessed immense pricing power, effectively acting as toll bridges for advertisers seeking to reach local consumers. Their economic moats were incredibly wide, protected by high capital requirements for printing presses and physical distribution networks. During this era, newspaper conglomerates generated massive amounts of free cash flow and maintained high operating margins.
Enter the internet.
Suddenly, there was an alternative frictionless substitute. Platforms like Craigslist entirely decoupled classified advertising - the most lucrative margin driver for newspapers - from the physical production of news. Furthermore, the internet provided an unlimited supply of free, instantly accessible information, permanently altering consumption habits.
The timeline of the newspaper industry’s decay reveals how the stock market processes genuine terminal decline. The peak in newspaper stock valuations occurred significantly earlier than the final collapse in their trailing earnings, demonstrating a clear instance of accurate, long-term market prescience regarding structural obsolescence.
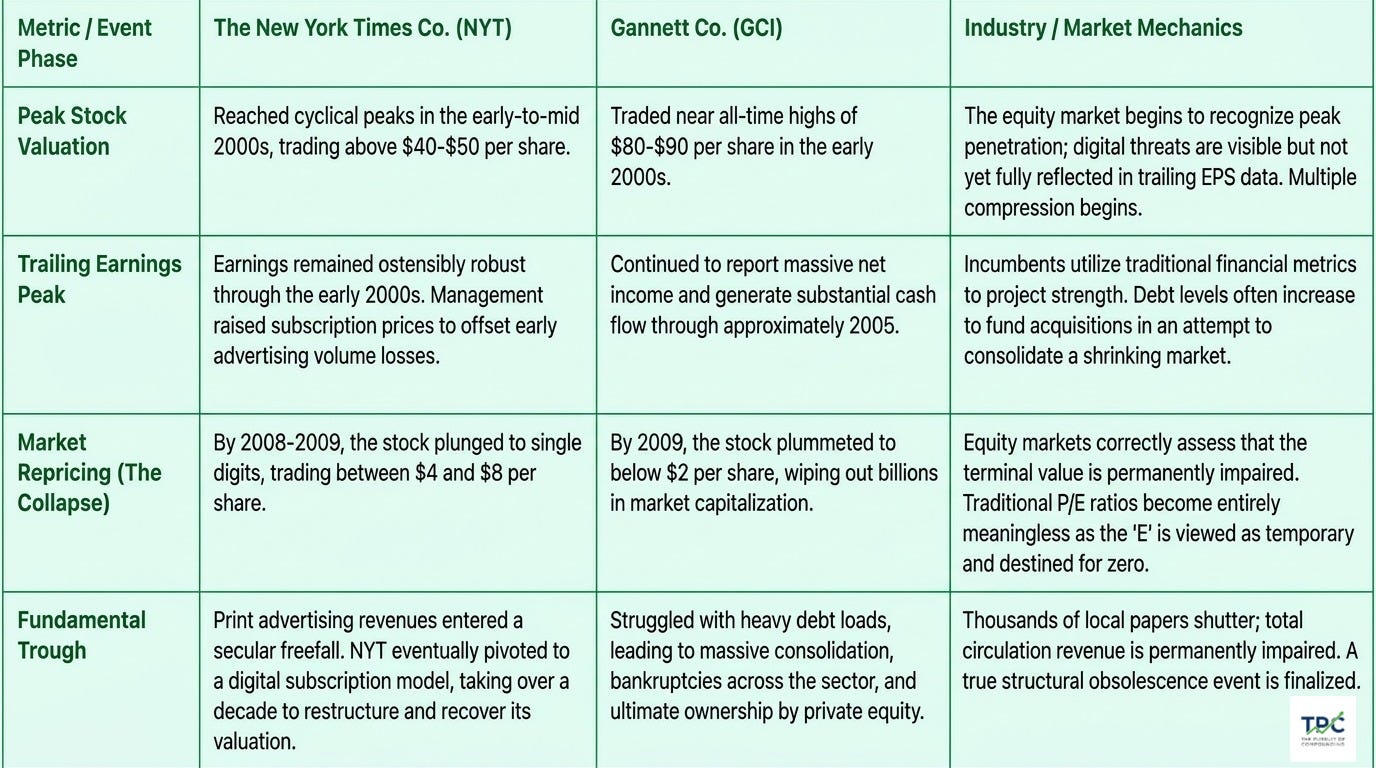
The market was correct because the technological disruption was not merely a new tool that newspapers could integrate into their existing workflow; it was a fundamental decoupling of their monetization engine from their distribution mechanism by entities with a marginal cost of zero.
The competitive advantage period (CAP) was forced to zero. Further, print media no longer monopolized the flow of information. The market correctly ignored the high trailing earnings in 2004–2005 because the base rate of survival for a high-fixed-cost physical distribution business facing a zero-marginal-cost digital substitute is effectively zero. The terminal value was impaired, and the market priced the equity accordingly.
When the Market Was Wrong
Contrasting the newspaper industry’s terminal decline are numerous historical examples where improving fundamentals were met with severe stock price stagnation or collapse, yet the underlying business model remained structurally sound. In these instances, the market confused temporary cyclicality, high initial valuation multiples, or resolvable narrative crises with terminal decline.
The Microsoft “Dead Money” Era (2000–2012)
Following the Dot-Com bubble, Microsoft (MSFT) entered a prolonged period commonly referred to as “dead money.” For over a decade, Microsoft’s stock price remained essentially flat.
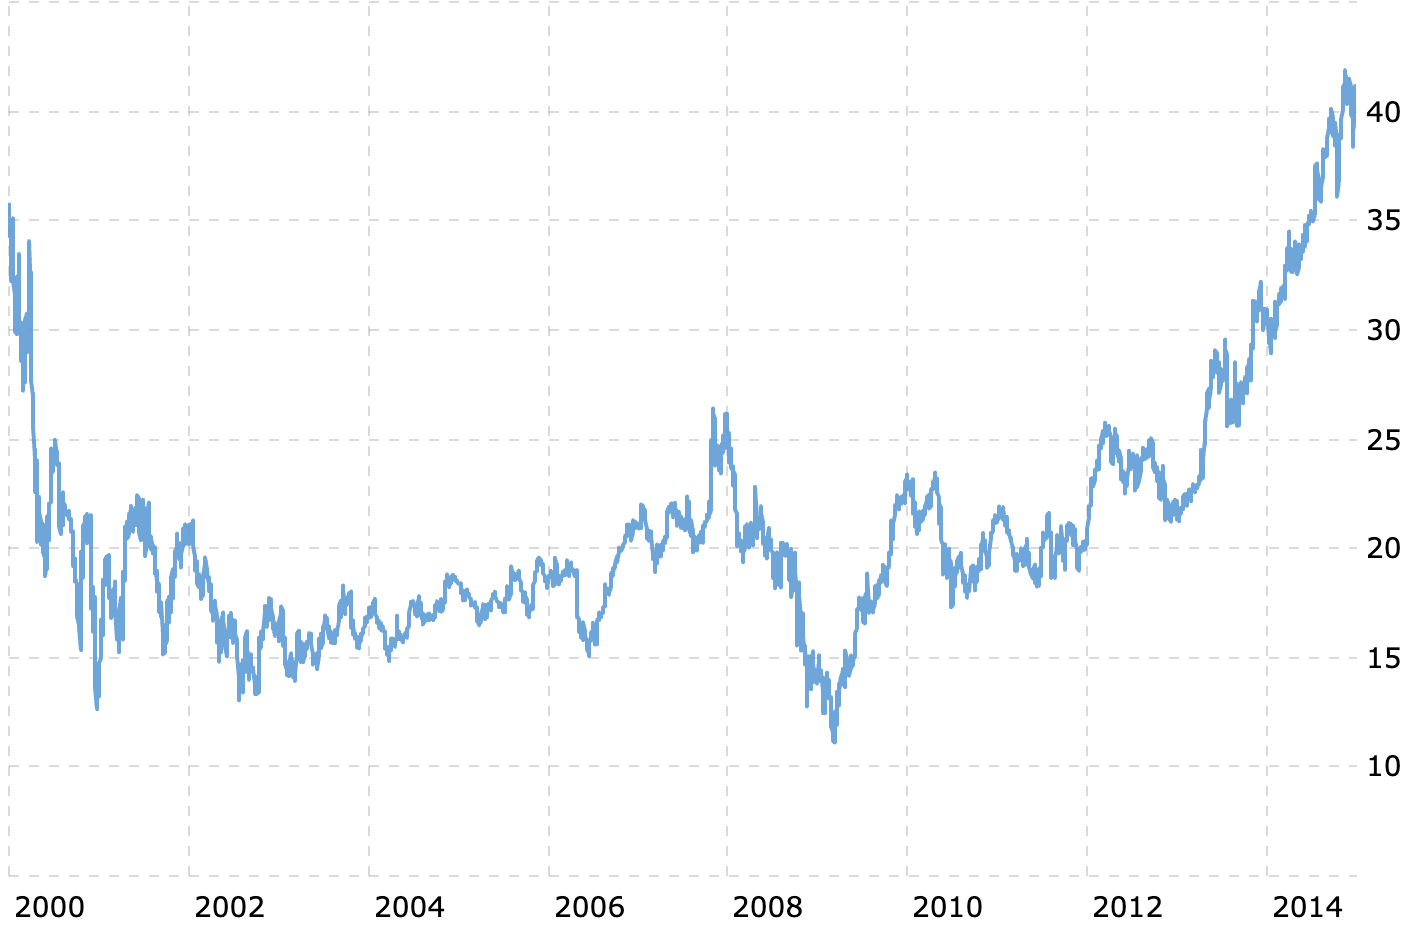
During this exact same period, the company’s fundamentals were exceptional. Net income crossed the $10 billion mark for the first time in fiscal 2005, jumping 50% year-over-year to $12.3 billion. Revenues and earnings per share continued to march steadily upward.
The market soured on Microsoft not because the business was failing, but because the starting expectations (the valuation multiple) in 1999 were mathematically impossible to satisfy. Further, a pervasive narrative took hold that Microsoft had missed the mobile and search revolutions. The market assumed the rise of Apple and Google would render Microsoft’s enterprise software dominance obsolete.
In hindsight, it’s easy to see that the market was profoundly wrong.
The switching costs and the stickiness of the Windows and Office ecosystems provided a massive margin of safety. These franchises provided ample cash flow that funded the development and scaling of Microsoft’s cloud platform, Azure. Once the market recognized that the terminal value was not impaired, patient investors were awarded with a hundred bagger.
If an investor bought on January 1, 2000 and held to January 1, 2026 they would have achieved a ~10% CAGR (including dividends), beating the S&P during the same time by 150-200 basis points.
The Netflix Qwikster Crisis (2011)
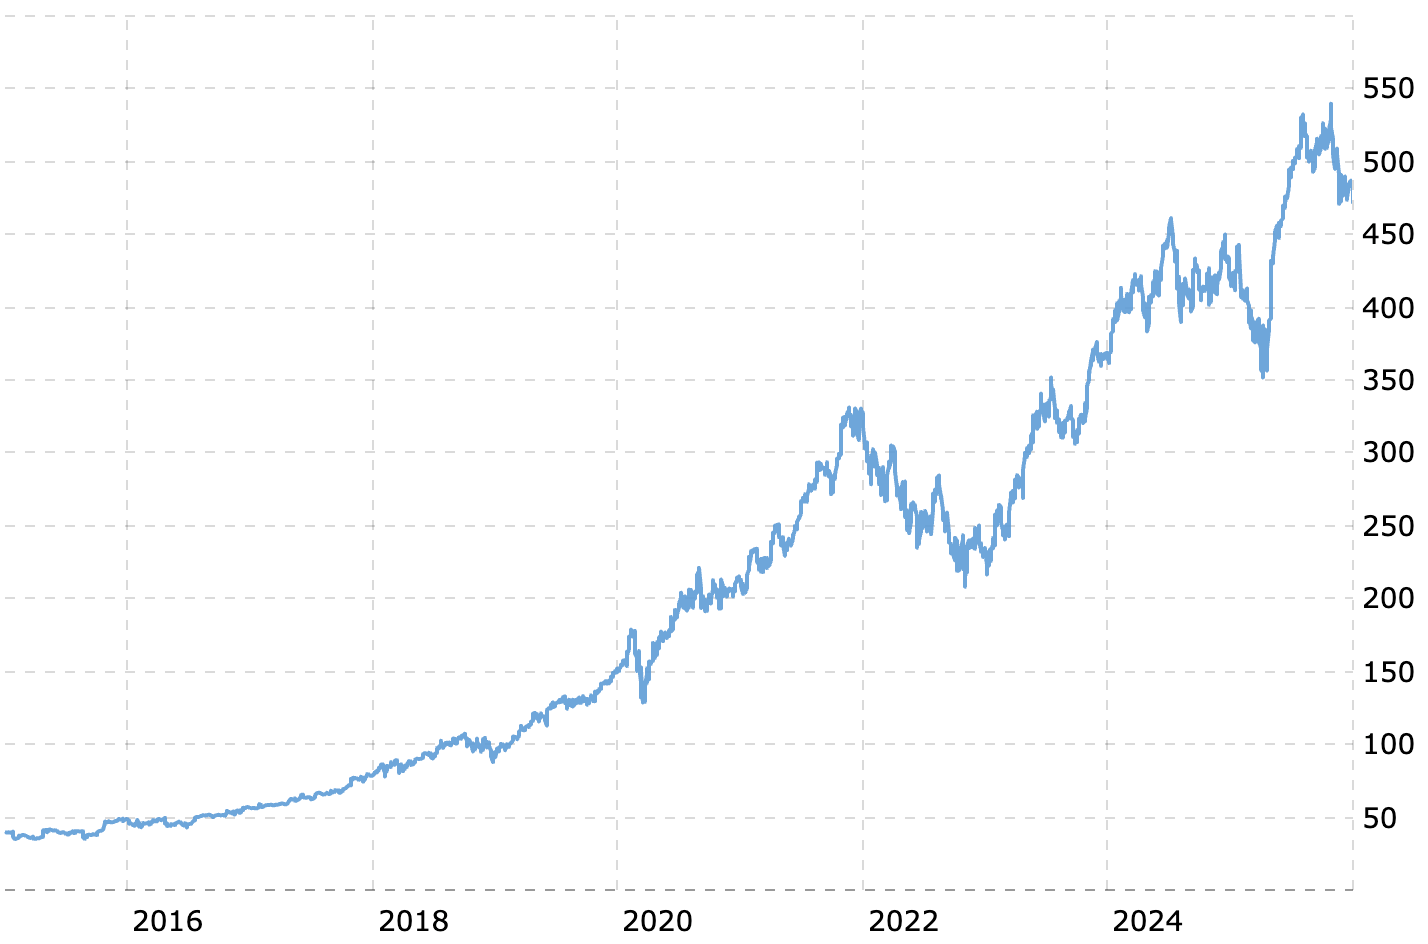
A more acute example of market overreaction occurred with Netflix (NFLX) in 2011. As the company attempted to transition its customer base from physical DVD rentals to digital streaming, management announced a price increase and a deeply unpopular plan to split the services, branding the DVD business “Qwikster”.
The market reaction was violently negative. Driven by fierce consumer backlash and a narrative that Netflix had permanently alienated its user base, the stock collapsed by 75%, dropping from $42 in July 2011 to under $9 by the end of the year.
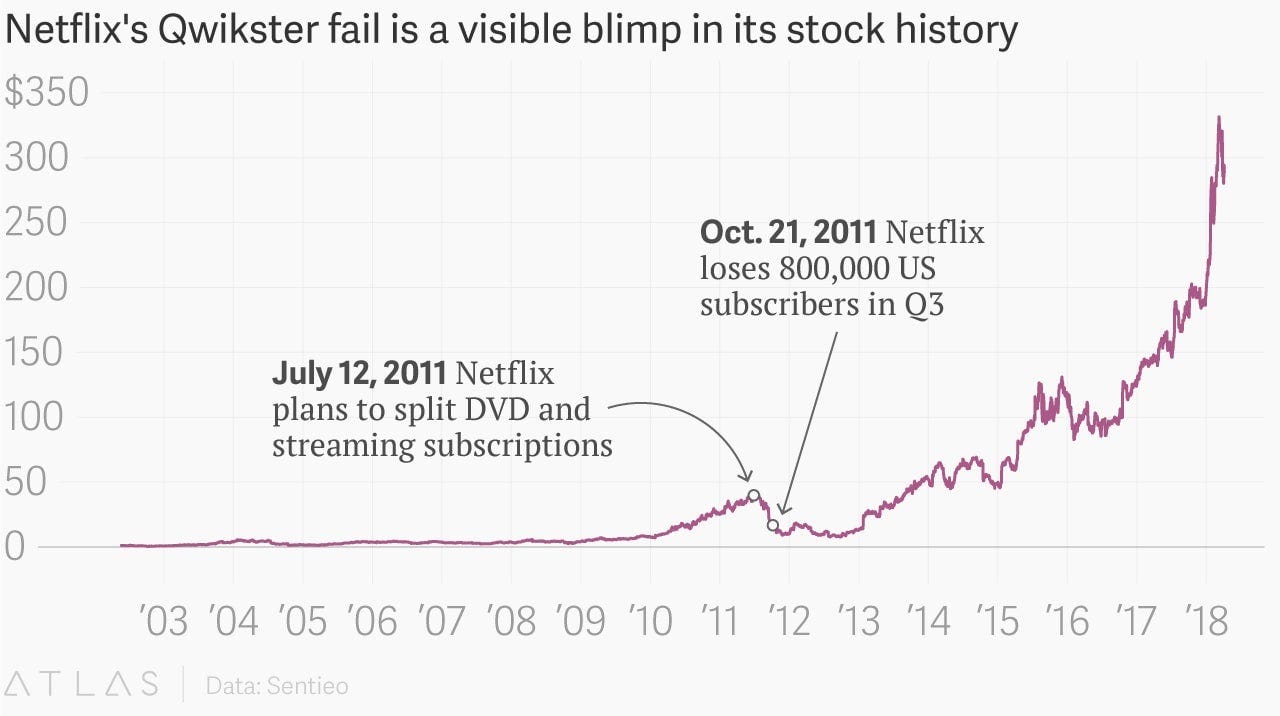
In that same year, churn in the business unexpected increased, further hurting the narrative. The market priced the equity as if the subscriber churn was permanent and the streaming business model was structurally flawed.
However, the underlying fundamental premise - that consumers desired on-demand digital content - remained completely intact. Investors who ignored the highly salient, emotional narrative of the Qwikster public relations disaster and focused on the base rate of digital adoption realized spectacular returns as the company recovered and dominated the streaming landscape.
These case studies highlight a critical vulnerability in aggregate market pricing: the market struggles immensely to differentiate between a temporary headwind (or multiple reset) and a terminal decline, often pricing both scenarios with equal severity in the short term.
Contemporary Divergences: The AI and Saturation Narratives
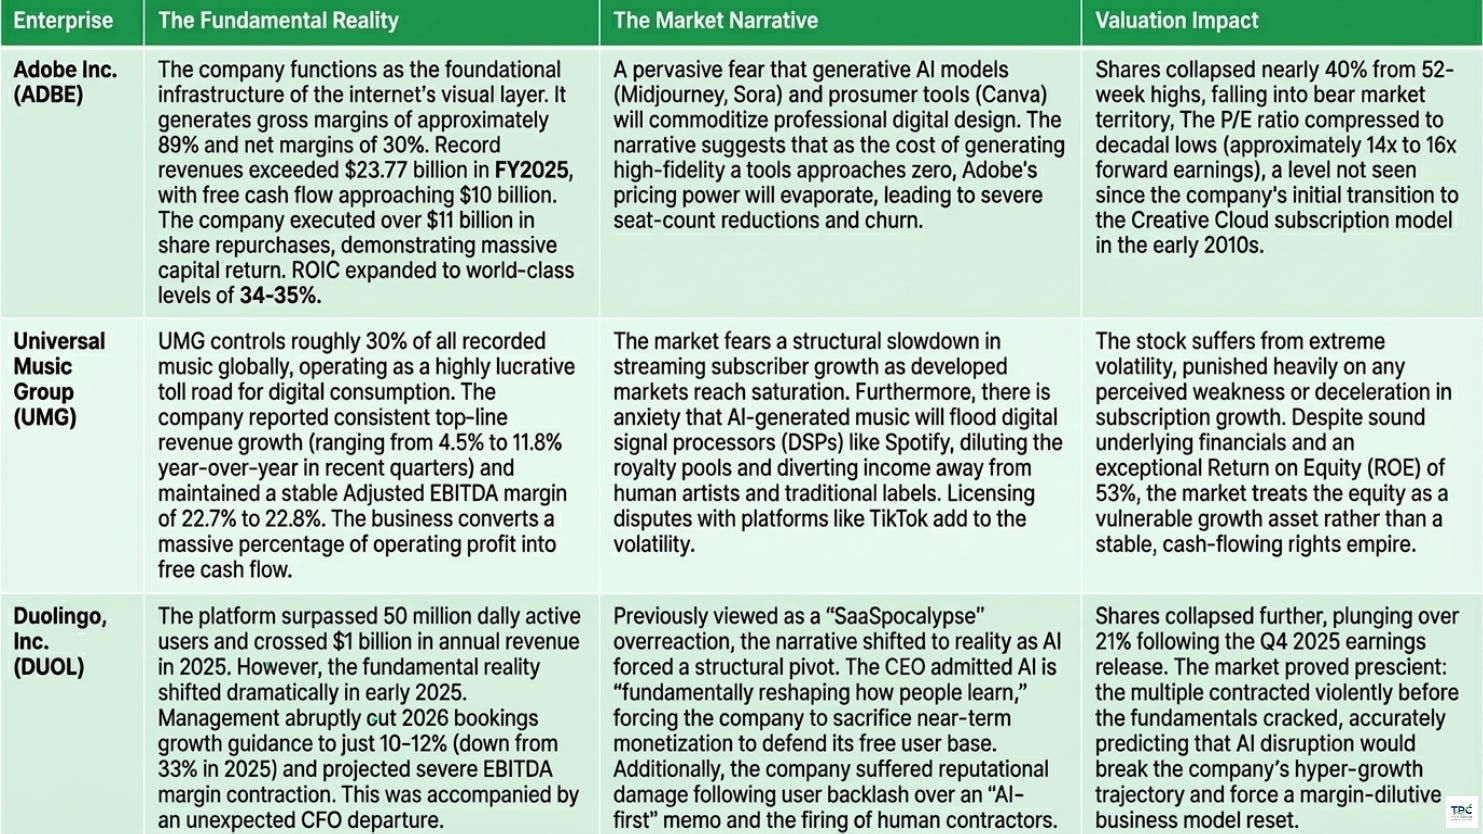
Applying this historical context to the current market environment highlights the mechanics driving the divergence in companies like Adobe (ADBE), Universal Music Group (UMG), and Duolingo. In these instances, robust trailing financial realities collide with powerful, fear-driven narratives. However, as recent developments demonstrate, the market can sometimes accurately front run a fundamental deterioration before the trailing data reflects it.
In the cases of Adobe and UMG, the market is aggressively discounting the terminal value of the enterprise due to fear. With Duolingo though the market may be right. As the company’s 2026 guidance confirmed, the high margins and hyper-growth rates were indeed unsustainable and rapidly regressed.
The “Expectations Investing” Paradigm
When an investor possesses implicit conviction about a company’s financial trajectory and is plagued by the psychological pressure of a collapsing stock price, they must transition to an expectations-based analysis. The premier methodology for this transition is “Expectations Investing,” a framework developed by Alfred Rappaport and Michael Mauboussin. It’s something we plan to unpack in our next Consilient Investor article.


In short, expectations investing acknowledges that the only absolute, objective truth in the financial markets is the current stock price. Instead of attempting the impossible task of forecasting the future, the investor can use a reverse Discounted Cash Flow (DCF). While a traditional DCF attempts to predict future cash flows to estimate a fair price, a reverse DCF starts with today's known stock price and works backward to reveal the exact growth and margin assumptions already baked in. This process calculates the Price-Implied Expectations (PIE).
Once the PIE is established, the investor’s sole task is to assess the probability that the company will exceed or fall short of those specific, defined expectations. By understanding exactly how the market is currently weighing the fundamental variables to justify the current share price, the investor removes emotion and narrative from the equation, replacing it instead with a testable hypothesis.
A Systematic Framework for the Long-Only Investor
Ok, so what?
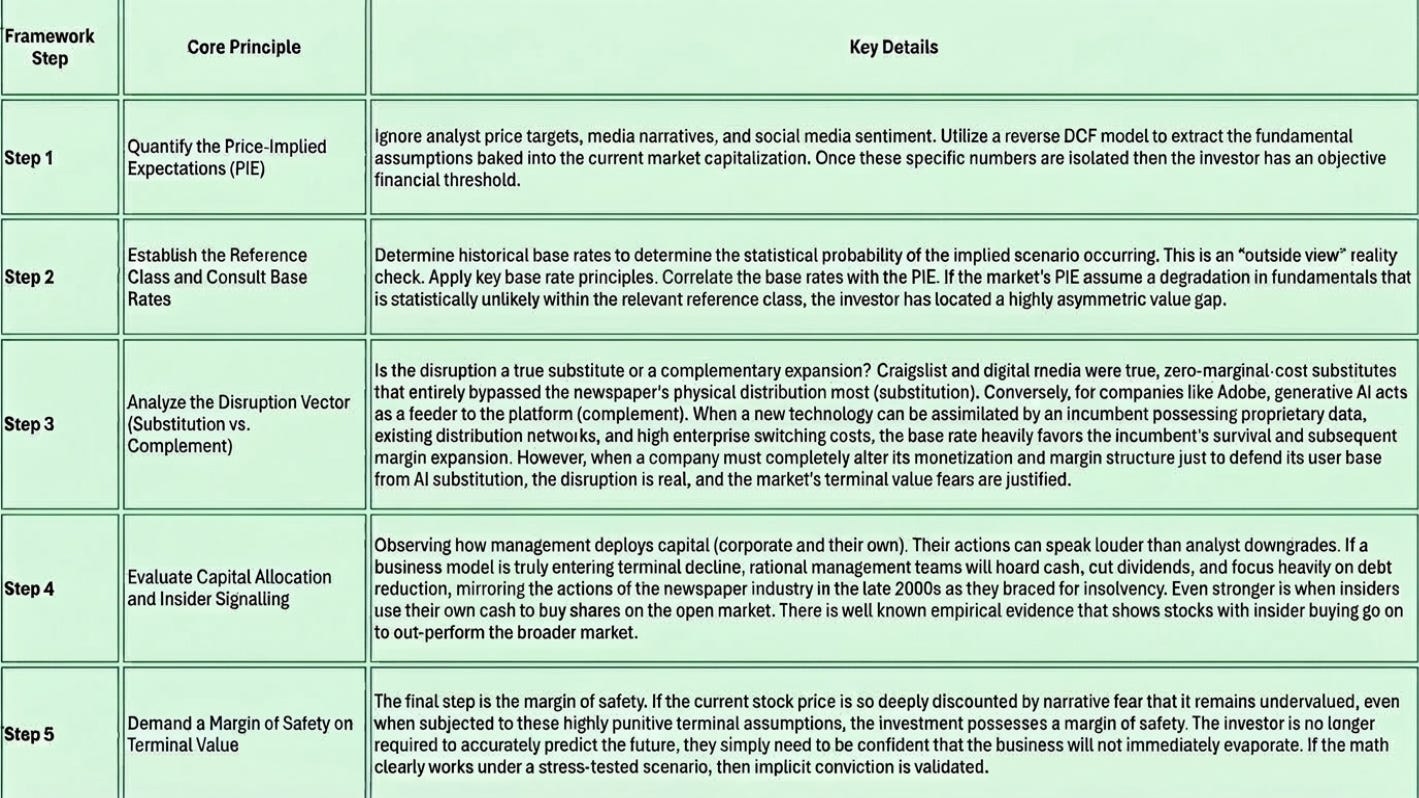
We can tie all these ideas into a five-step framework when confronting a divergence between improving fundamentals and a collapsing stock price. The goal is to move the investor away from feel and toward deduction.
Step 1: Quantify the Price-Implied Expectations (PIE)
The immediate first action is to utilize a reverse DCF model to extract the exact fundamental assumptions baked into the current market capitalization.
If Adobe’s stock falls by 40% while its free cash flow continues to grow, the market is severely compressing the implied duration and magnitude of its value creation. The reverse DCF will reveal exactly what the market expects. For example, calculating the PIE might reveal that the current depressed price mathematically implies Adobe’s revenue growth will immediately drop to zero and its operating profit margins will contract from 30% to 15% over the next three years.
Once these specific numbers are isolated, the amorphous fear of “AI disruption” is then encapsulated into a tangible, testable financial threshold. The investor no longer asks, “Will AI hurt Adobe?”; they ask, “What financial metrics is the market pricing currently pricing in?”.
Step 2: Establish the Reference Class and Consult Base Rates
With the PIE explicitly quantified, the investor can then consult historical base rates to determine the statistical probability of that implied scenario occurring. Mauboussin’s Base Rate Book provides longitudinal data on corporate performance, serving as the ultimate “outside view” reality check.
Key base rate principles to apply include:
Gross Margin Persistence: High gross margins are one of the most persistent factors of long-term corporate performance. Once a company establishes a high gross margin, it tends to retain it, creating a floor for profitability. If a company like Adobe possesses ~89% gross margins, the base rate suggests extreme resilience against rapid profitability degradation, even in highly competitive environments. The market’s expectation of an immediate margin collapse is statistically anomalous.
CFROI Fade Rates: High Cash Flow Return on Investment (CFROI) naturally fades toward the cost of capital over time due to the gravitational pull of competition. However, the market frequently prices in a fade rate that is far too aggressive for companies with deeply entrenched network effects or high switching costs. If the PIE implies a CFROI fade rate that is substantially faster than the historical base rate for similar software monopolies, then the stock is mispriced.
If the market’s PIE assume a degradation in fundamentals that improbable within the relevant reference class, then the investor has located a highly asymmetric value gap.
Step 3: Analyze the Disruption Vector (Substitution vs. Complement)
The critical difference between the newspaper industry (where the market was right) and contemporary software platforms lies in the structural nature of the technological threat. The framework requires classifying the disruption as either a true substitute or a complementary expansion.
The Substitute (The Newspaper Scenario): Craigslist and digital media were true, zero-marginal-cost substitutes that entirely bypassed the newspaper’s physical distribution moat. The incumbent could not co-opt the technology to protect its core revenue driver. Their economic model was permanently broken.
The Complement (The Modern SaaS Scenario): Conversely, for companies like Adobe, generative AI acts as a feeder into their platform. Adobe integrates AI (Firefly) directly into its professional workflow, enhancing the value of its proprietary ecosystem and maintaining its status as the standard for enterprise content production. While AI can generate an image, that asset still requires the Adobe ecosystem for corporate color grading, typography, layout, etc.
When a new technology can be assimilated by an incumbent possessing proprietary data, existing distribution networks, and high enterprise switching costs, the base rate favors the incumbent’s survival and even margin expansion.
However, when a company must completely alter its monetization and margin structure just to defend its user base from AI substitution, the disruption is real, and the market’s terminal value fears are justified.

Step 4: Evaluate Capital Allocation and Insider Signalling
When market sentiment diverges sharply from intrinsic value, observing how management deploys capital can provide a reality check against the outside noise. Their actions with corporate - or their own - cash speak louder than analyst downgrades.
If a business model is truly entering terminal decline, rational management teams will hoard cash, cut dividends, and focus heavily on debt reduction, mirroring the actions of the newspaper industry in the late 2000s as they braced for insolvency. However, if management aggressively repurchases shares, this can signal profound internal conviction that the market’s terminal value assessment is fundamentally flawed.
For instance, Adobe’s strategy of executing massive, multi-billion-dollar buyback programs - effectively cannibalizing its own float at depressed multiples - demonstrates that the cash flow generation remains structurally sound despite external AI anxiety. Buying back stock at a 15x P/E ratio when margins are expanding is a highly accretive maneuver that mathematically increases intrinsic value per share.
Even stronger is when insiders use their own cash to buy shares on the open market. There is well known empirical evidence that shows stocks with insider buying go on to out-perform the broader market.
Step 5: Demand a Margin of Safety on Terminal Value
The final step in the framework is the application of the ultimate risk management tool: the margin of safety. In discounted cash flow models, the terminal value - the estimated value of all cash flows beyond the explicit forecast period - often accounts for the vast majority (sometimes over 80%) of the company’s calculated intrinsic value. The market’s fears of disruption are almost entirely focused on compressing this terminal value.
If the current stock price is so deeply discounted by narrative fear that the PIE are at the floor, then even when subjected to these highly punitive terminal assumptions, the investment possesses a margin of safety. The investor is no longer required to accurately predict the future or feel that they need to have a strong view on possible catalysts or outcomes; instead, they simply need to be confident that the business will not immediately evaporate. If the math clearly works under a stress-tested scenario, then implicit conviction is validated.
I don't look to jump over 7-foot bars: I look around for 1-foot bars that I can step over. - Warren Buffett
The Bottom Line
The burden of maintaining implicit conviction while share prices continue to drop is immense. The human brain is evolutionarily wired to conform to the herd, making that little voice of doubt inevitable. However, by recognizing that market sentiment frequently overreacts to weak narratives, while ignoring the strong signals of persistent cash flow, an investor can (somewhat) detach from this emotional turbulence.
Nonetheless, sometimes price declines are prescient. The market correctly identified the structural death of the newspaper industry because the economic moat was fundamentally bypassed by a zero-cost substitute, permanently impairing the terminal value.
Similarly, when AI forces a company like Duolingo into a sudden, margin-diluting structural pivot, the market’s early punishment is validated. In contrast, modern digital platforms like Adobe exhibiting exceptionally high ROIC, sticky enterprise workflows, and the capacity to assimilate new technologies as complementary features are structurally different.
Ultimately, the market will always have its animal spirits. The dog will inevitably dart far ahead (or behind) the human. Speculative euphoria and narrative-driven panics will always exist.
By utilizing the Expectations Investing framework to reverse-engineer exactly what the market is pricing in, and cross-referencing those implied expectations against historical base rates, the investor can replace feel with deduction. When the market prices a highly profitable, cash-generative incumbent as if it is entering terminal decline, and historical base rates instead suggest a high probability of survival and adaptation, then this divergence is a source of opportunity.
As long as the human keeps walking steadily forward, the patient investor can comfortably enjoy the stroll, knowing that the pursuit of compounding is then simply a matter of time.
Disclaimer: We are private investors and not financial advisors. This post is for educational purposes only and does not constitute financial advice. Always conduct your own due diligence before making any investment decisions.