

Hello and welcome to the fourth issue of The Consilient Investor. This is our magnum opus for 2026 where we plan on releasing one issue per month. At the conclusion they will be incorporated into an E-Book that will be released for paid subscribers.
If you missed the first three, catch up here:


Subscribe today so you don’t miss out on future issues!
In The Consilient Investor (TCI) 03 we opened with a provocation:
Every time an investor builds a traditional 10-year Discounted Cash Flow (DCF) model, they are participating in an illusion.
We argued that forward-forecasting - i.e. guessing cash flows many years into the future - suffers from an abysmal signal-to-noise ratio and isn’t worth doing. We explored how the Price-Implied Expectations (PIE) and Expectations Investing framework flips the model upside down, transforming the investor from a forecaster into an auditor.
And so, building on that theme, today we’ll be deep diving into Discounted Cash Flow (DCF) Models.
Wait, what?
Why would we spend several thousand words defending the very thing we lambasted last issue? Because illusion or not, they are a useful tool in investing.
The PIE framework tells the investor what the market believes. However, to decide whether the market is right, wrong, or somewhere in between, the investor needs to compare that to a forward model built with sound logic.
We’ll be delving into what that means further today. Paid subscribers will have access to the three-stage DCF model, PIE reverse DCF model, and an error checklist at the end of the article.
To be clear, these two approaches are not a contradiction; they exist in a duality, like two sides of a coin. If the investor wants to be consilient, then they must hold both frameworks together at the same time.
Mental Model: Wave-Particle Duality
In quantum physics, light behaves as both a wave and a particle. Some phenomena can only be fully described by two frameworks that appear to contradict each other.
The experiment that is run determines which aspect is observed. Run the forward model and you see the intrinsic value. Run the reverse model and you see the market’s embedded expectations. Neither is complete without the other.
Paid subscribers will have access to the three-stage DCF model, the PIE reverse DCF model, and an error checklist at the end of the article.
Cargo Cult Science
In his 1974 Caltech commencement address, the physicist Richard Feynman described a peculiar phenomenon he called “Cargo Cult Science.”
During World War II, Pacific islanders observed Allied military planes landing on their islands to deliver cargo.
After the war ended and the planes stopped coming, some islanders constructed replica runways, wooden control towers, bamboo antennae, and coconut-shell headphones, hoping the ritual would summon the cargo again.
“But it didn’t work.
No airplanes land.
So I call these things Cargo Cult Science, because they follow all the apparent precepts and forms of scientific investigation, but they’re missing something essential, because the planes don’t land.” - Richard P. Feynman, Caltech’s 1974 commencement address.
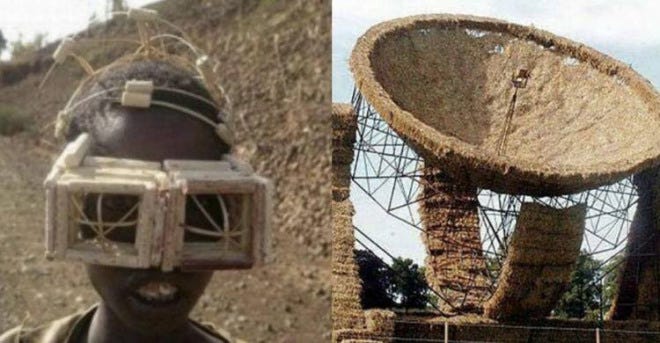
It’s easy to sit and snicker at the unsophisticated tribal peoples. However, Wall Street’s relationship with the DCF model is very similar.
The structure always looks rigorous; explicit forecast periods, terminal values, weighted average cost of capital calculations. But beneath the professional veneer, most institutional DCF models are cargo cult artifacts, like the thatch satellite dish above - they replicate the form of fundamental analysis without the embodiment of substance.
How can this be the case? In Valuation Multiples, (2024) Mauboussin writes:
“Researchers collected responses from nearly 2,000 analysts who were members of the CFA Institute, a global association of investment professionals. Asked about their approach to valuation, nearly 93% selected ‘a market multiples approach’.”
When analysts do build DCF models, they frequently use a multiple (e.g. EV / EBITDA) to calculate the terminal value - meaning 70% to 80% of the model’s output is just a multiple in disguise.
So, what’s wrong with using multiples in a DCF? Haven’t we used them here in the past on this Substack? It’s true, we have! And, like you, we’re learning in real time too!
The core issue is that multiples are not valuation, they are pricing. And that issue isn’t just semantic, it is foundational.
The process of valuation makes an absolute claim: this business will generate X dollars of cash flow over its lifetime, and discounted back to today, those cash flows are worth Y today.
Meanwhile, the process of price makes a relative claim: this business is worth Y today because it trades at this ratio, which I then judge relative to its peers.
When we build a DCF but use a multiple to calculate the terminal value, the terminal value can represent up to 80% of the enterprise value.
If up to 80% boils down to a multiple, then all we’ve done is built a multiples-based valuation wearing a DCF costume. Said another way, we are just doing more elaborate relative pricing, not a valuation.
Everything is a DCF Model
“…we want to suggest the mantra “everything is a DCF model.” The point is that whenever investors value a stake in a cash-generating asset, they should recognize that they are using a discounted cash flow (DCF) model.
…many practitioners use heuristics for value without recognizing the purpose and limitations of the shorthands.
At the end of the day, the intrinsic value, determined by the present value of future cash flows, attracts the price like a magnetic force. This means that investors always have to keep in mind the value drivers of a discounted cash flow model. It is easy to forget but useful to remember.” - Mauboussin and Callahan, Everything is a DCF Model: A Mantra for Valuing Cash Generating Assets (2021)
Warren Buffett has pointed out that the conceptual roots of the DCF analysis stretch back to Aesop, who shared this evergreen valuation philosophy in The Hawk and the Nightingale.
A Hawk catches a Nightingale, and as the smaller bird pleads for its life, it suggests the Hawk could let it go and hunt larger prey that will make for a more satisfying meal.
The Hawk replies:
“I should indeed have lost my senses if I should let go food ready to my hand, for the sake of pursuing birds which are not yet even within sight.”
Said another way: “A bird in the hand is worth two in the bush”.
To apply Aesop’s fable, an investor must answer three questions:
What is the certainty that there are birds in the bush?
When will they emerge, and in what quantity?
What is the risk-free interest rate for discounting those future arrivals back to the present?
This was broken down mathematically in 1938 by John Burr Williams in The Theory of Investment Value. The intrinsic value of any cash-generating asset - that corner laundromat or the multinational conglomerate - is the present value of the future cash flows it will distribute to its owners.
This principle is inescapable, and it applies whether acknowledged or not. When an investor slaps a P/E multiple on a stock, they are implicitly running a DCF model.
The investor who declares “Company A at 15x is cheap relative to Company B at 25x” without examining the respective ROIC trajectories, capital structures, and competitive advantages is engaging in precisely the kind of cargo cult thinking Feynman warned against.
The investor who says, “I use multiples, not DCFs” is like a driver who says “I use the accelerator, not the engine.”
For a multiple to be meaningful, it must map back to the underlying DCF parameters.
Two Architects, One Blueprint: Mauboussin vs. Damodaran
Both Michael Mauboussin and Aswath Damodaran converge on the same foundational truth - intrinsic value is the present value of future cash flows. However, they do view this truth from different perspectives.
As we explored in TCI03, Mauboussin’s expectations framework prefers to invert the problem and examine what makes up the current share price, while also examining the Market Implied Forecast Period (MIFP).
On the other hand, Damodaran is a classic bottom-up valuation architect. He constructs a story and models the future. He estimates revenues, projects margins, forecasts reinvestment, assesses risk, and discounts to present value.
Mauboussin and Damodaran have complementary approaches; Mauboussin is the microscope while Damodaran is the telescope.
Mauboussin’s reverse DCF employs intellectual humility in determining what the market is already pricing. He advocates for decoding the market’s embedded narrative and assessing it against empirical base rates. His rationale is that the signal-to-noise ratio is higher when you audit expectations than when you generate them.
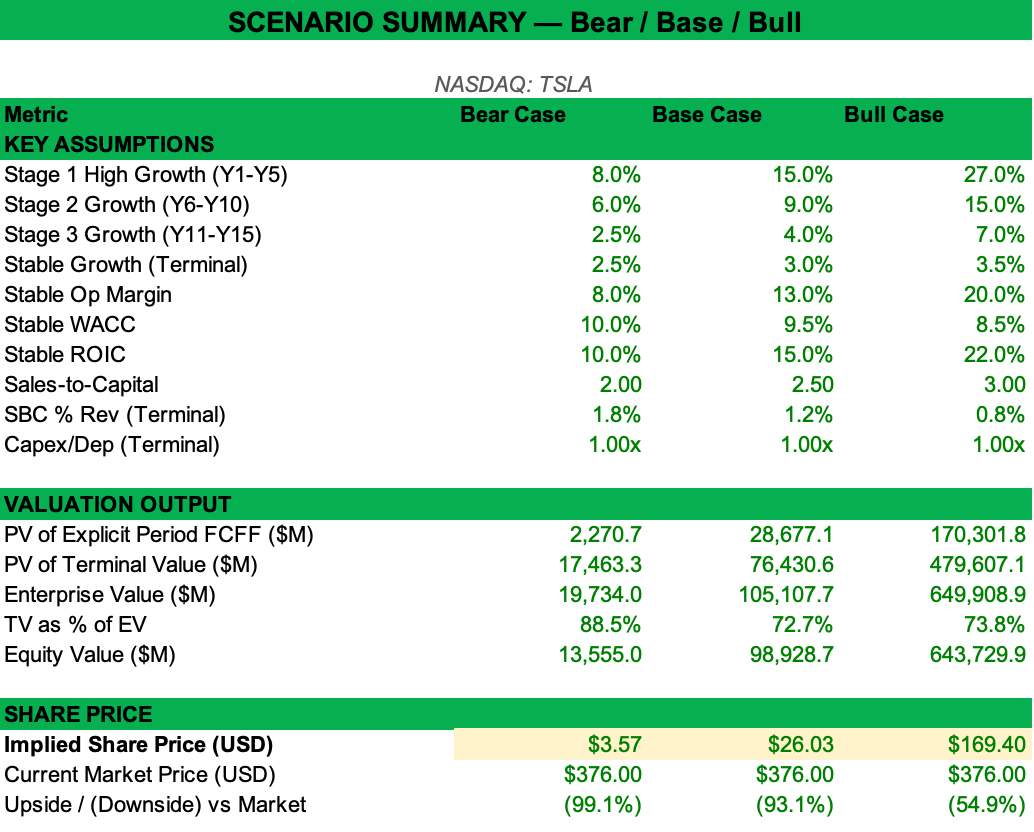
On the other hand, Damodaran’s forward DCF employs intellectual assertiveness in prognosticating the future. He employs a three-stage DCF: a high-growth phase, a transition phase where growth and returns gradually decay, and a stable-growth terminal phase. The goal with this process is to explicitly model the competitive fade that most two-stage models ignore.
Paid subscribers will have access to the three-stage DCF model, the PIE reverse DCF model, and an error checklist at the end of the article.
Further, Damodaran insists that valuation requires a narrative - a coherent story about the company’s future that translates into numbers. Every input must have a narrative justification.
“A good valuation is a marriage between stories and numbers.” - Aswath Damodaran
On the errors that plague the industry, there is near-complete alignment. Both reject terminal growth rates above GDP. Both insist on linking growth to investment. Both condemn the standard SBC treatment. Both argue that multiples are compressed DCFs and must be earned, not assumed.
To fully understand the art of valuation, the consilient investor uses both.
A Taxonomy of Errors
Both architects, despite their different starting points, agree on the specific errors that destroy DCF models in practice.
Because the output is sensitive to small deviations in terminal assumptions, forecast duration, and capital intensity, errors do not merely produce minor inaccuracies - they produce substantial distortions.
Mauboussin has defined a list of the most pervasive errors that routinely render institutional DCF models useless or dangerous. Let’s examine them.
Error 1: The Forecast Horizon Mismatch
Mauboussin highlights this as a structural flaw. Analysts (historically us included!) constrain their explicit forecast periods to five years or fewer, typically justifying this truncation with the reasonable-sounding claim that forecasting beyond a few years is guesswork.
The logic is wrong for a precise reason: the current market prices of most publicly traded equities - particularly those trading at high multiples - reflect expectations for value-creating cash flows extending ten, fifteen, or twenty years into the future. When an analyst assesses a firm with a 20-year competitive advantage period but forces its financials into a 5-year forecast, the model faces a severe mathematical crisis.
For example, in our Hermès Q1 2026 update we ran a Price-Implied Expectations update for Hermès. The market implied forecast period (MIFP) came out at 24 years. This means the market is pricing in a 20+ year competitive advantage. A 5-year DCF for Hermès then compresses the remaining 15+ years of competitive advantage into the terminal value, negating the value of the explicit forecast period.
Mauboussin’s prescription is that the explicit forecast period should be elongated to capture the entirety of the firm’s excess-return phase - often ten to fifteen years. The investor then has to model the gradual fade of the ROIC toward the cost of capital as the competitive advantage period exhausts itself. This aligns with the three-stage DCF model philosophy espoused by Aswath Damodaran.
Then, the terminal value accurately reflects a mature state of value neutrality, and the model’s dangerous sensitivity to infinite terminal assumptions is drastically reduced.
Think of it like a controlled landing on an aircraft carrier. A 5-year forecast for a company with a 20-year runway is like cutting the approach short and hoping the plane finds the deck on its own.
Error 2: The Investment-Growth Disconnect
Companies must invest capital to generate sustainable organic growth. Whether through capex, working capital expansion, R&D, or acquisitions, growth is a function of capital reinvestment. Value creation then is based on the returns of that growth.
Yet DCF models routinely project aggressive revenue and margin growth in perpetuity without forecasting a commensurate increase in the capital required to sustain it. This effectively models a scenario where the company manufactures money from thin air.
During high-growth phases, capex must materially exceed depreciation because the company is expanding its asset base. As growth decelerates toward a terminal rate, the composition of capex must shift from growth-oriented to maintenance-oriented. In the final forecast year, assuming the firm has reached a stable, low-growth steady state, the ratio of capex to depreciation must converge toward 1.0, or slightly above to support inflation and modest growth.
If the model assumes depreciation will outpace capex indefinitely, then there is a massive artificial inflation of terminal free cash flow. Said another way, a company cannot grow at 3-4% in perpetuity while undertaking zero net capital investment.
Error 3: Terminal Value Inflation
Analysts can justify elevated stock prices by assigning perpetual terminal growth rates of 5%, 6%, or even higher. This ignores the macroeconomic speed limits of capitalism.
In perpetuity, no single corporate entity can outgrow the broader economy. Yes, some companies do indeed have sustained competitive advantages, but no company can grow larger than the global economy in perpetuity. The perpetual growth assumption must be capped at the risk-free rate or the long-term expected growth rate of nominal GDP - historically bounded between 2% and 4%.
Furthermore, the terminal value must account for the microeconomic reality of mean reversion. Over long durations, excess returns attract competition, which erodes advantages and forces ROIC down closer to the WACC.
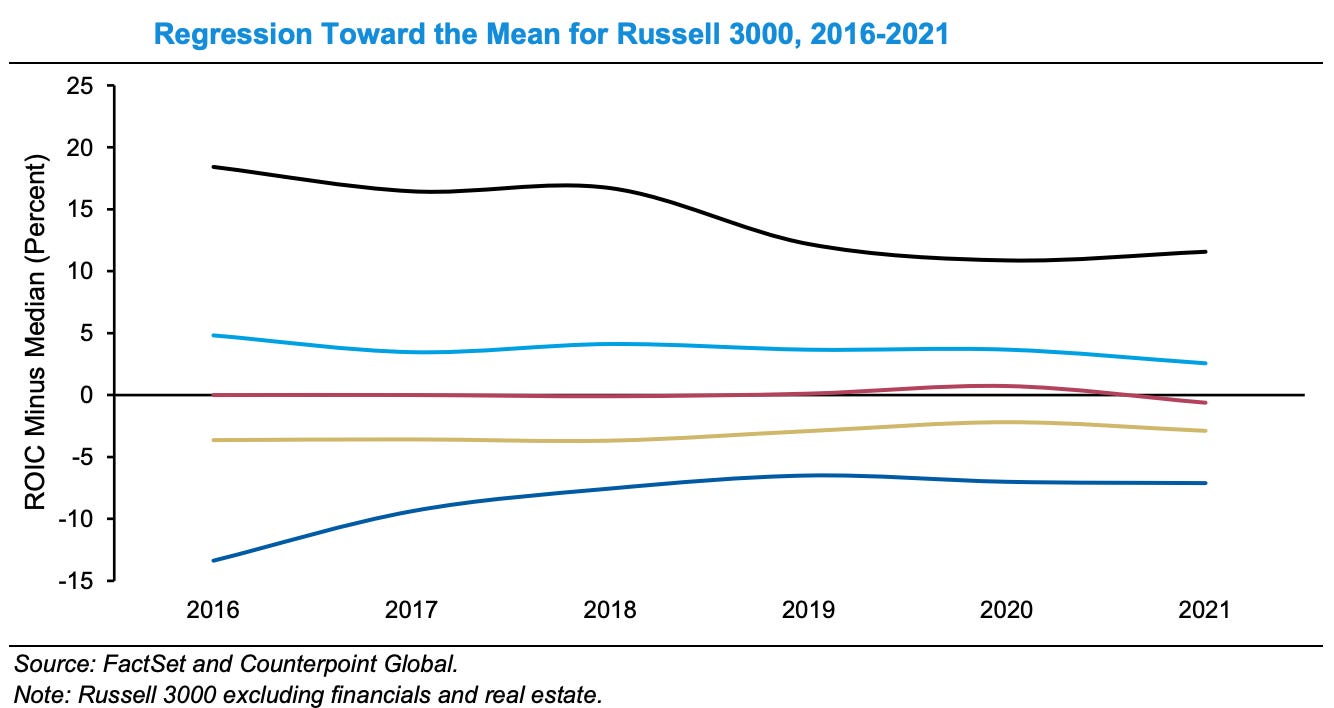
If ROIC and WACC converge, then any incremental growth fails to create value, leading to a net present value of zero.
Error 4: Wacky WACC
The misestimation of the Weighted Average Cost of Capital (WACC) is a complex issue that deserves its own treatment. In TCI 02 we wrote about how to calculate WACC properly, including the limitations of CAPM and how to use Damodaran's implied equity risk premium as a more reliable anchor.
Because WACC feeds directly into the terminal value, and the terminal value can dominate the model, a 1% change in the discount rate can swing the per-share valuation by 25 to 40%. The practical implication is that it’s an error for the WACC to be a single point estimate. Instead, best practice is to run a sensitivity analysis across a range of WACC.
The Three-Stage DCF model available for paid subscribers includes a sensitivity table for exactly this purpose.
A Word on Share-Based Compensation

Under Generally Accepted Accounting Principles (GAAP), Share-Based Compensation (SBC) is classified as an operating expense on the income statement. But because no cash leaves the treasury when the grant is issued, the SBC expense is added back on the cash flow statement. Analysts often take this inflated cash flow figure, subtract capex, and arrive at a Free Cash Flow metric that models the business as if it receives skilled labor for free. Doing this distorts any subsequent DCF analysis.
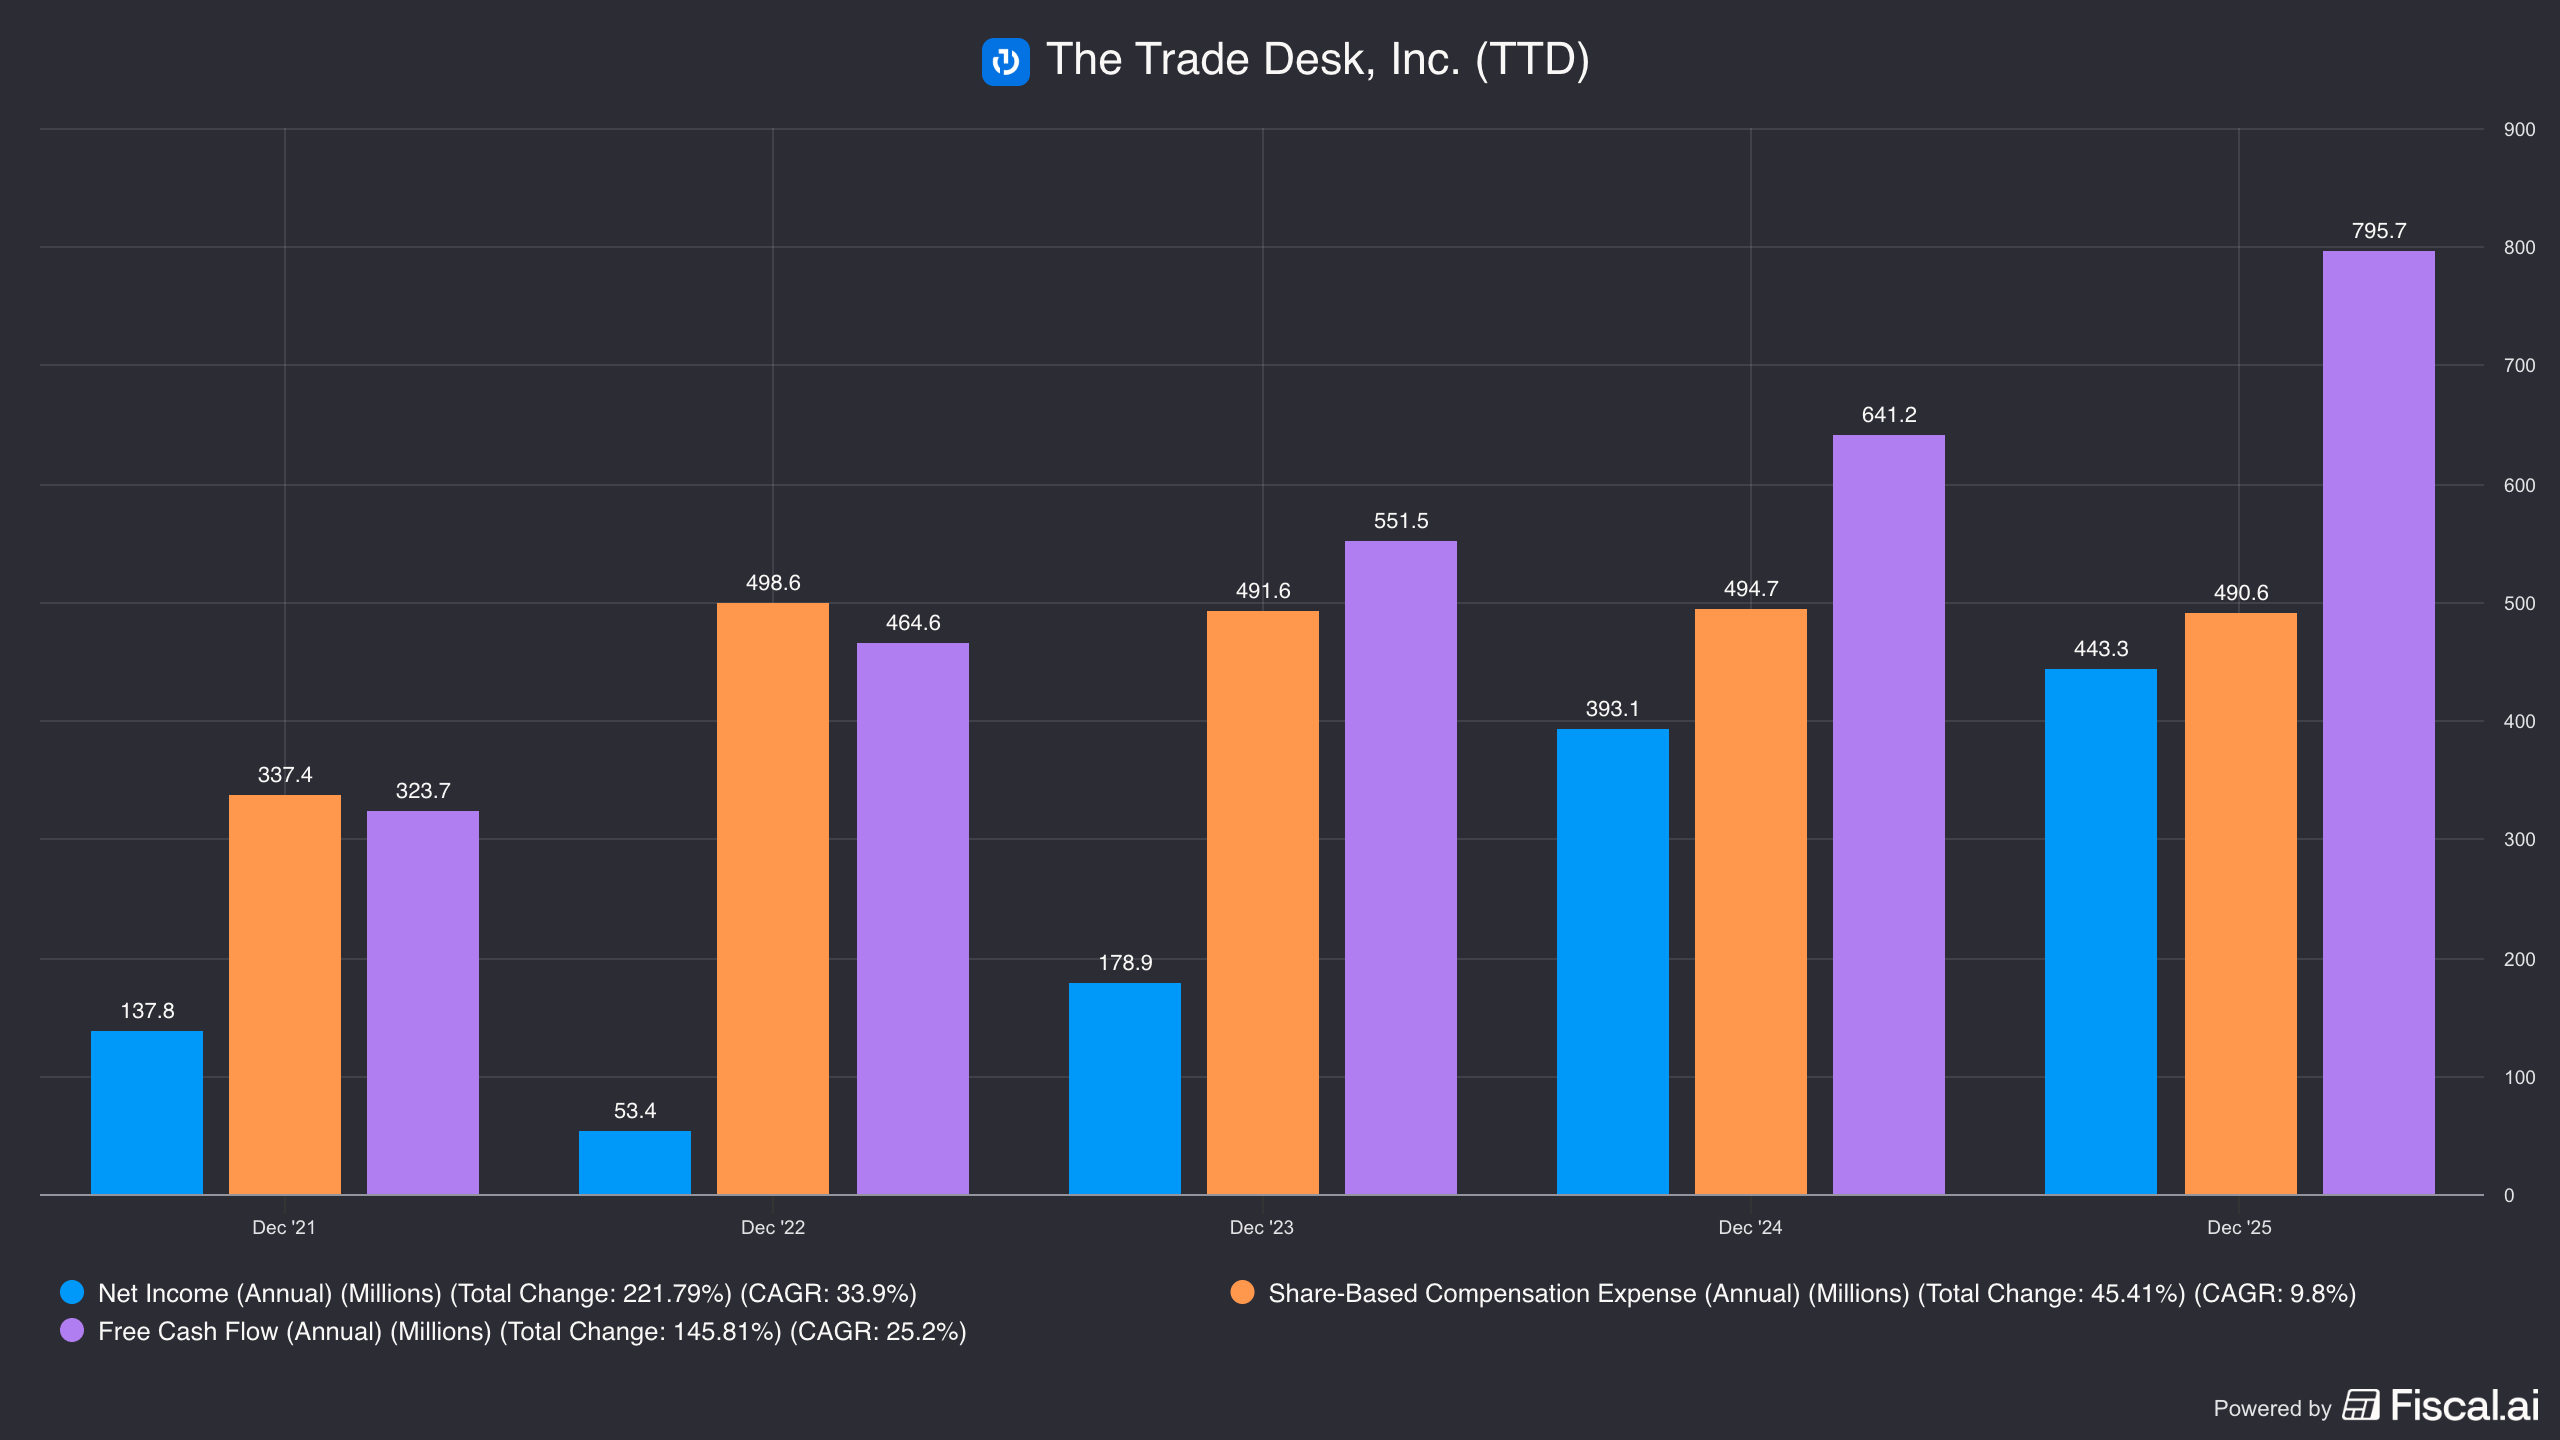
For example, consider The Trade Desk (TTD). For FY 2025 SBC was $491 million, which exceeded net income ($443 million). The reported FCF - with SBC added back - came in at $796 million. However, treating the SBC as an expense reduces the true FCF by nearly two-thirds, to $305 million.
In such cases the impact on a DCF can be enormous. Damodaran and Mauboussin both provide frameworks for correcting it. Let’s explore them further.
Damodaran’s Framework: Expense and Overhang
Aswath Damodaran advocates for a two-pronged approach.
First, treat future SBC as a direct cash flow reduction. The SBC expense must not be added back. Even though it doesn’t immediately drain the bank account, it is a real economic transfer from existing shareholders to employees. By treating projected equity grants as if they were cash expenses, free cash flow is appropriately adjusted.
Second, address past SBC as an equity overhang. Mature tech firms carry massive overhangs of already-granted options and RSUs that represent competing claims on equity value. Damodaran insists the analyst must independently value this pool using options pricing, then deduct it from aggregate equity value before dividing by the basic share count.
Mauboussin’s Approach: Two Paths, Same Destination
Mauboussin and Callahan show there are two valid ways to handle SBC in a Free Cash Flow to Equity framework - and that when applied correctly, both arrive at the same per-share value.
Like Damodaran, the first is the expense method. Here the investor deducts SBC directly from free cash flow, treating it like any other operating cost. The cash flows are lower, but the share count stays fixed.
The second is the dilution method, where the cash flows are unadjusted. Instead of expensing the SBC, the investor projects a continuously growing share count that reflects the ongoing issuance of shares to employees.
The error is mixing the two methods. The investor adds back SBC to keep free cash flow high, borrowing from the dilution method, while keeping the share count static, borrowing from the expense method. The cost of employee compensation disappears from both the numerator and the denominator simultaneously, and the model systematically overvalues the business.
When the Linear Model Breaks: Real Options
Even a perfectly constructed DCF - with sound horizons, growth linked to investment, and honest SBC treatment - remains a linear instrument. It projects expected cash flows along a single path and discounts them at a fixed discount rate. For mature, steady-state businesses with predictable margins and stable demand, it works beautifully.
However, business is often non-linear.
For example, consider an early-stage unprofitable biotech awaiting Phase III trial results. Apply a standard DCF, and the model will say it’s worthless.
The base rates say the drug will probably fail, as most do. But not all fail. The DCF cannot capture this asymmetry - if the drug fails, losses are capped at the R&D already spent. If it succeeds, then upside is unbounded.
That truncated downside with an open upside is an option, and options derive value from volatility. A wider distribution of outcomes - volatility - makes the option more valuable, not less.
Markets routinely assign these companies multi-billion-dollar valuations, taking the consensus view on the value of the option. In these situations, the DCF is the wrong tool.
Not every company has meaningful real option value. While a unprofitable start-up has future optionality, a regulated utility has near-zero optionality. Most companies sit somewhere in between. For example, Amazon’s core retail and AWS operations are reasonably modelled by a DCF, while its emerging robotics and chip-design businesses would be real options.
What separates companies with genuine option value from those without comes down to three things: management that can identify and exercise options at the right moment (Microsoft’s Azure was conceived under Ballmer but only scaled under Nadella, funded by Office cash flows), a dominant market position that ensures they get the first call when opportunities emerge, and a wide enough distribution of possible outcomes to make the optionality worth pricing.
For many businesses in a quality portfolio, the option component is negligible and the DCF does the work. For others, it may represent the majority of the firm’s value.
Real Options in Practice
There are a few ways to value real options. The standard academic (and admittedly unwieldy) approach is the Black-Scholes model, developed for financial options.
This model maps directly onto real options using the same five variables: the value of the underlying asset (the project's present value), the exercise price (the cost of investment), time, the risk-free rate, and volatility. Higher volatility makes a financial option more valuable; the same is true for a real option, because a wider distribution of outcomes expands the upside while the downside remains capped.
However, the Black-Scholes model has limits as it assumes continuous trading, perfect liquidity, and observable and stable volatility. None of these assumptions apply cleanly to the real world.
So, what’s an investor to do?
Start with a simple calculation: take your DCF estimate of the company’s existing operations and subtract it from the current market cap. What’s left is what the market is paying for optionality. Call it the imputed option value.
For example, recall the Tesla DCF above - the bull case led to a fair value of $170 per share. At the time of writing, the current share price is $376.
This means that the market is pricing a real option worth $206 for Tesla.
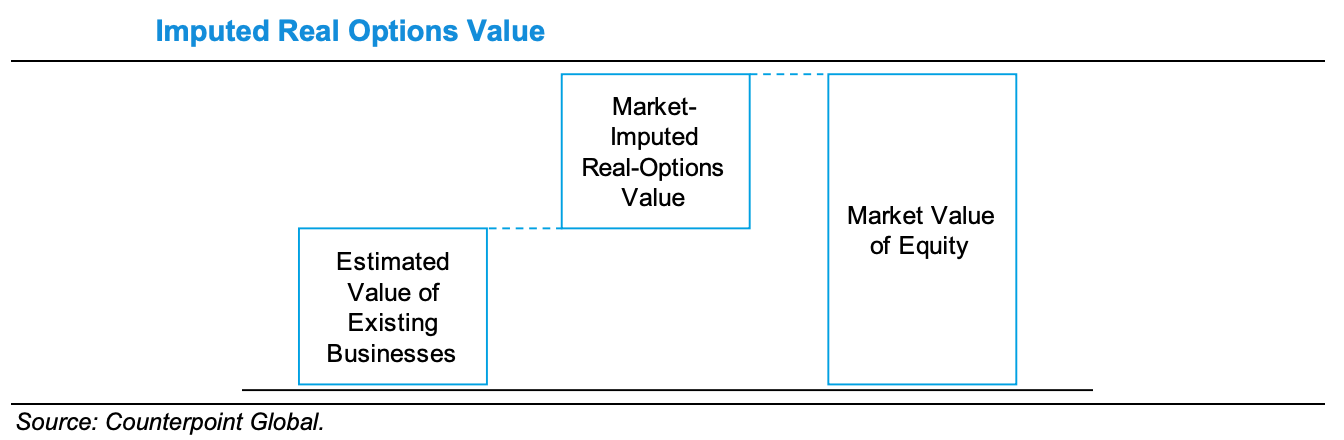
The investor then must judge whether that is warranted. To answer it, Mauboussin offers a 2x2 matrix that turns this into a decision:
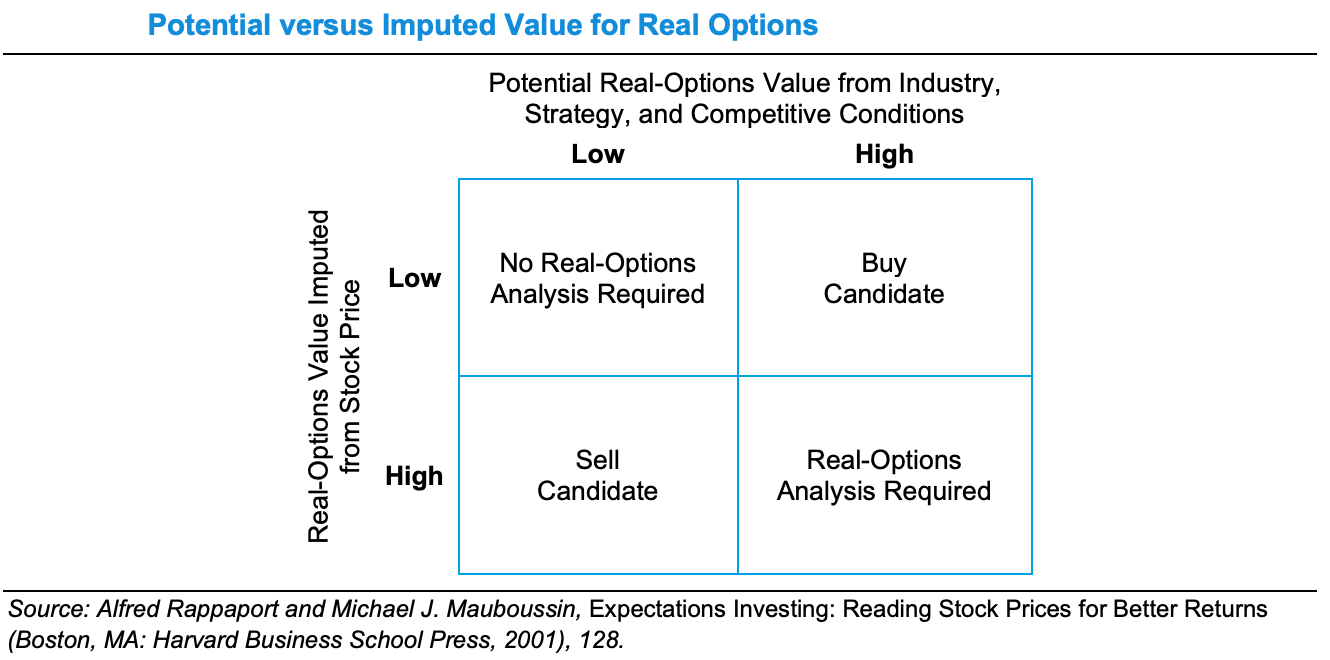
If potential is low and imputed value is low, standard DCF analysis is sufficient. No options work needed. A regulated utility lives here.
If potential is high but imputed value is low, this is a buy candidate. The market isn’t pricing the optionality, which means you may be getting it for free. Early-stage Amazon in 2005 arguably lived here as the DCF of the retail business was modest, and AWS was invisible.
If potential is low but imputed value is high, this is a sell candidate. The market is paying for options that don’t exist. This is where narrative-driven speculation tends to cluster.
If both potential and imputed value are high, real options analysis is required before you can form a view. The market believes the options exist and is pricing them - the job then is to assess whether the magnitude is reasonable. So, anyone buying TSLA at this level needs to judge for themselves if the robotaxi, Optimus, AI and Elon Musk is worth at least $200 per share.
Often, a high P/E is a sign that the market is pricing in a real option. When doing any valuation, the investor needs to know which quadrant they are living in.
The Complete Toolkit
Paid subscribers will have access to the three-stage DCF model, the PIE reverse DCF model, and an error checklist at the end of the article.
Let’s put it all together.
In TCI03, we introduced the auditor’s instrument - the reverse DCF. It tells you what the market believes about growth, margins, capital intensity, and duration. It transforms the investor from a forecaster into an expectations analyst.
In this issue, we now complement it with additional tools.
The Damodaran three-stage DCF is constructed by marrying story with economic soundness. It uses explicit forecast periods that capture the competitive advantage period, growth assumptions linked to investment, a terminal growth rate that respects macroeconomic reality, and honest SBC treatment throughout. This is the blueprint for the future, to complement the audit.
And Real Options theory respects that business reality is generally beyond the boundary of linear predictability. The option-pricing framework captures the asymmetric value of strategic flexibility that a standard DCF can’t.
Different instruments illuminate different facets of the same underlying reality. Like the parable of the blind people and the elephant - where each is certain they understand the whole from the part they can perceive - the investor who relies on a single tool fails to see the big picture.
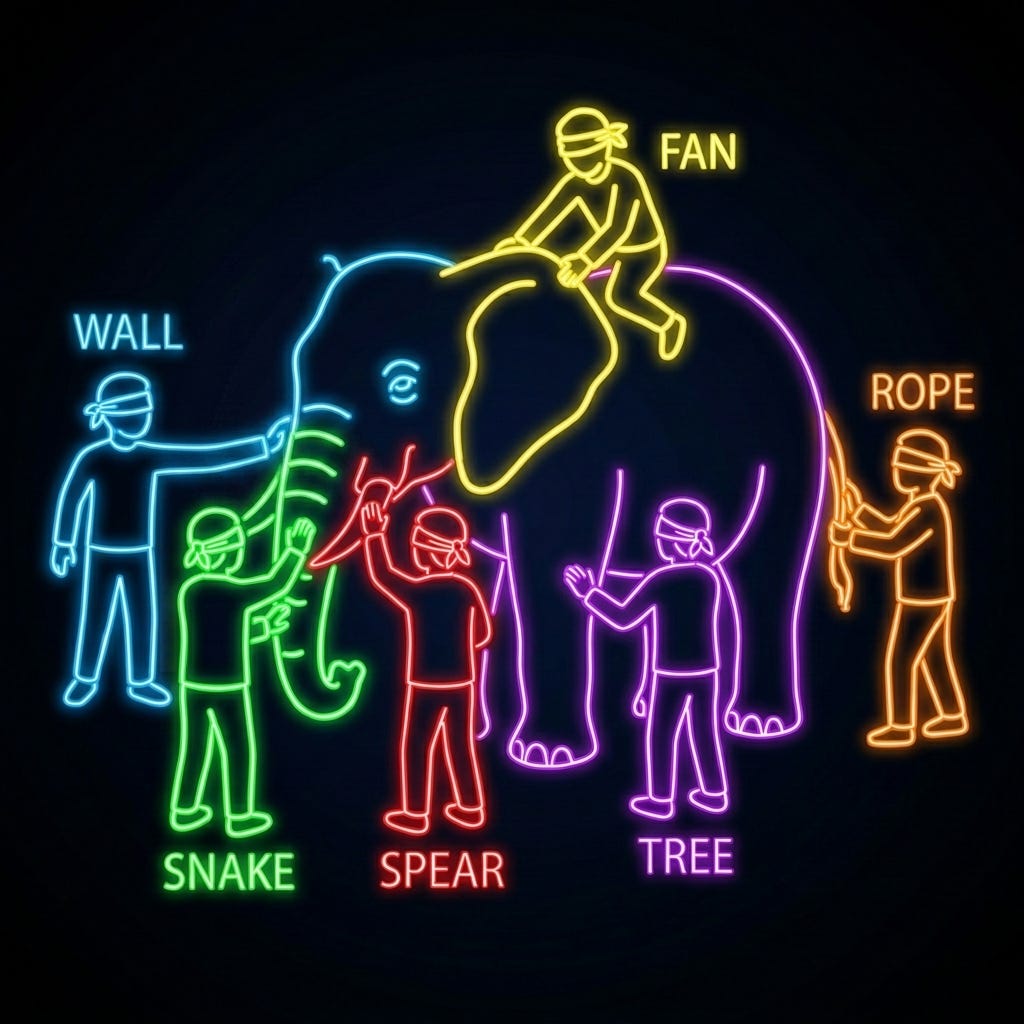
The reverse DCF and forward DCF are not contradictions - they are the same equation, solved from opposite ends. And when neither captures the full picture, real options fill the gap.
The consilient investor's valuation toolkit has now been assembled. We now know how to appraise what a business is worth.
Next issue, we'll assess whether the managers running it deserve that capital.
If you enjoyed this analysis, continue the pursuit.
Catch up on all past posts in our Library.

Further Reading
Caltech’s Commencement Address. Richard P. Feynman (1974)
Everything Is a DCF Model, Michael J. Mauboussin and Dan Callahan, Consilient Observer: Counterpoint Global Insights (2021)
Common Errors in DCF Models, Michael J. Mauboussin, Legg Mason Capital Management, March (2006)
WACC and Vol: Valuation for Companies with Real Options, Michael J. Mauboussin and Dan Callahan, Consilient Observer: Counterpoint Global Insights (2020)
Narrative and Numbers: The Value of Stories in Business, Aswath Damodaran, Harper Business (2017)
Expectations Investing. Michael J. Mauboussin and Alfred Rappaport, Columbia Business School Publishing (2021)
The Theory of Investment Value. John Burr Williams. BN Publishing (1938)