

Early in 2026, Constellation Software Inc (CSI) found itself under notable pressure, and shares were down nearly 50% peak-to-trough. The company found itself swept up in artificial intelligence fears rippling through the market.
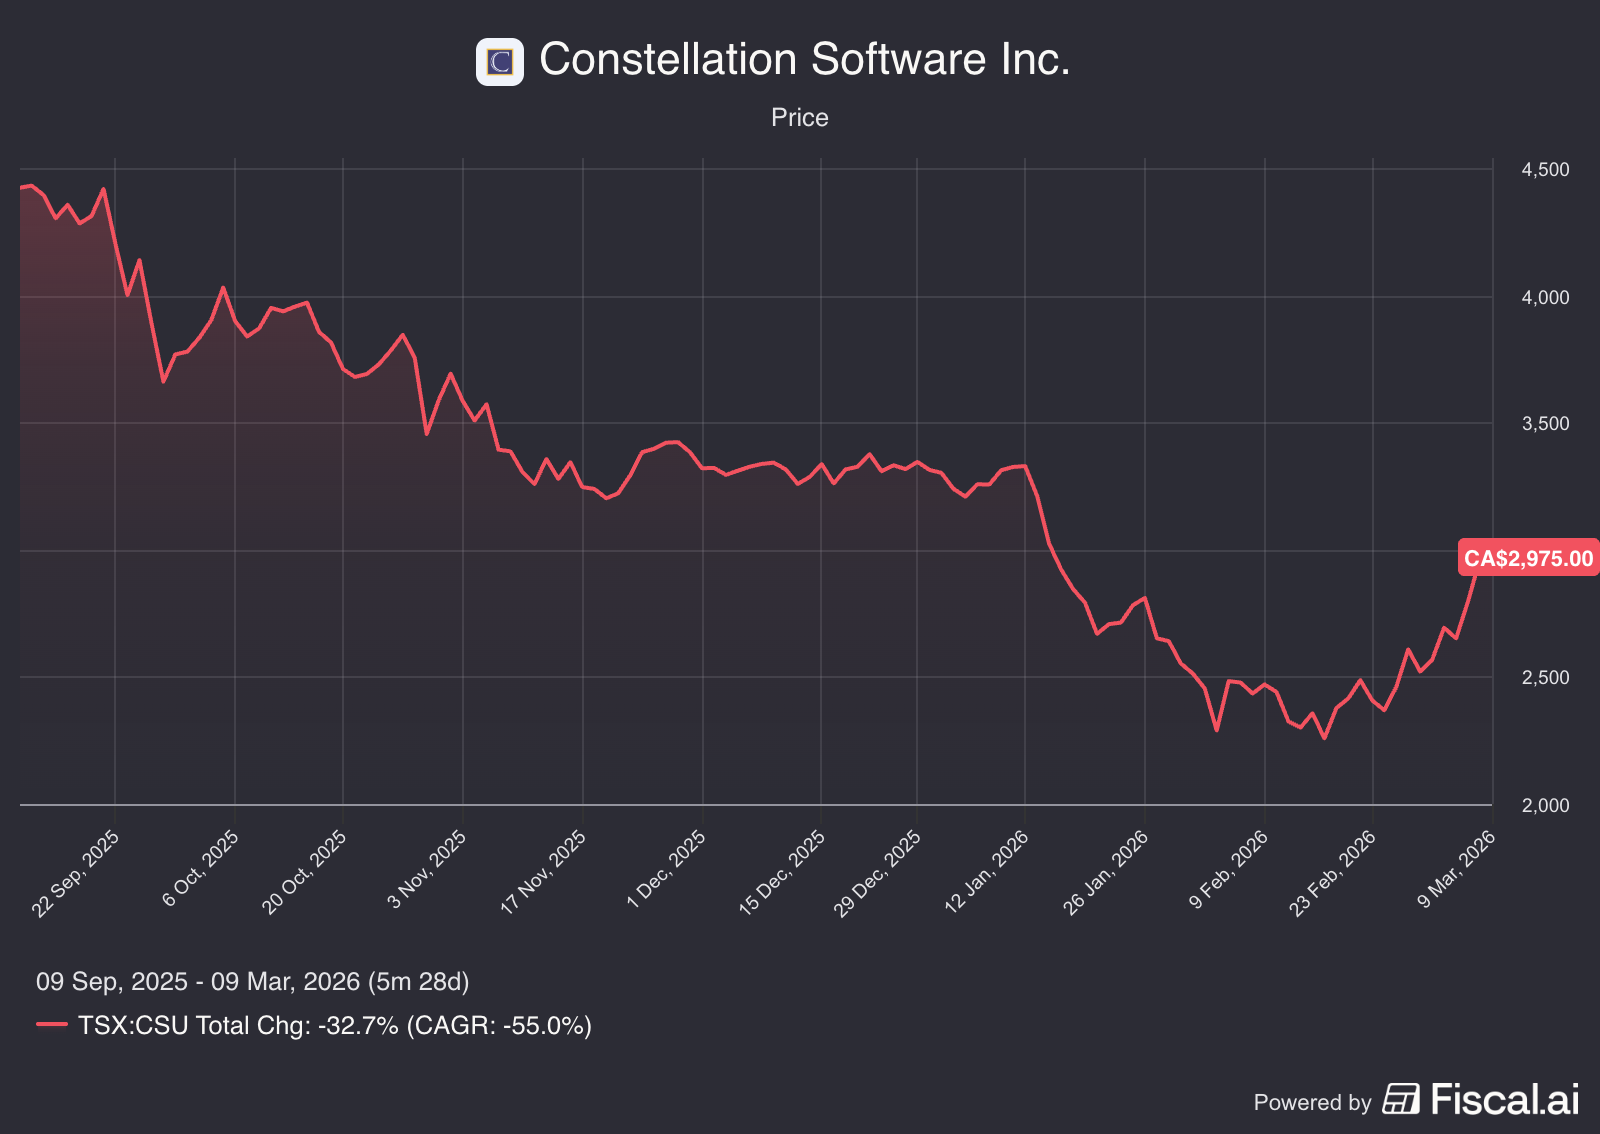
The predominate fear is that AI-driven coding capabilities could lower entry barriers and threaten the historically impenetrable moats of niche software providers.
Beneath the noise of this AI-driven market volatility, CSI continues to operate as a decentralized serial acquirer of Vertical Market Software (VMS) businesses. The company relies on acquiring mission-critical, niche software providers, optimizing their operations to generate high-margin recurring revenue, and utilizing the resultant free cash flow to fund a continuous pipeline of subsequent acquisitions.
In this post, we review the recent financial results, dissect the firm’s revenue trajectory, unpack its Free Cash Flow Attributable to Shareholders (FCFA2S), and apply the Michael Mauboussin operating framework to calculate exact Return on Invested Capital (ROIC) and Return on Incremental Invested Capital (ROIIC). Finally, we’ll conclude with a five year discounted cash flow.
Are AI cracks starting to show in the results? Or is the VMS stalwart showing that the market narrative is unfounded? Let’s find out.

Today’s article is free and so if you enjoy it, please share!
The Structural Advantages of the Constellation Model
To properly contextualize the 2025 financial results, it helps to understand the three pillars of CSI operating model - negative working capital, decentralization and disciplined capital allocation.
CSI’s businesses primarily sell software licenses bundled with ongoing maintenance contracts or SaaS subscriptions. Customers are typically billed annually in advance. Because CSI collects cash before it incurs the expenses required to deliver the service, the aggregate business operates with deeply negative net working capital. This provides a continuous stream of zero-cost capital that the company can then reinvest at high rates of return. This has allowed CSI to continually grow with minimal use of debt or share issuance.
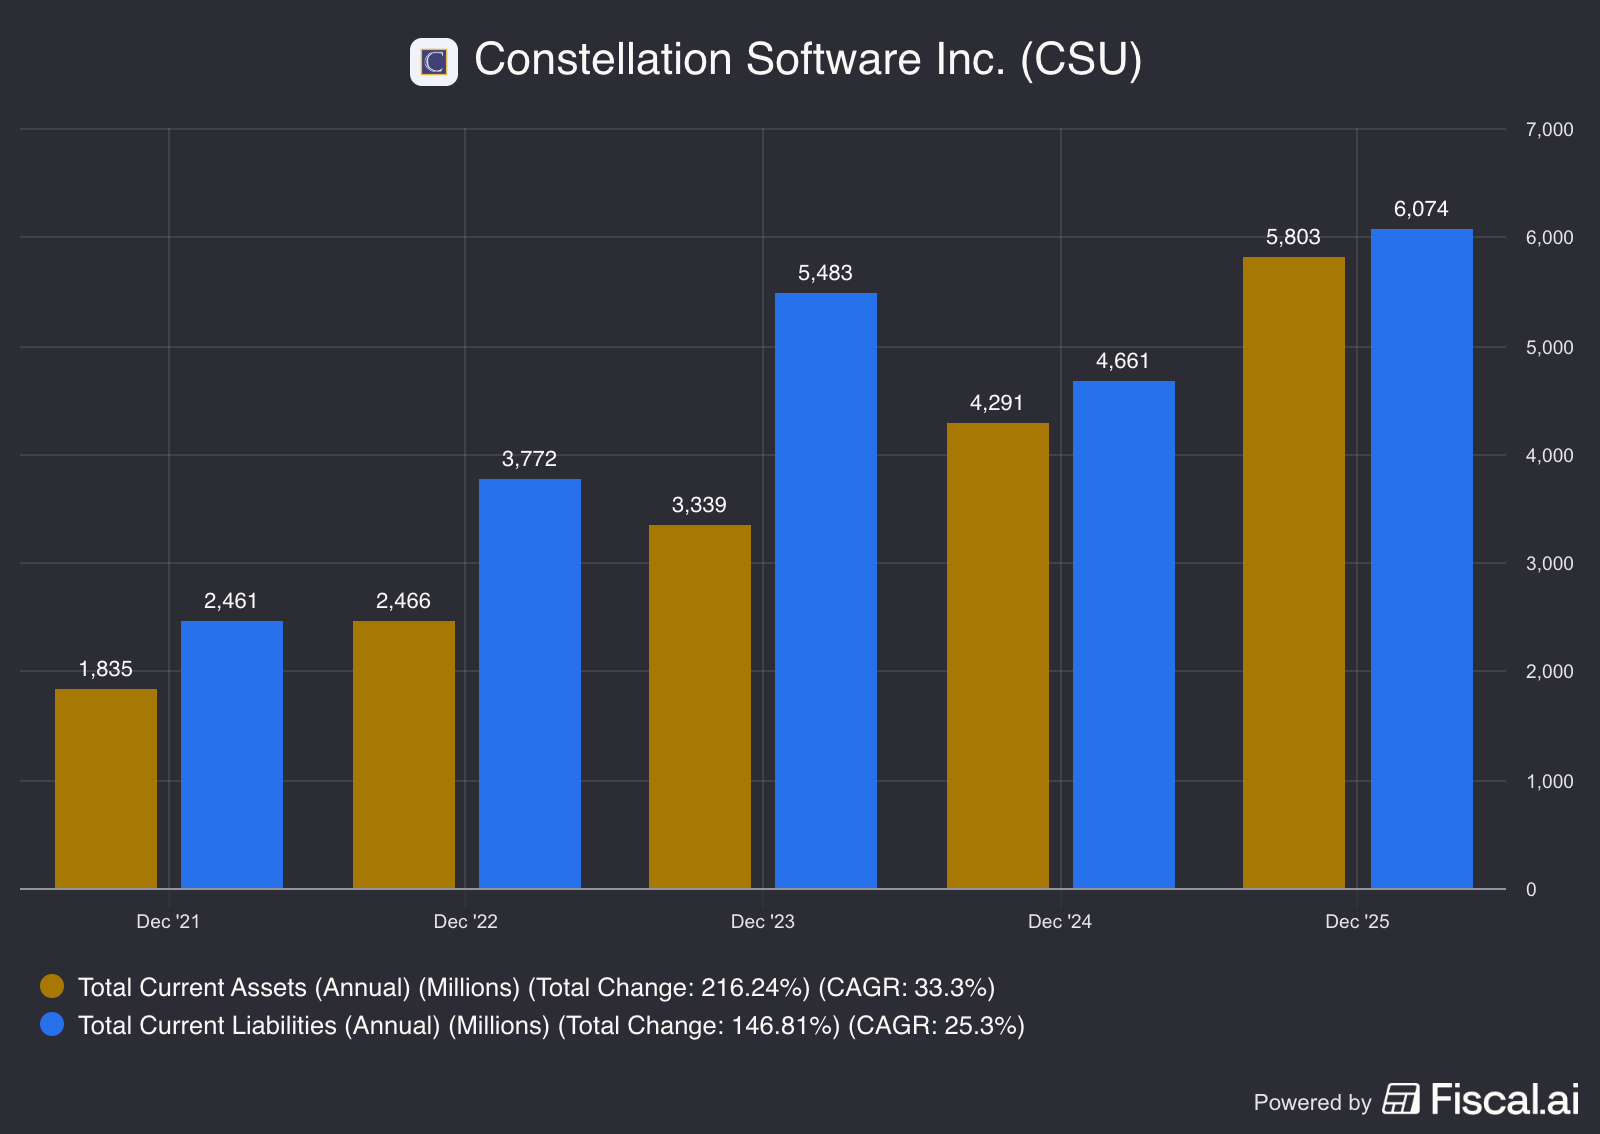
Further, CSI is a holding company managing hundreds of autonomous business units across six primary operating groups. Each operating group will oversee business units, who then oversee specific product lines or businesses. Within each operating group there are 1000+ individual VMS businesses.
Excess cash generated by the individual business units is systematically repatriated to portfolio managers at the operating group level, who then focus on allocating that capital to new acquisitions. This structure allows CSI to quickly process and close hundreds of small, sub-$10 million acquisitions annually, bypassing the intense competitive bidding processes that characterize mid-market and large-cap private equity transactions
By pushing capital allocation responsibilities down the chain CSI mitigates bureaucratic calcification, allowing it to continually grow and scale without being bogged down by corporate red tape. The highest levels of management are only involved in the largest acquisitions (e.g. $100+ million).
Managers are incented to allocate capital at high rates of return. Target IRRs are rumored to vary from 20-30% depending on the size of the deal, with smaller deals commanding higher IRRs (e.g. 30%).
Historically management has been exceptionally disciplined and price focused. Managers are required to invest the majority of their cash bonuses in CSI stock (bought on the public market) and so they are owners as well. All of this taken together has led to exceptional fundamental compounding - since going public in 2006 it has been a 250 bagger with a CAGR of ~ 35%.
Now with this primer, let’s dig into FY 2025.
Q4 2025 and FY 2025 Financial Performance Review
Released on March 9 2026, the Q4 / FY 2025 results showcase the continued scale of the business. GAAP reported numbers are messy though, due to the non-cash accounting treatments required under IFRS. We’ll unpack that further below.
Revenue Trajectory and Composition
For FY 2025, Constellation reported total consolidated revenue of $11,623 million, a 15% increase compared to $10,066 million in 2024. Q4 2025 contributed significantly, scaling to $3,177 million (up 18% YoY).
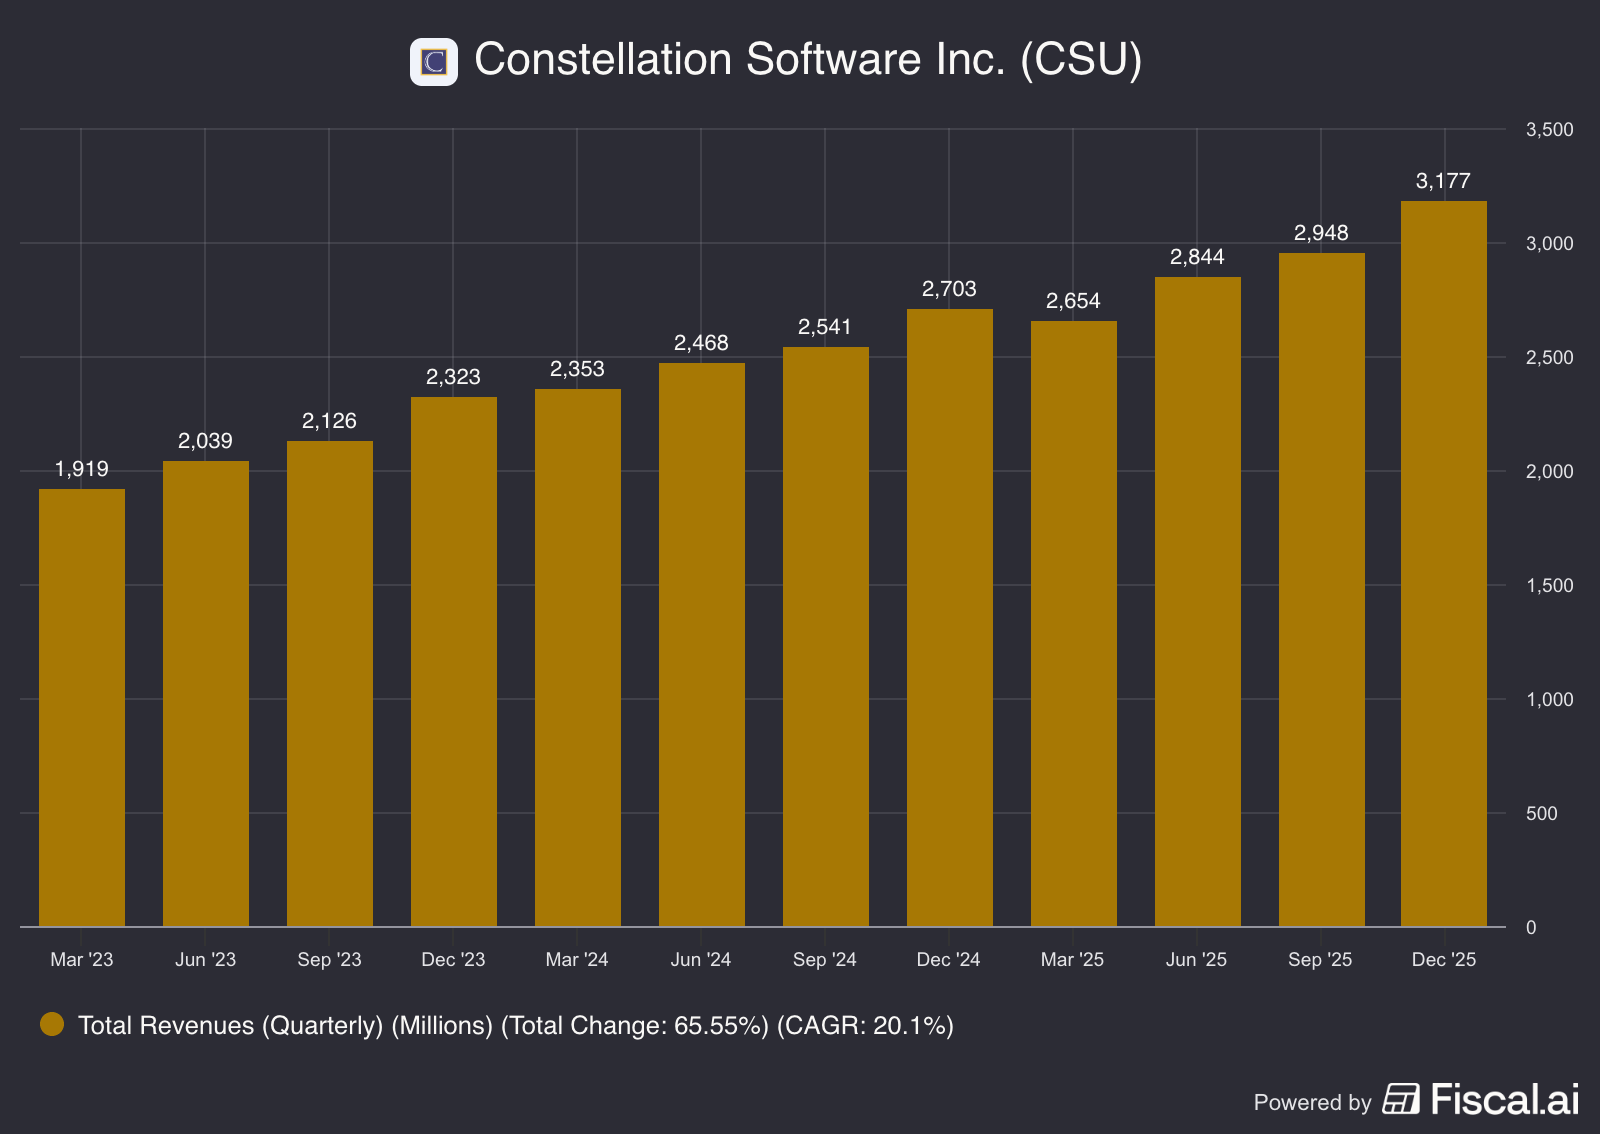
Nearly 75% of the company’s revenue is derived from recurring maintenance and subscription fees. This line item primarily consists of fees charged for post-delivery customer support, fees from combined software/support contracts, transaction revenues, managed services, and hosted SaaS products. The sticky, recurring nature of this revenue provides massive downside protection and unmatched cash flow visibility during economic downturns.
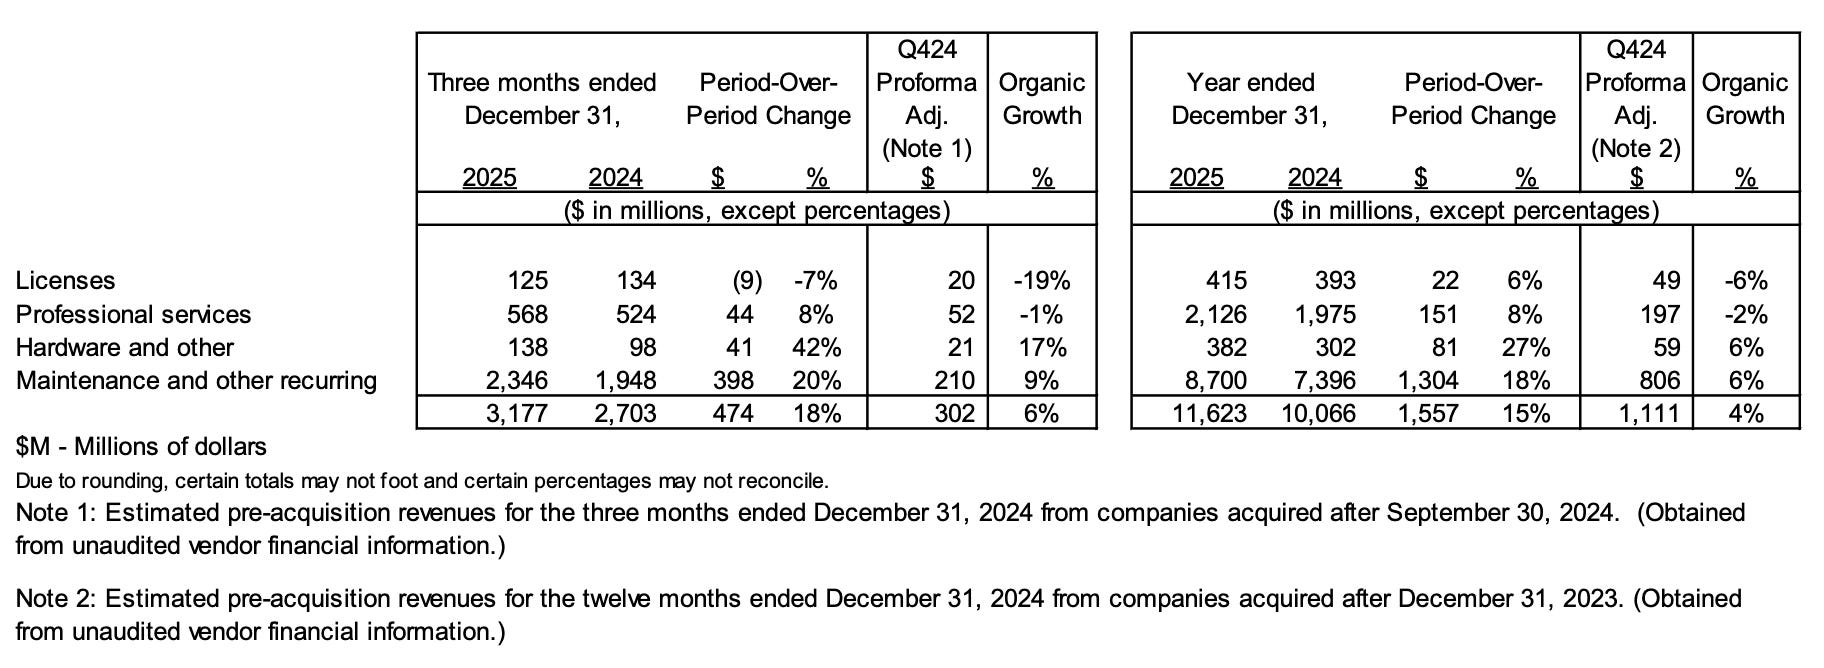
When stripping out acquired revenue, the company achieved organic growth of 4% for FY 2025 (3% after adjusting for foreign exchange fluctuations). The most important revenue line item - maintenance and recurring - showed 6% organic growth on a constant currency basis.
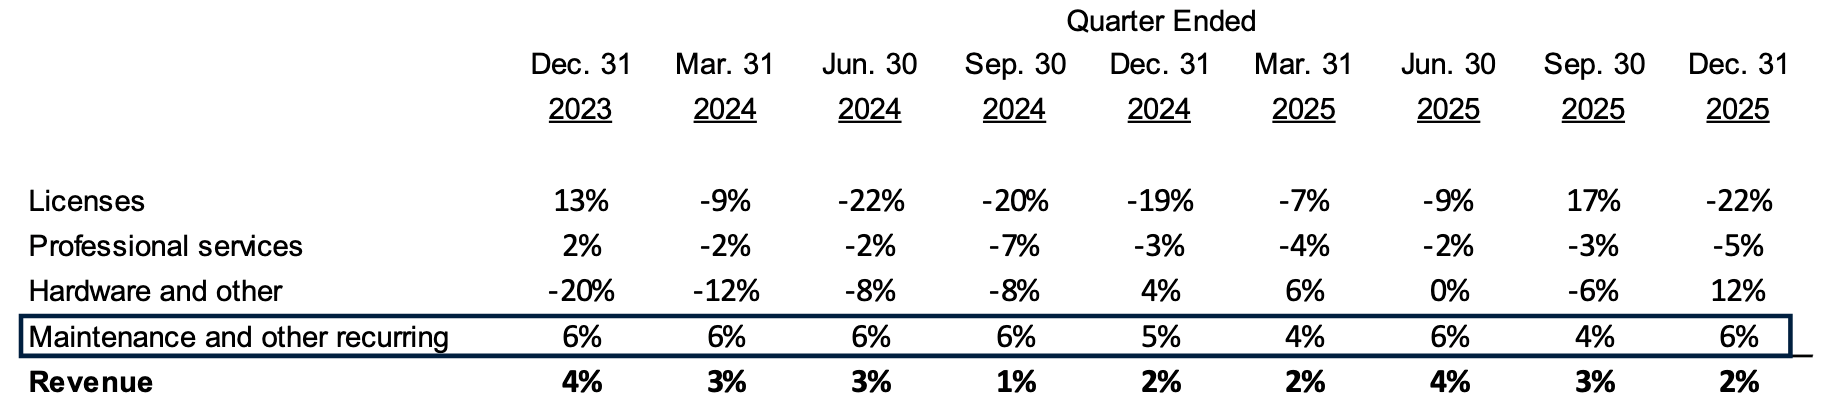
This is an important metric to monitor - if AI is eroding their competitive position, then we should see organic growth in maintenance and other recurring begin to drop, as customers churn away from their CSI VMS product.
Net Income Profitability
Total operating expenses for 2025 amounted to $8,546 million (up 13% YoY). As a percentage of total revenue, operating expenses declined slightly to 73.5% in 2025 from 75.1% in 2024, indicating a marginal improvement in operating leverage.
Earnings Before Interest and Taxes (EBIT) is not explicitly reported due to IFRS requirements, but pre-distortion EBIT can be approximated at $1,236 million by taking income before income taxes ($939 million) and adding back finance costs ($297 million). However, this figure is severely depressed by two massive non-operating distortions.
The first is the IGRA / TSS Membership Liability Revaluation Charge. This is put option held by minority shareholders (Joday Group, among others) in Topicus, and it must be revalued every quarter.
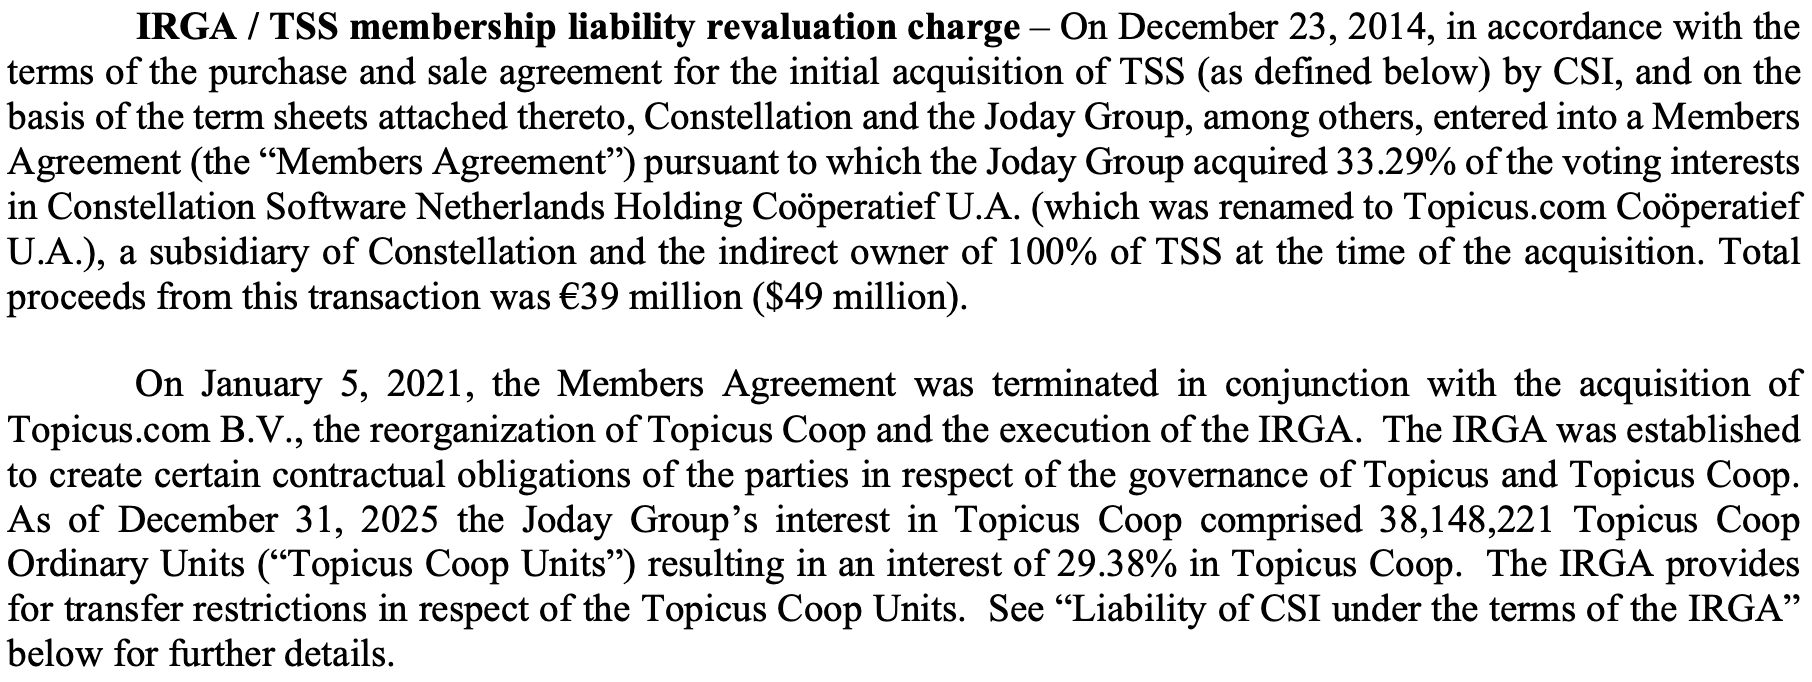
Strong operational performance and stock appreciation at Topicus necessitated a non-cash revaluation charge of $440 million expensed directly through Constellation’s 2025 income statement. Paradoxically, excellent operational performance at the Topicus level punishes Constellation’s statutory net income (blue box in figure below).
The second relates CSI’s accumulation of shares in Asseco Poland S.A. Early in 2025, the company purchased a 9.99% stake in Asseco, electing to record it as an equity security held at fair value through other comprehensive income.
Subsequently, the company entered a binding agreement to acquire an additional 14.84% of Asseco’s treasury shares. Upon receiving regulatory approval in September 2025, CSI’s total stake reached 24.84%, crossing the threshold required to exercise "significant influence" on the company.
Thus, IFRS accounting rules dictated that the company must transition from fair-value accounting to the equity method of accounting, recording the investment at cost. This one change created a non-cash income of $260 million, that was recognized in the 2025 income statement (green box below).
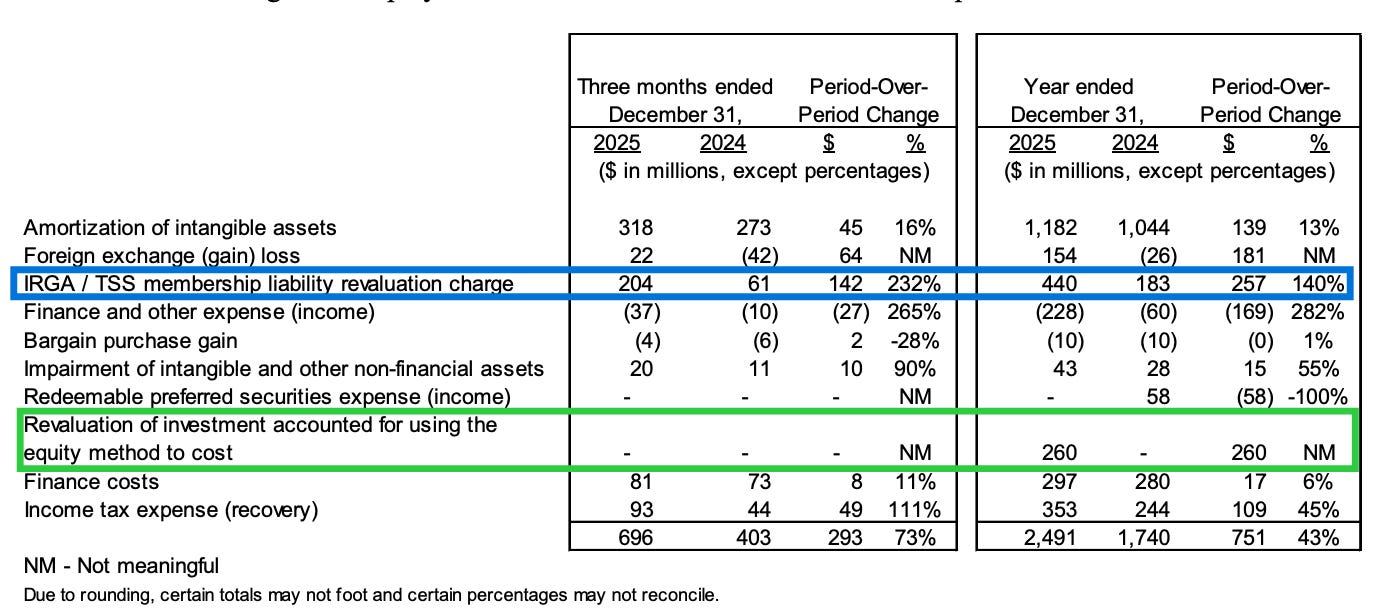
These two accounting quirks substantially alter net income. However, the income statement is not the most important statement to watch for underlying business performance - it is always noisy for CSI. Instead, we must follow the cash.
Free Cash Flow
To bridge the gap between statutory accounting and economic reality, we look to Free Cash Flow Attributable to Shareholders (FCFA2S). This Non-GAAP / Non-IFRS metric is calculated by management as net cash flows from operating activities, less interest paid on lease obligations, interest paid on debt, debt transaction costs, payments of lease obligations, the IRGA liability revaluation charge, and property and equipment purchased.
It then adds back interest and dividends received, and crucially, deducts the free cash flow attributable to non-controlling interests (such as the minority shareholders of Topicus and Lumine).
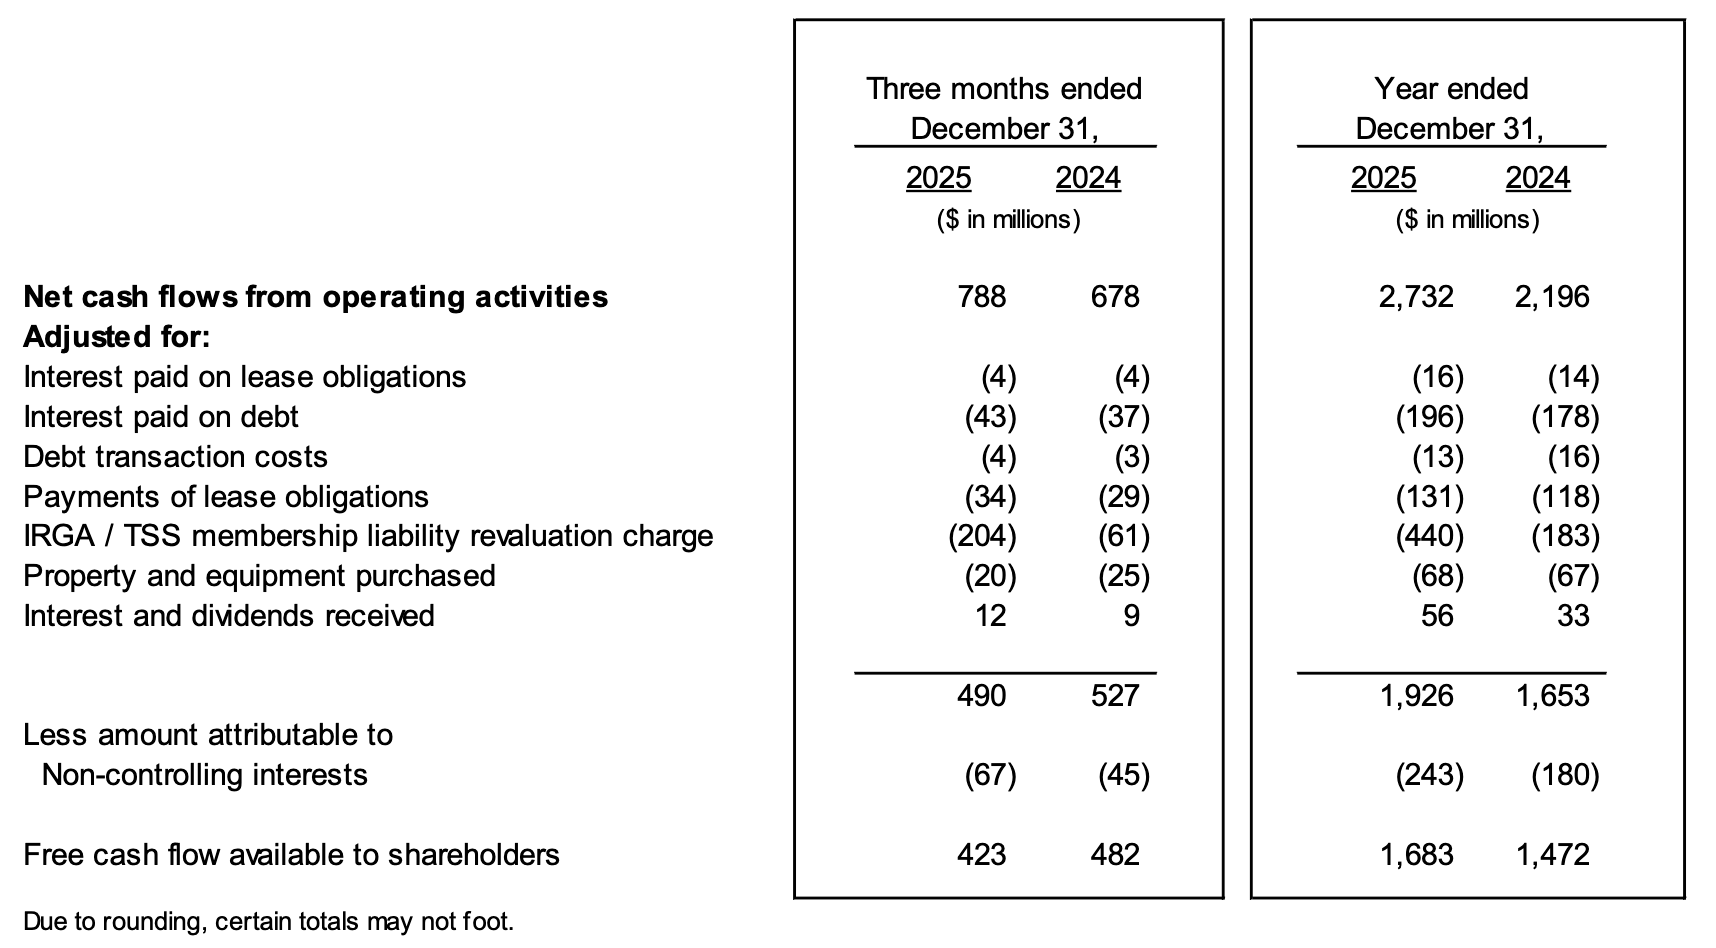
The 14.3% growth in FCFA2S encapsulates the true economic engine of the business, and is the economic north star for any CSI investor, and it has been growing at an 11% CAGR over the last five years.
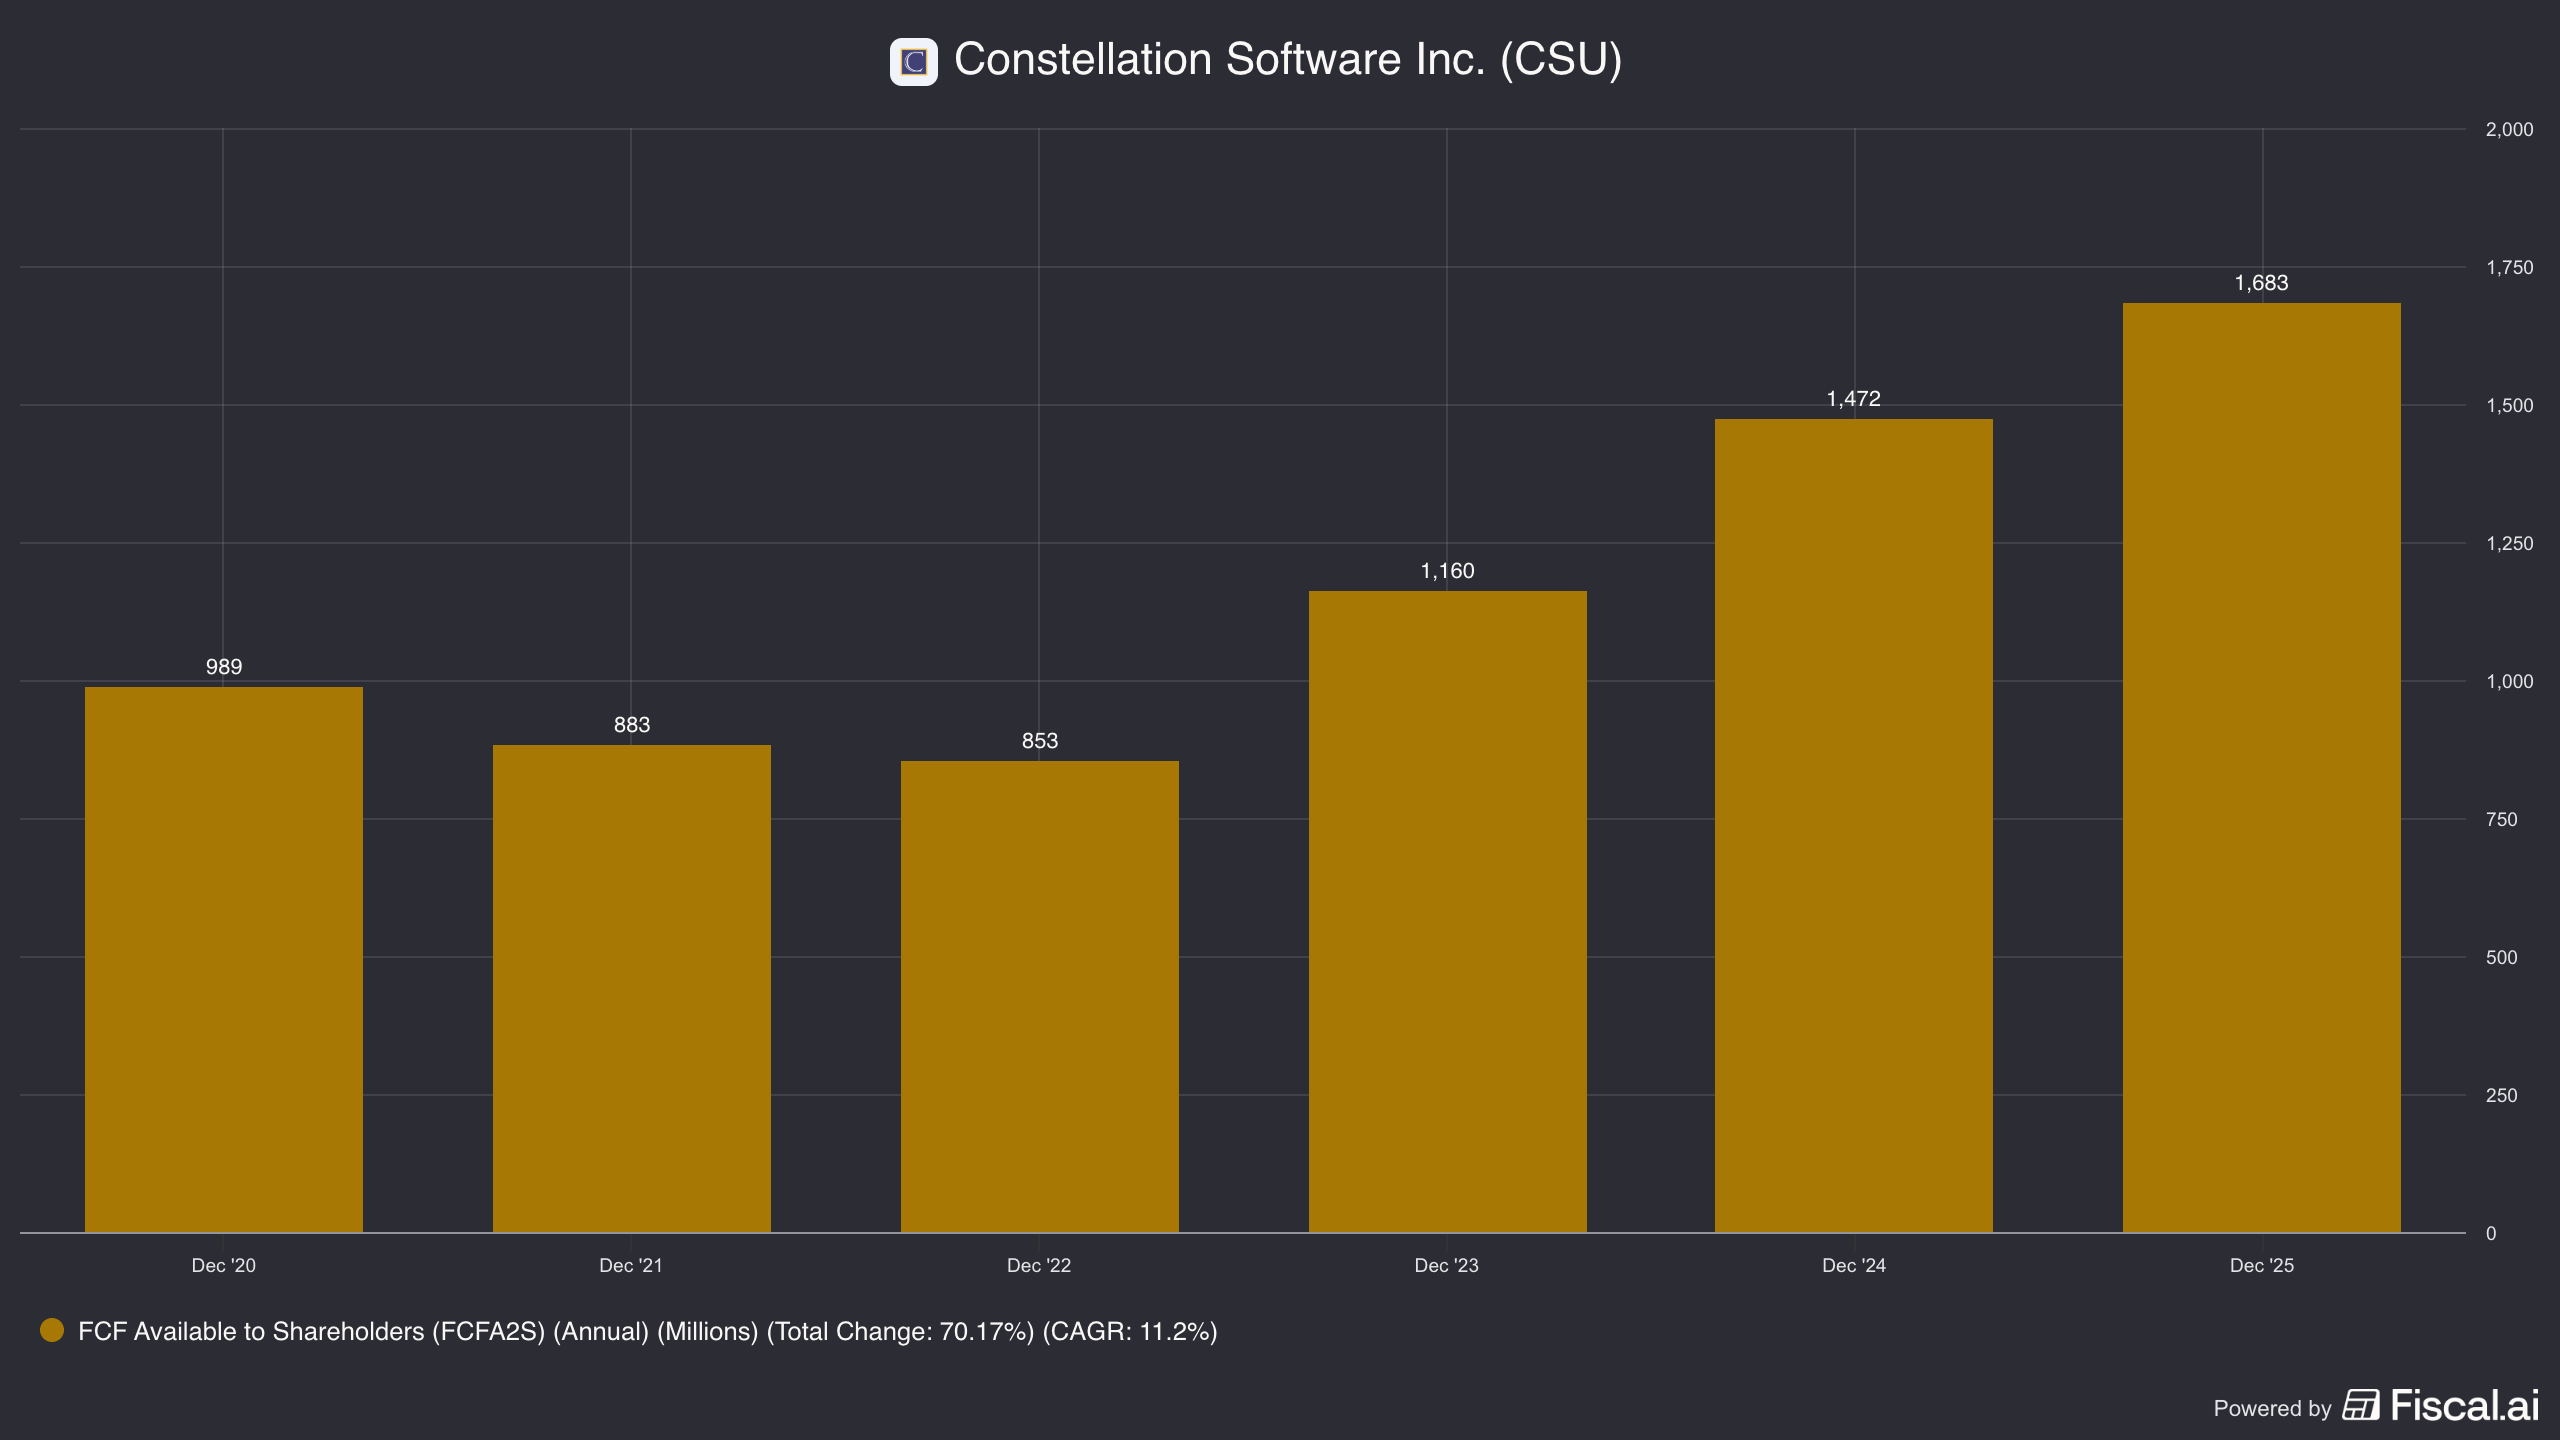
Reinvestment Rate
Constellation’s stated objective is to invest 100% of its FCFA2S in acquisitions that meet internal hurdle rates. The Reinvestment Rate is calculated by dividing the total cash used for acquisitions by the FCFA2S generated in the same period:
2023 Reinvestment Rate: 154.5% ($1,792M deployed vs $1,160M FCFA2S)
2024 Reinvestment Rate: 114.3% ($1,683M deployed vs $1,472M FCFA2S)
2025 Reinvestment Rate: 89.9% ($1,513M deployed vs $1,683M FCFA2S)
While maintaining a high reinvestment rate is mathematically essential for compounding, the slight dip to 89.9% in 2025 highlights the growing challenge of the “law of large numbers” - deploying $1.7 billion annually at high hurdle rates is increasingly difficult, regardless of level of decentralization.
Moving forward, CSI needs increasingly larger acquisitions to move the needle. They are signalling that they are going to be doing this at least in part via public markets, initially with Asseco, and now with Sabre Corporation (NASDAQ: SABR).
Return on Invested Capital (ROIC)
Although there are many ways to calculate Return on Invested Capital (ROIC), we generally prefer the Mauboussin operating method. This methodology adjusts statutory figures to reflect the true economic cash earnings of the operating business, devoid of capital structure noise and accounting distortions. For those interested in learning more, we write about it extensively in the post below.

For CSI we’ll show two calculations - NOPAT and FCFA2S. The goal of using NOPAT is so that the calculation can be standardized across companies and industries, although we are more interested in FCFA2S. Why?
If FCFA2S is the economic north star, then using it to calculate ROIC / ROIIC gives us a gauge for what is happening to internal IRRs with time (are they increasing, or decreasing)? As acquisitions sizes increase, then we should see IRRs decrease, as the internal hurdle rates decrease.
For the invested capital base, we’ll use the same denominator (adjusted invested capital) for both calculations, as outlined within the Mauboussin framework.
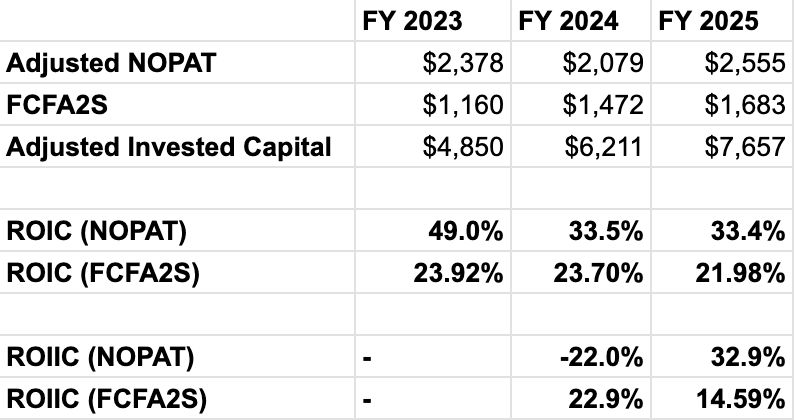
The degradation in NOPAT ROIC from 2023 to 2024 (49.0% to 33.5%) is largely a mathematical artifact of the massive $597 million non-cash redeemable preferred securities expense incurred in 2023, connected to the WideOrbit acquisition, which inflated the 2023 Adjusted NOPAT when added back.
Using the cleaner FCFA2S metric, the return profile is fairly stable, albeit a bit down from 23.9% in 2023 to 22.0% in 2025. This slight compression is natural given the deployment of over $4.9 billion in capital across those three years; newly acquired assets inflate the denominator immediately but require time to reach optimal margin profiles to support the numerator. Assuming hurdle rates are met, then this should increase with time.
We can look to ROIIC to provide a critical lens into the efficiency of recent capital deployment, although it is often inherently fluctuant year-over-year. Nonetheless, the drop to 14.8% in 2025 warrants observation; it suggests that the integration of the 2024 acquisition cohort (which required $1.68 billion in capital) is yielding cash at a lower initial rate. The near-term drop is consistent with CSI’s strategy of acquiring sub-optimized businesses and slowly raising prices and cutting costs over a 24-to-36-month horizon.
However, it could also signal as that their internal hurdle rates are continually going down as they have to chase larger and larger deals, which means the days of super-normal returns are reverting to the mean.
Management has shown that they are not beholden to VMS and are chasing Horizontal Market Software (HMS) and hybrid hardware / software companies as acquisition targets, implying that they prize the internal hurdle rate over the VMS business model specifically for acquisitions.
Regardless, for any long only CSI holder the ROIC and ROIIC trends are certainly something to watch.
Five Year Discounted Cash Flow (DCF) Valuation
We constructed a 5-year DCF model utilizing an FCFA2S exit multiple approach, as the company is unlikely to be at a terminal growth rate in five years. For reference, at time of writing the current FCFA2S multiple is 27. Although CSI’s cost of capital is estimated to be about 6-7%, we’ll use a discount rate of 10%.
Growth rate can be estimated by taking ROIC x reinvestment rate. So for example, if the investor believes they can reinvest 90% of their FCFA2S at a 20% average ROIC, then the growth rate would be 18%. Of course, this ignores any organic growth and assumes all future growth comes only from acquisitions.
As their financials are reported in USD, we will calculate the share price in USD.
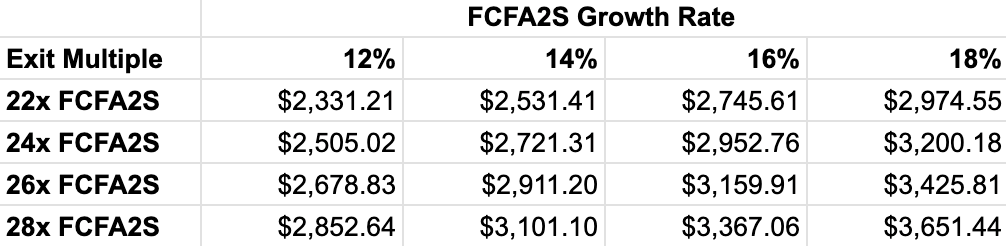
Even with a fairly conservative growth rate by CSI standards (12%) and with multiple compression (from 27X to 22X) shares are undervalued today at about $2331 USD / $ 3170 CAD. For reference, the share price at time of writing is $2970 CAD.
The Verdict
The Q4 / FY 2025 show more of the same, which is a good thing. CSI remains an exceptional capital allocator operating within one of the most economically resilient sectors in the global market - VMS. There are no AI cracks appearing in the core business, as both revenue and organic FCFA2S growth rates appear to be healthy. With these results it appears that the compounding is continuing on a trajectory double-digit trajectory.
Management is actively pursuing AI initiatives as well, using AI coding during development, deploying agents across their products when customers want them. If successful, there is a chance that organic growth may accelerate.
Regardless, the primary risk to CSI isn’t AI, it’s the gravitational pull of its own success. To maintain historical growth, the company must now deploy over $1.5 billion to $1.8 billion annually. Buying 200 small companies a year stops moving the needle.
To circumvent this, CSI is pursuing larger, public market deals, exposing them to competitive auctions and higher purchase multiples. There is evidence that the internal hurdle rates may be slipping as they pursue these larger deals, although it’s hard to parse out the signal from the noise in the ROIIC at this stage.
The protective factors that have led to exceptional capital allocation historically - disciplined capital allocation, decentralized structure and aligned incentives - remain in place. Further, the net working capital dynamic is a tailwind that will continue to exist.
Going forward, CSI’s valuation will depend entirely on management’s ability to resist overpaying for growth while managing the sheer organizational complexity of its expanding portfolio. We are confident that its structure and culture will remain in place.
With the benefit of hindsight, shares were a steal sub $2500 CAD, and are still very likely undervalued. Sometimes, dollar bills are laying on the ground for us to pick up!
Thanks for reading. Feel free to leave a comment below.
Happy Compounding! 📈
Todays article is free and so if you enjoy it please share!
Disclaimer: We are private investors and not financial advisors. This post is for educational purposes only and does not constitute financial advice. Constellation Software Incorporated (CSU) is a stock we currently own. Always conduct your own due diligence before making any investment decisions.
Well researched, enlightening
Trevor, I have been following CSI for a long time. This is the best analysis I have seen, and further enhances my confirmation bias of a wonderful investment. Thank you. Ralph