Selling software has become the trade of late, and if you hold any software names you’ve likely felt the tremors. The “SaaSmageddon” narrative - the fear that Artificial Intelligence (AI) will compress the terminal value of software companies to zero - has moved from a fringe theory to a central topic in boardrooms and investment committees.
The anxiety is palpable. For two decades, the investment thesis for B2B SaaS was the closest thing to a “free lunch” in finance: recurring revenue, high gross margins (80%+), and negligible churn. If a company hired more people, they bought more seats. Revenue grew linearly with headcount. It was a beautiful, predictable machine.
And then, AI came along.
The arrival of “Vibe Coding” - the ability for non-technical users to build software through natural language prompting - and autonomous AI agents has shattered the unit economics of the seat-based model.
If an AI agent can do the work of three junior analysts, why do you need three Salesforce licenses? If a marketing manager can “vibe code” a bespoke internal tool to track inventory, why pay $20k a year for a rigid point solution?
Look deeper and we see that the prevailing narrative that “SaaS is dead” is lazy. It lacks nuance. We are not witnessing an extinction event; we are witnessing a great bifurcation. The market is not discriminating between the vulnerable and the protected, it instead just assumes all will be crushed by the AI avalanche.
We’ve seen this play out before. About fifteen years ago there was the great debate between the System of Record (SoR) and the System of Engagement (SoE). The emergence of AI creates another layer - the System of Intelligence (SoI).
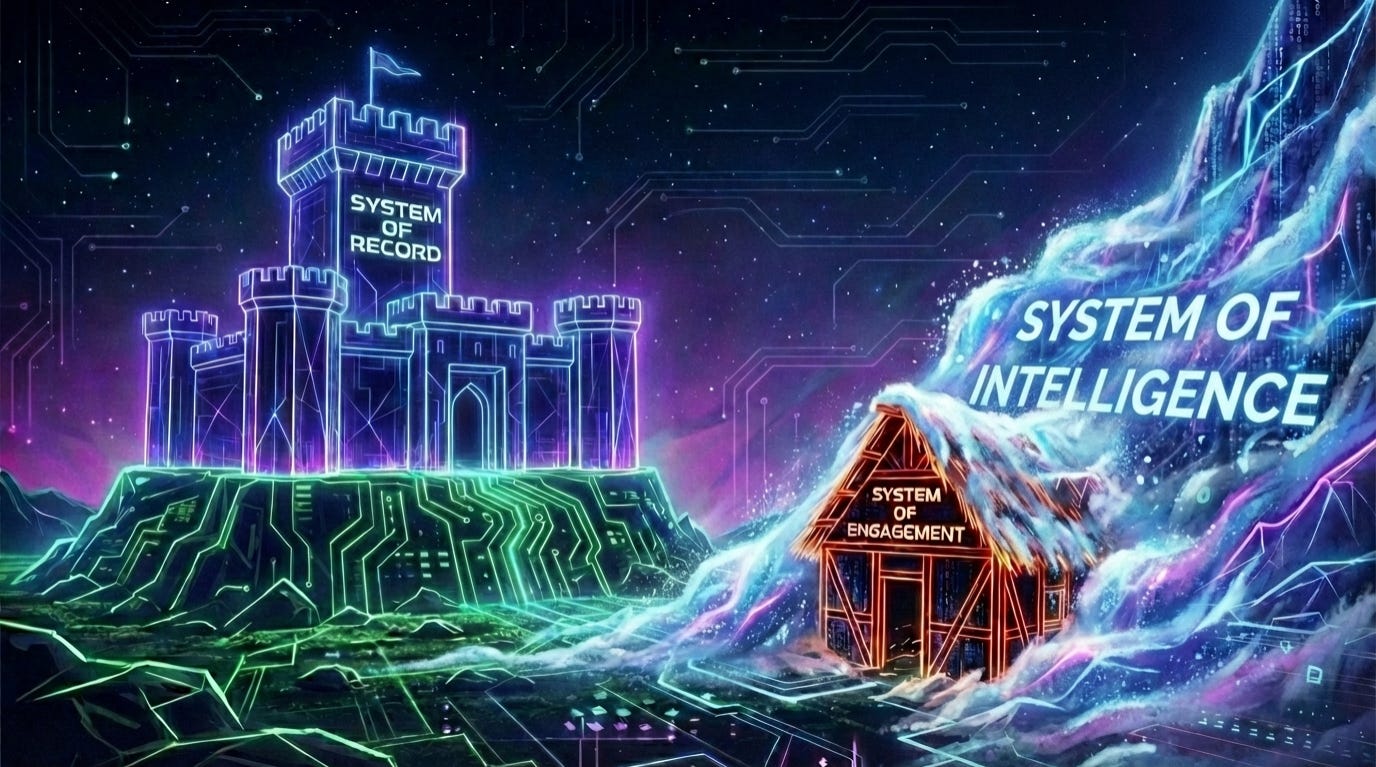
In this post we aim to deconstruct the history of this shift and provide a filtering framework to assess for Castles vs. Cottages.

The Mechanism of Disruption
To understand why the market is selling off SaaS stocks, we must understand the deflationary pressure of AI on code itself.
Vibe Coding and the Collapse of “Hard” Software
In 2025, the term “vibe coding” went mainstream. It refers to a shift in software development where the user describes the intent (the “vibe”) of an application in natural language, and an LLM handles the syntax, libraries, and deployment. This is not just a productivity hack for developers; it is a demolition of the barrier to entry for software creation.
Historically, B2B SaaS companies charged a premium because building software was hard. You paid a vendor $50/month per user because hiring engineers to build a custom tool cost $500,000. Today, a CIO or a savvy department head can ask an advanced model to “write a Python script that takes this CSV of employee shifts, applies these three rules, and emails the schedule to everyone.”
Software development is now becoming commoditized. We are seeing a massive shift in the “Build vs. Buy” equation. For the first time in twenty years, “Build” is becoming cheaper, faster, and more flexible than “Buy”.
Assets, Access and Agents
One further consideration is the reliance on the seat-based pricing model. This model assumes that value is delivered to a human user. In an AI-native world, value is delivered by the completion of a task.
We are witnessing the evolution of a new software business model in real time, like the emergence of a new species. The primitive species was monetization by selling software tools (assets). The next evolutionary event was monetization by selling subscriptions to those tools (access). Now, an even more advanced species is emerging, which sells outcomes (agents). With the introduction of the new species, the ecosystem has changed.
The recent market volatility is a manifestation of that ecological change. Seat based models are now transitioning to consumption-based pricing - charging per API call, per transaction, or per resolved workflow. For example, Salesforce (CRM) is monetizing Agentforce, Einstein AI and Salescloud with a consumption-based model.
It’s important though to pay attention to the unit economics. If a company successfully deploys an AI agent that performs the work of three junior analysts, the customer may drop three $100/month licenses in favor of a single consumption-based agent.
Seat-based subscription revenue is linear and easy to model; consumption revenue is variable and lumpy. As Castles like Salesforce or Adobe begin to trade stable license fees for variable transaction fees, the quality of their revenue technically degrades in the eyes of the market.
Unless the consumption volume explodes immediately to offset that churn, the software vendor effectively cannibalizes its own predictable, recurring revenue stream in the pursuit of modernization. The revenue “trough” before the eventual “climb” creates market concern and volatility.
The Historical Echo (2011 vs. 2026)
Systems of Record vs. Systems of Engagement - 2011
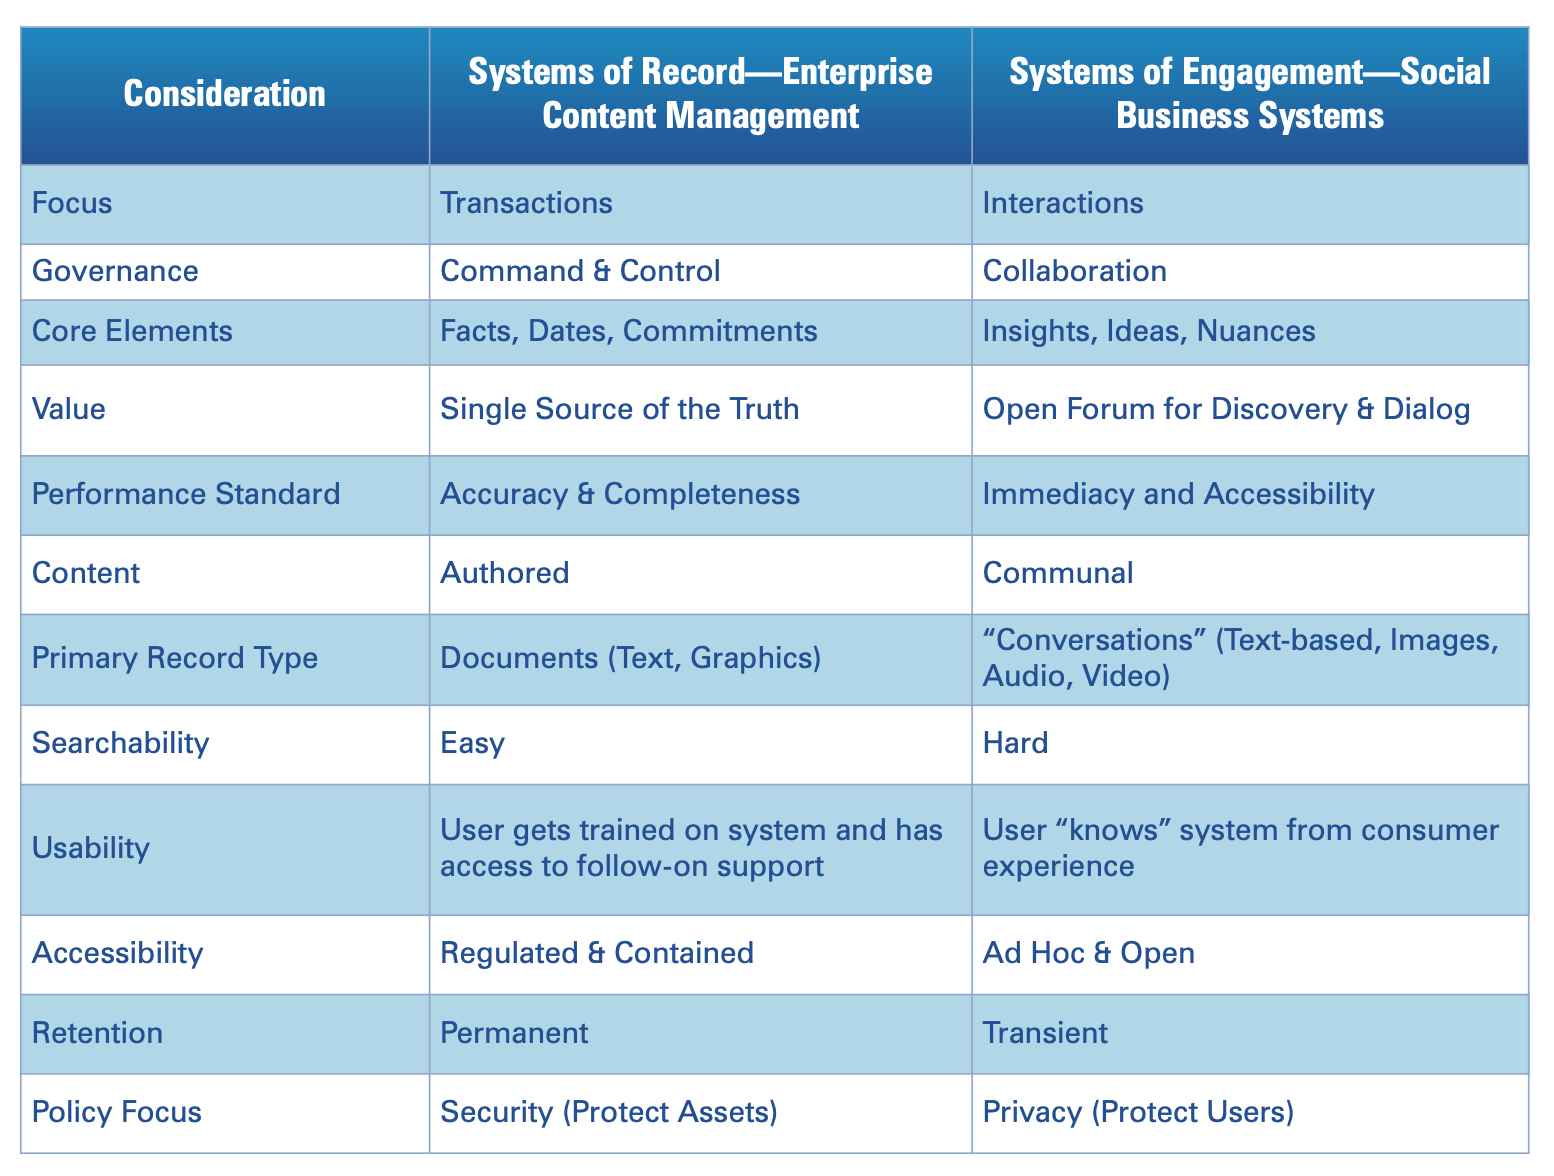
The terminology was popularized by Geoffrey Moore (author of Crossing the Chasm) in a 2011 AIIM white paper.
Moore argued that traditional IT had spent decades building Systems of Record (SoR) - ERPs like SAP and Oracle - which were designed for transactions, compliance, and “truth.” However, they were clunky and hated by users.
At the time Moore predicted a shift toward Systems of Engagement (SoE). Driven by the iPhone and Facebook, employees demanded software that was social, mobile, and collaborative.
Investors bet billions that the value would migrate from the “command and control” database (SoR) to the “collaborative” interface (SoE).
This era birthed a wave of companies that were essentially “Facebook for the Enterprise.” They were the “vibe coding” wrappers of their day - a user interface (for social interaction) sitting on top of data they didn’t own.
Jive Software (JIVE)
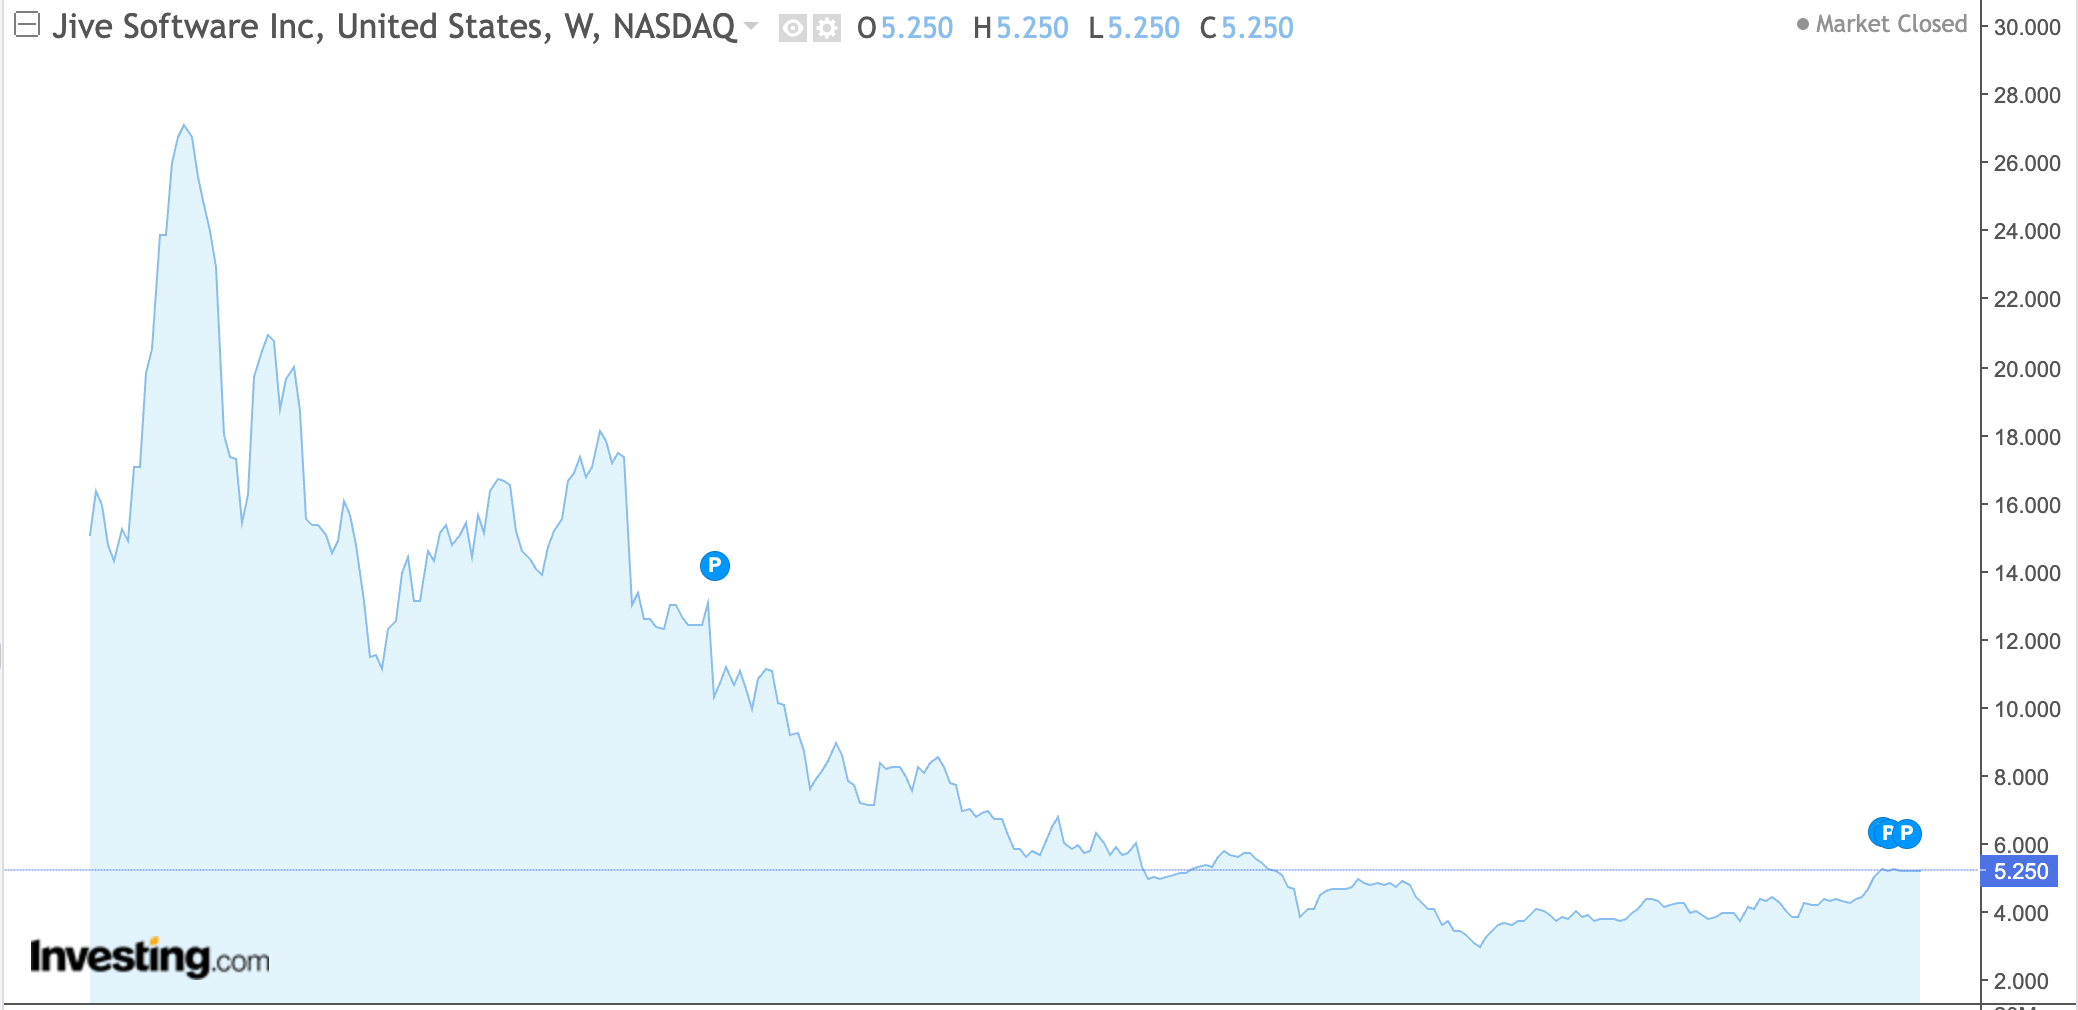
Jive was the ultimate SoE. It promised to be the social layer connecting all your employees, the “Facebook for enterprise”. It went public in 2011 at a share price of $12 and a market cap of about $700 million. Shortly after IPO it more than doubled before peaking at ~$28 / share.
However, Jive didn’t own the data. It was just a place to talk about work, not do work. It was disrupted as soon as SoRs added SoEs on top of their databases. When the SoRs “social” features to their own Systems of Record, Jive became redundant. For example, Microsoft built SharePoint and acquired Yammer (incorporated it into the Office line of products), while Salesforce built Chatter and acquired Slack in 2019
Subsequently, after IPO Jive’s stock collapsed to ~$4 before being taken private in 2017 for $5.25 per share.
The lesson here is that engagement is a feature, not a product. Inherently, System of Engagement (SoE) are easy to switch. If you stop posting on Jive, the value disappears instantly.
System of Record (SoR) are Impossible to switch. The SoR is the operating system of the business. The company cannot turn off the Vertical Market Software (VMS - e.g. Constellation Software), the Enterprise Resource Planner (ERP - e.g. SAP) or Customer Relationship Manager (e.g. Salesforce) without massively disrupting the workflows of the company.
What about Slack?
Slack too started as an SoE, so why did it survive while Jive died? Salesforce acquired Slack in 2021 for ~ $27 billion, two years after a direct listing on the NASDAQ with a market cap of about $24 billion.
What set Slack apart from Jive, and other SoEs that went bust?
User Data Aggregation: Although Slack was first and foremost an SoE, by allowing users to aggregate data onto its platform (tying into databases like Google Drive or example) it created a switching cost for the user.
Network Effects: Slack integrated with over a thousand other apps, aggregating multiple SoEs onto its platform to create a unified ecosystem. It also allowed users across companies to communicate and interact. These features brought more users onto slack, which in turn, strengthened the value proposition of its ecosystem and made it harder to leave. It also retained all data that could be accessed in a user friendly, searchable manner, encouraging users to retain more data on the platform.
Workflows: Slack has an embedded “Workflow builder” that is easy to use. By creating such a product, Slack becomes part of the de facto business operating system for its users. The deeper the workflow integration, the harder it is to rip out.
Ultimately these three factors - User Data Aggregation, Network Effects, and Workflow integration - created a high switching cost that is not innate to an SoE.
System of Intelligence - 2026
In 2017 Jerry Chen updated the framework to include a third layer - the System of Intelligence.
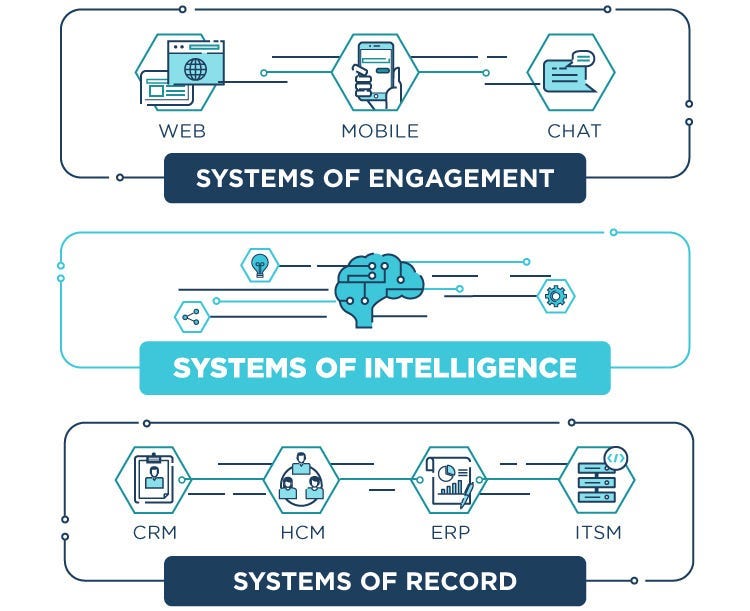
Chen writes:
What makes a system of intelligence valuable is that it typically crosses multiple data sets, multiple systems of record. One example is an application that combines web analytics with customer data and social data to predict end user behavior, churn, LTV, or just serve more timely content. You can build intelligence on a single data source or single system of record but that position becomes harder to defend against the vendor that owns the data. - Source
Chen’s idea applied to 2026 this is the AI Agent, SLM, or LLM that is flashy and boosts productivity. However, the SoI requires data to function. As Chen notes, the SoI is only as valuable as the data source.
We can reframe the SoE and SoR discussion with this third variable - the SoI. The SoI can exist within the SoE or the SoR, so long as it has access to data. So, if the data accessed by the SoE is public, then there’s a high probability the SoE can be disrupted by the SoI.
Consider Duolingo (DUOL). At its core, it is a user interface (SoE) that uses publicly accessible data (language, math, physics, rules of chess, etc.) to teach its users. A SoI, with access to this public data, can recreate the SoE based on the preference of the creator. This specific SaaS application is now commoditized by the SoI.
On the other hand, consider Constellation Software Incorporated (CSU). It is a serial acquirer for vertical market software (VMS) companies. The VMS is literally the operating system of the business (SoR) and without the VMS, the business can’t operate. For example, a construction management company may use a VMS to track and coordinate all its active projects, while scheduling, invoicing, and collecting payment from subcontractors. Without this SoR the construction management company cannot function - the workflows are 100% dependent on the VMS.
Adding an SoI enhances the value proposition of the SoR. Rather than replacing the SoR, AI agents entrench it further. The more an enterprise uses AI to analyze its data, the more valuable the underlying database becomes - a phenomenon known as Data Gravity. Companies that own the data can further monetize their SoR by charging a “toll” for AI agents to access it, effectively protecting their revenue streams.
Moving forward, the SaaS winners will not be the companies that build the best agent, but the companies that own the data and the SoR. Otherwise, the SoI is just going to commoditize the SoE. The only thing protecting the SoE from being disrupted by the SoI is the presence of switching costs.
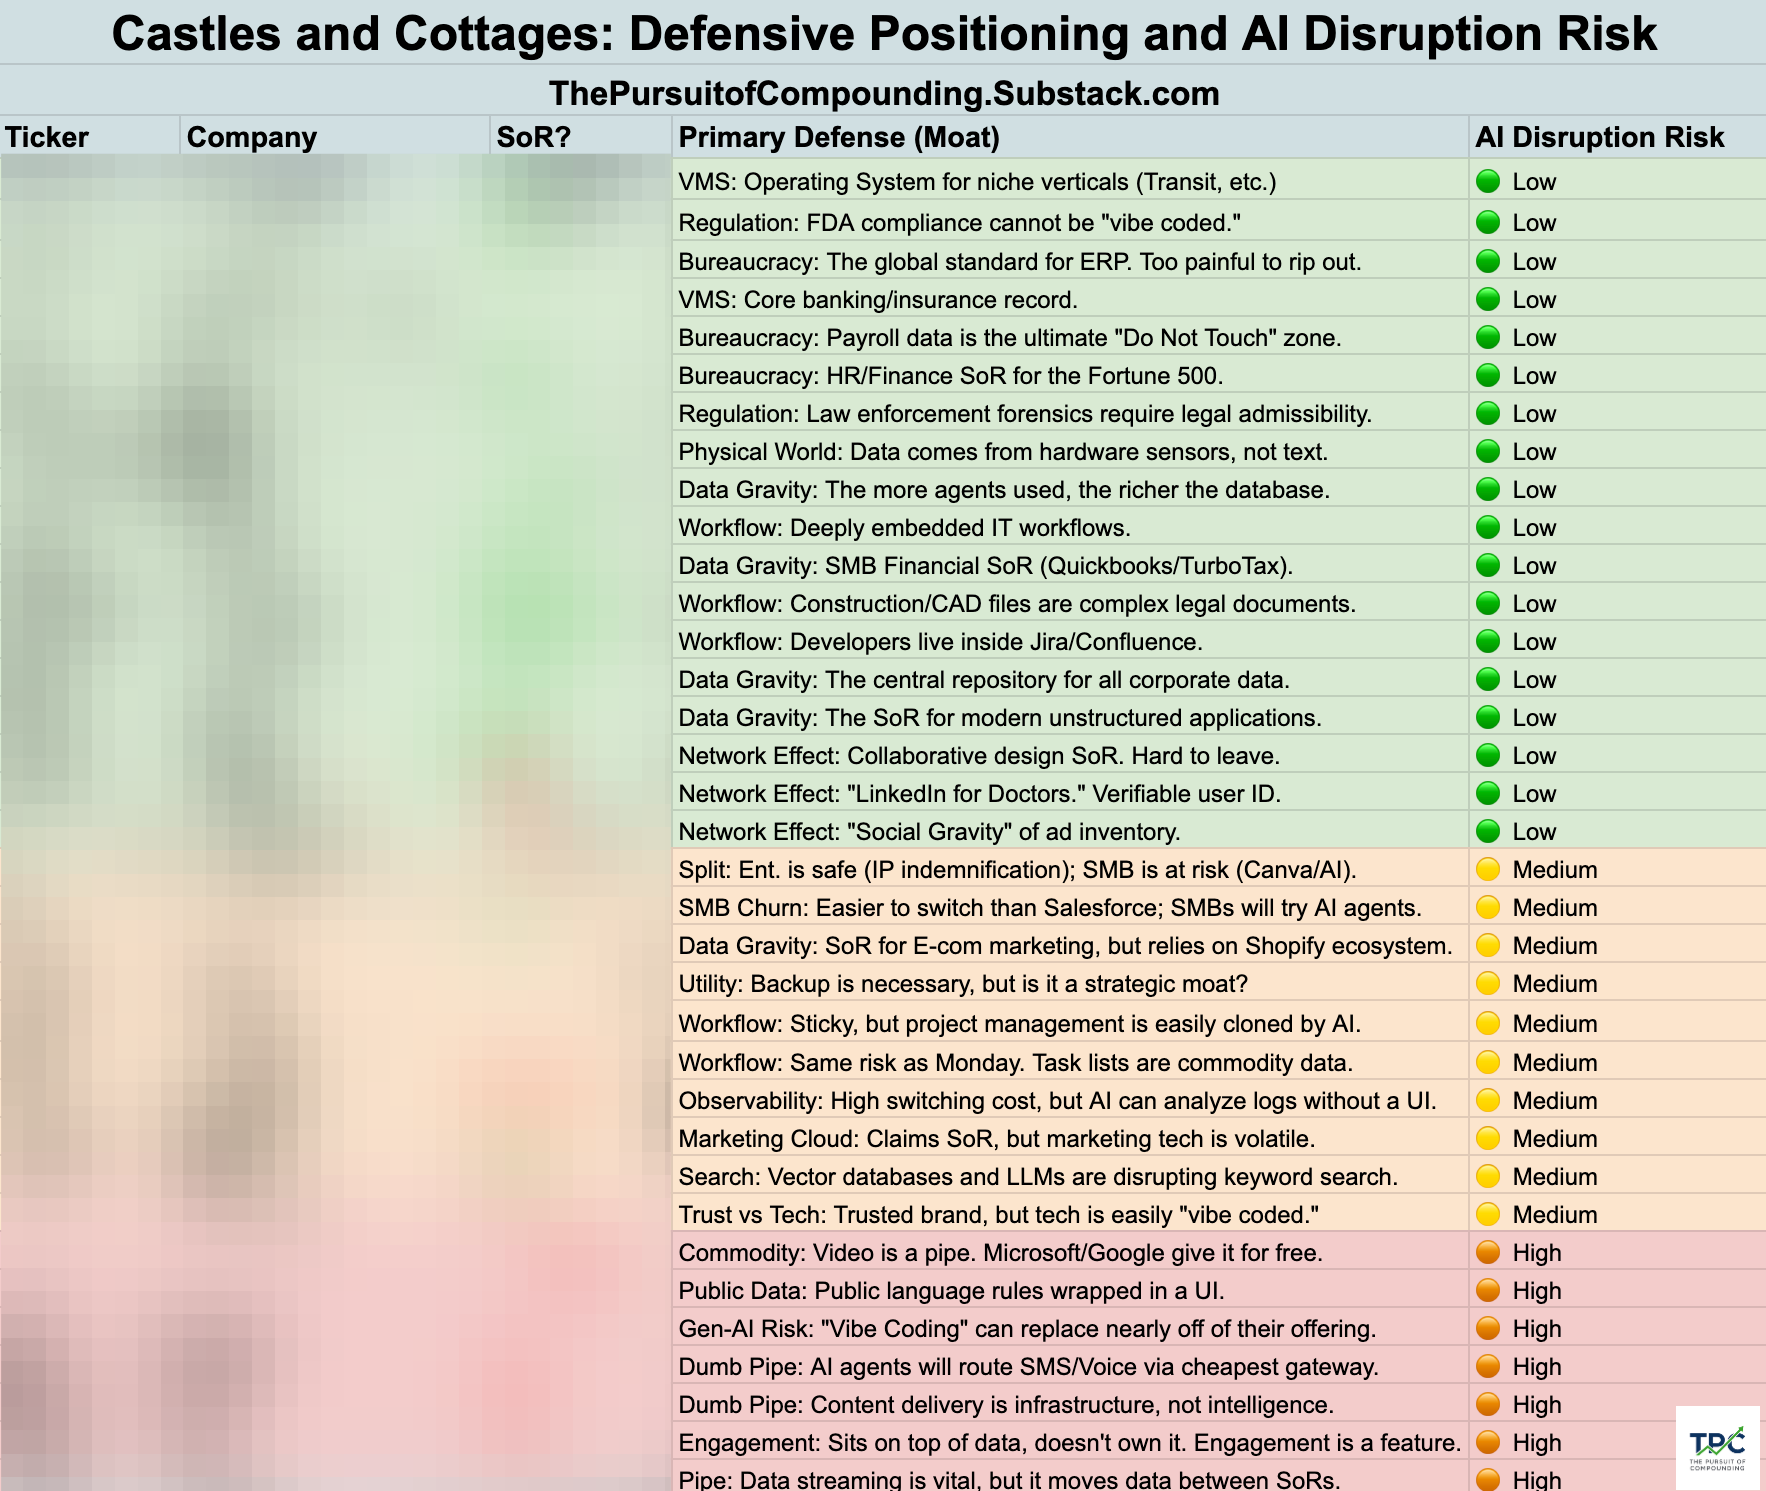
Paid subscribers will see the full framework and rank order of over 30 SaaS companies below.