

Created with Gemini Nano Bananna
On November 19 2025, Adobe announced it is acquiring Semrush for $1.9 billion in cash. To the casual observer, this looks like a boring software consolidation: the giant with too much money swallowing a toolmaker to buy growth.
But if you look closer—specifically at the tectonic shifts happening in how humans find information online—this deal is much more interesting. It isn’t just about buying a keyword tool. It’s about Adobe securing the future of discovery.
For the last two decades, Adobe has owned the “creation” layer of the internet. If you see a logo, a video, or a banner ad, it was likely made in Photoshop or Premiere. Although they do have some competition with upstarts like Figma and Canva, here they dominate, especially with enterprise customers.
With its Experience Cloud, Adobe is also involved in the “content management” layer—storing that content, distributing it across the internet, and providing data and analytics for customer relationship management (CRM). Unlike at the creation layer, in the content management / CRM business Adobe faces fierce competition. Companies like SalesForce, Oracle, SAP, HubSpot are massive in size and scale. There are also smaller upstarts like Sitecore, Optimizely, Bloomreach, and Insider.
Further, Adobe has always had a blind spot - they lacked the “visibility” layer. They could help you make beautiful content, store it, and give you the CRM data about it, but they couldn’t tell you if anyone will actually find it.
Historically this is called “Search Engine Optimization” (SEO) It’s about improving the quality and quantity of website hits through traditional discovery means - search engines.
With the rise of AI - specifically Agentic AI - SEO is quickly being disrupted and evolving into Generative Engine Optimization (GEO). Now, instead of just optimizing for a human with a search engine, marketing firms need to think about the work flows involving Generative AI Agents.
By acquiring Semrush, Adobe isn’t just buying a SaaS company; they are buying a map to this Generative AI Agentic future. And they are doing it just as the roads are being repaved by Artificial Intelligence for Artificial Intelligence.
The Death of “Ten Blue Links”
To understand this deal, you have to understand the existential crisis facing every Chief Marketing Officer (CMO) right now.
For 25 years, the game was simple with SEO. You wrote content, you got backlinks, and you prayed to the Google algorithm to rank you in the “ten blue links.”
That era is ending. We are entering the age of GEO.
First and foremost, the ten blue links are being disrupted by Gemini AI summaries.
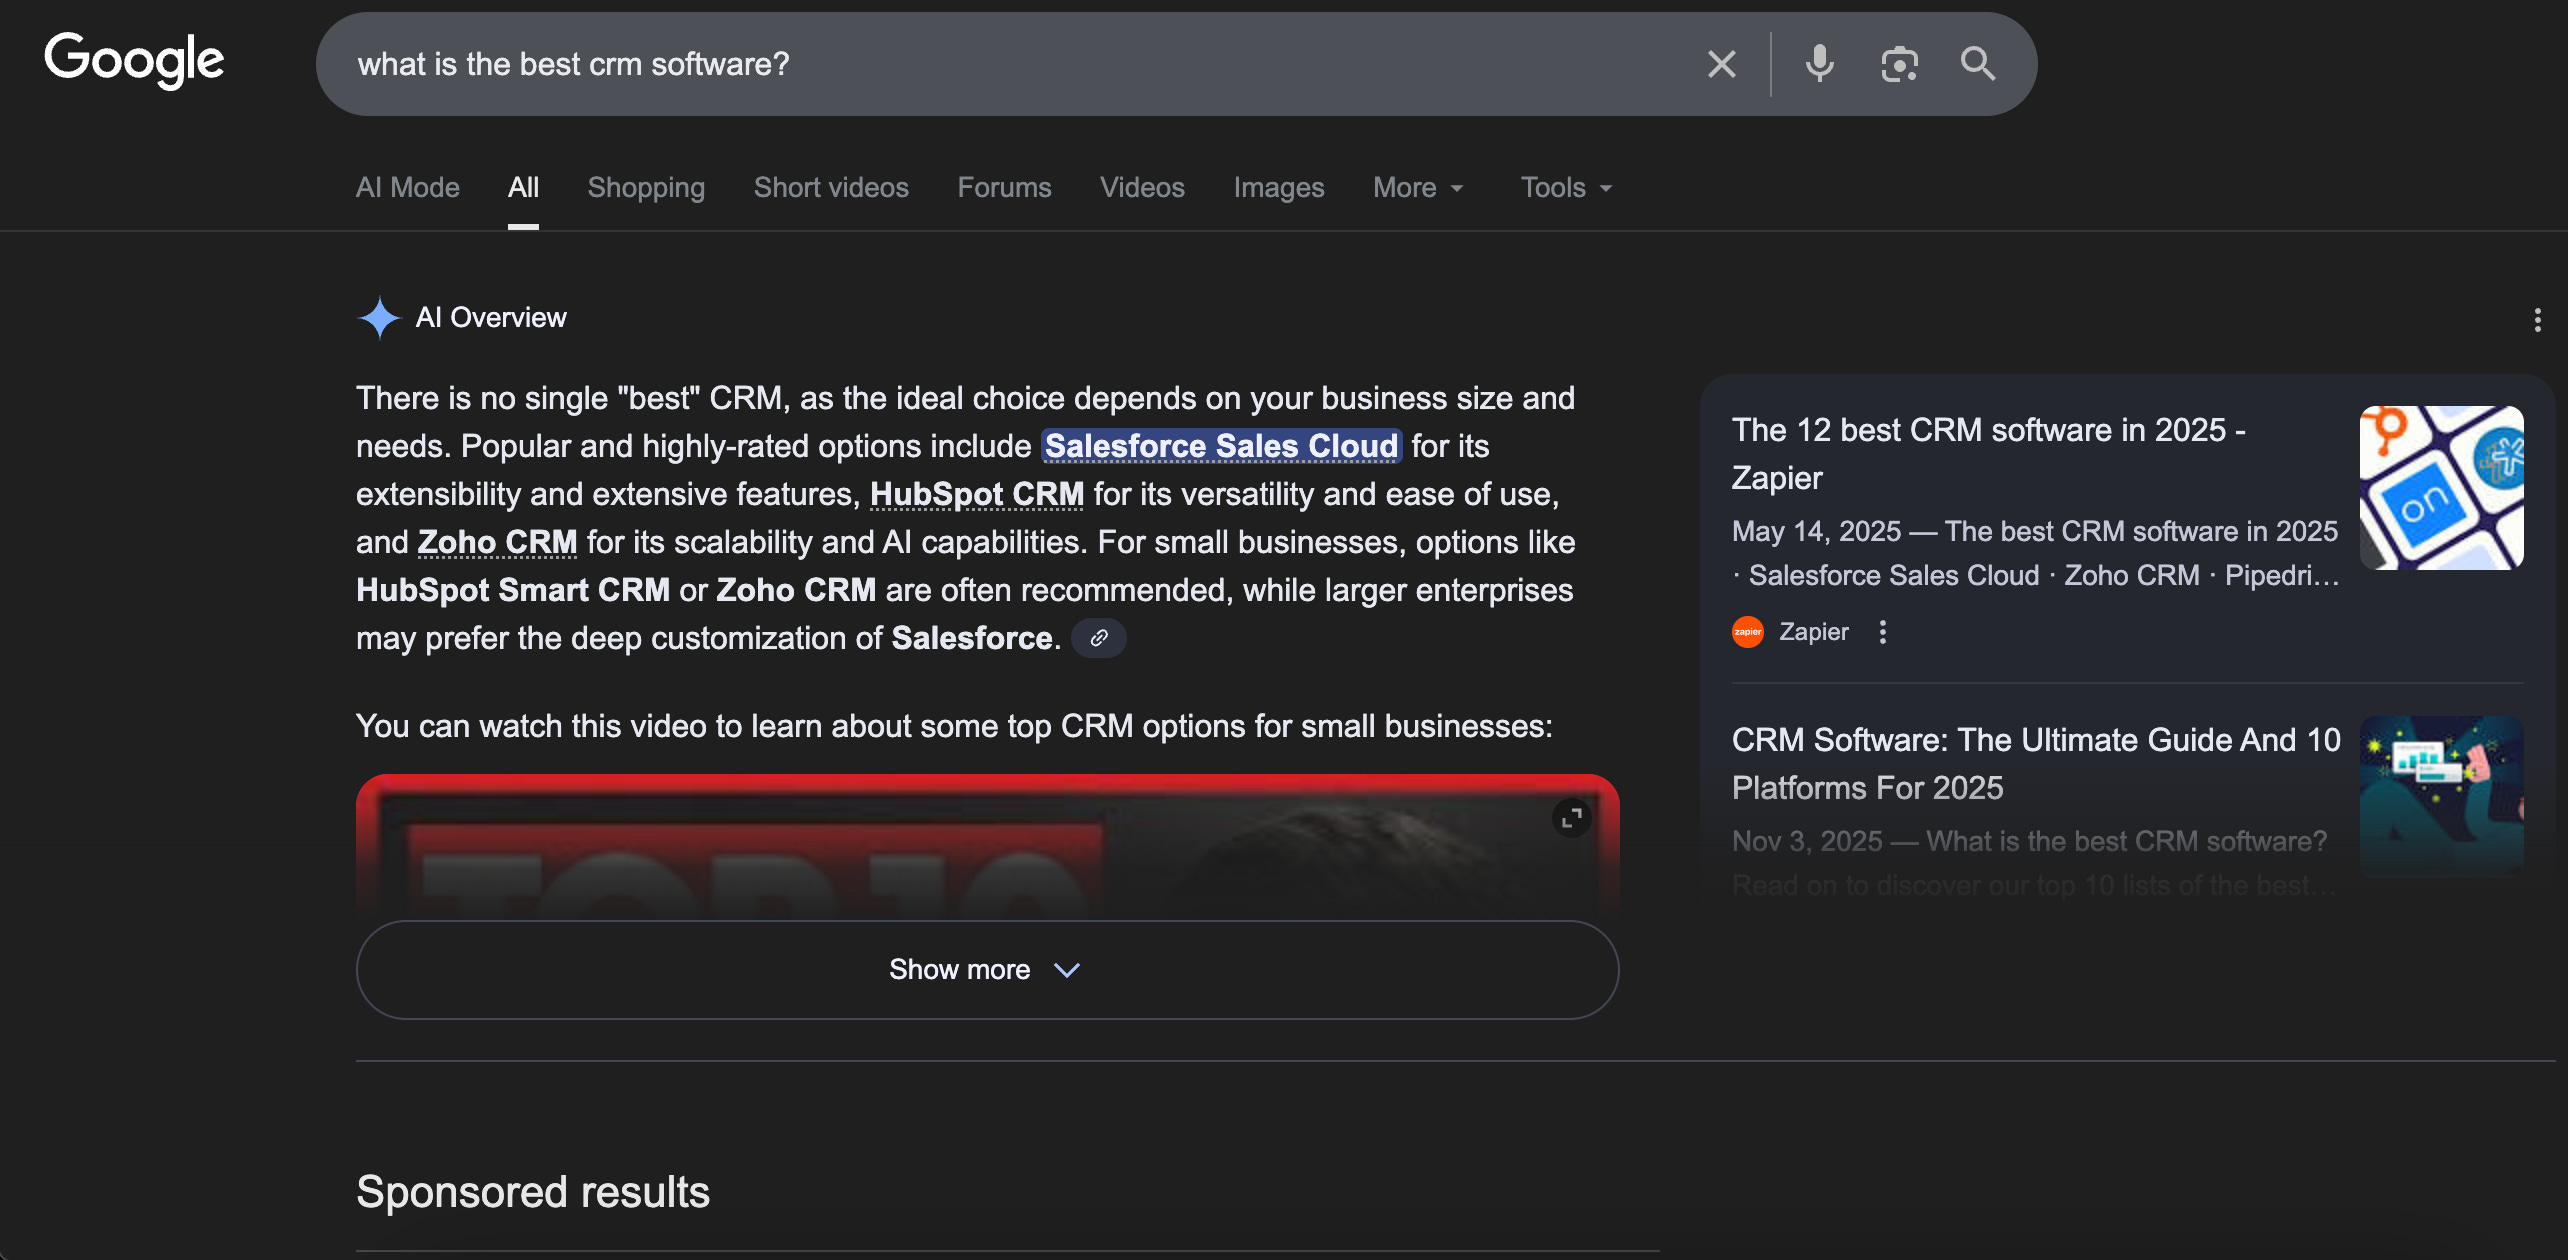
Author Google search on Nov 20, 2025
Further, research indicates that when the Gemini AI overview is present, Google search users click links 50% less than when the overview is absent.
But users’s aren’t only just typing “what is the best CRM software” into Google for their research. Increasingly they are asking Gemini, ChatGPT, Claude, etc to “Compare and contrast the best CRM software for SMB”
The AI gives an answer. It cites sources. And, if your brand isn’t in that answer, you may as well not exist.
This is a terrifying “black box” for brands. In the old world, you could track your rank. In the new world, visibility is opaque, depending on the whims of the agentic AI model of the day. This is where Semrush comes in. While Adobe was busy building Firefly to generate images, Semrush was pivoting its entire backend to track visibility in Large Language Models (LLMs). They crawl 17 billion URLs a day and track 33 trillion backlinks. They possess the raw data required to reverse-engineer why an AI recommends one brand over another.
For Adobe, this greatly increases their value proposition. They can now go to a Fortune 500 CMO and say: “We won’t just help you build and manage your content. We will ensure the AI agents actually find it.”
The Asset: The Data
Semrush is often dismissed as a tool for SEO freelancers. This underestimates the asset. Building a web crawler that indexes the entire internet daily is a non-trivial engineering problem. It costs tens of millions of dollars in infrastructure and years of tuning to navigate robots.txt files, JavaScript rendering, and IP bans.
There are only a handful of entities that have a live, high-fidelity index of the web: Google, Microsoft (Bing), Ahrefs, and Semrush.
Adobe didn’t buy Semrush for its $455 million in Annual Recurring Revenue (ARR). They bought it because building this data infrastructure from scratch would probably take years. In the AI arms race, years is an eternity.
By integrating this data into the Adobe Experience Manager (AEM), Adobe creates a closed loop. Imagine a content editor in AEM writing a product description. The Semrush integration could pop up and say: “Warning: This phrasing has 0% visibility in ChatGPT. Try this phrasing instead to increase citation probability by 40%.”
That is a feature that justifies a massive contract renewal for Adobe. It increases the value proposition of their CRM tools. It increases switching costs. It deepens their moat.
The Valuation: Buying Growth on Sale?
Let’s talk about the price tag. $1.9 billion. At first glance, paying a ~74% premium over the previous trading price looks rich. But context is everything.
Semrush was trading at a depressed valuation—roughly 2.2x revenue—largely because small-cap SaaS stocks have been hammered by high interest rates and fears that AI would kill SEO (which is likely true).
Adobe is paying $12.00 per share, which implies a valuation multiple of roughly 3.7x TTM revenue ($1.6B Enterprise Value / $428M Revenue).
Compare this to 2021, when similar SaaS companies traded at 15x or 20x revenue. Adobe is effectively buying a high-quality asset at a pawn-shop price relative to historical norms.
Furthermore, the deal is financially sound on a standalone basis:
Semrush Gross Margins: ~82-83%. This is elite software economics.
Multiple Arbitrage: Adobe trades at roughly 9x-10x revenue. There is an immediate arbitrage here. Adobe buys revenue at 3.7x and instantly re-rates it to its own multiple.
Customer Acquisition: Semrush spends heavily to acquire customers (mostly SMBs). Adobe already has contracts with 99% of the Fortune 100. They can cross-sell Semrush as an add-on to existing enterprise licenses with virtually zero Customer Acquisition Cost (CAC).
The Risks: Can Adobe Integrate This?
The bull case is clear, but the bear case is execution.
Adobe has a mixed history with M&A. The acquisition of Omniture (now Adobe Analytics) was a massive success that defined the industry. The acquisition of Magento (Commerce) has been rockier, facing stiff competition from Shopify. Figma was not approved by regulators.
We think there will be no anti-trust concerns and that this deal will likely get regulatory approval. The risk here then is cultural and technical. Semrush is a product-led growth (PLG) company with a “hacker” culture. Adobe is a classic enterprise sales organization. If Adobe wraps Semrush in too much bureaucracy, the engineers who maintain those complex crawlers might leave. If the data quality degrades, the asset becomes worthless.
Also, OpenAI or Google could simply release tools that make third-party visibility tracking obsolete. If ChatGPT releases a “Brand Dashboard” for free, Semrush loses its edge. However, independent verification would still be valuable. Brand may not trust Google to tell them how they rank on Google, nor would they trust Google Gemini to tell them how they rank with ChatGPT. Due to the number of popular LLMs / agents they would still likely need a neutral third party.
The Verdict
We see this is a defensive maneuver that doubles as an offensive land grab.
Defensively, this acquisition protects Adobe users from the SEO to GEO disruption. It also prevents a competitor like Salesforce or HubSpot from buying this data moat. Offensively, it positions Adobe for success as the Agentic web continues to develop, increasing Adobe’s CRM value proposition, while also adding further switching costs.
As we move toward a future where AI agents do our shopping, booking, and researching, the battle for attention changes ground. It’s no longer about grabbing human eyeballs; it’s about grabbing AI citations.
With this $1.9 billion acquisition, Adobe just positioned itself to stake a claim on that future, buying a map of this future Agentic internet.
What do you think about this acquisition? Feel free to tell us in the comments below!
Happy Compounding! 📈
PS: Like what you read? Buy us a coffee!
Disclaimer: We are private investors and not financial advisors. This post is for educational purposes only and does not constitute financial advice. We have a long position in ADBE. Always conduct your own due diligence before making any investment decisions.